Sodium-Ion Battery Electrode Production Surges in May: Tight Capacity, Cost Pressures, Q3 Expansion Ahead

Published: Jun 05, 2026 16:45 (GMT+8)
In May, key materials for sodium-ion batteries sustained their strong momentum, with both cathode and hard carbon anode recording sharp YoY and MoM growth. Top-tier players’ order books were full and capacity utilization rates approached their limits. On the supply side, the pattern of rising volumes and stable prices was pronounced, yet pressure to pass on rising raw material costs was also building.

In May, key materials for sodium-ion batteries sustained their strong momentum, with both cathode and hard carbon anode recording sharp YoY and MoM growth. Top-tier players’ order books were full and capacity utilization rates approached their limits. On the supply side, the pattern of rising volumes and stable prices was pronounced, yet pressure to pass on rising raw material costs was also building. Meanwhile, capacity expansion expectations for Q3 became progressively clearer, setting the stage for the sodium-ion battery industry chain to scale up in H2.

Cathode Material: Surge in Demand Boosts Capacity Utilization, Cost Pressures Force Price Increases 

In May, production of sodium-ion battery cathode material rose 17% MoM and 21% YoY. The polyanion route accounted for as much as roughly 87% of output, with NFPP’s share up 5 percentage points MoM, further cementing its dominance. Top cathode enterprises progressively delivered orders, but available capacity had become a bottleneck, creating an undersupply situation. Simultaneously, leading players intensively launched next-generation products in May, offering comprehensive performance upgrades that continuously enhanced the competitiveness of sodium-ion batteries in application scenarios. On the supply side, leading cathode plants had begun preparing for capacity expansion, and a significant release of sodium-ion battery cathode capacity is expected in Q3.
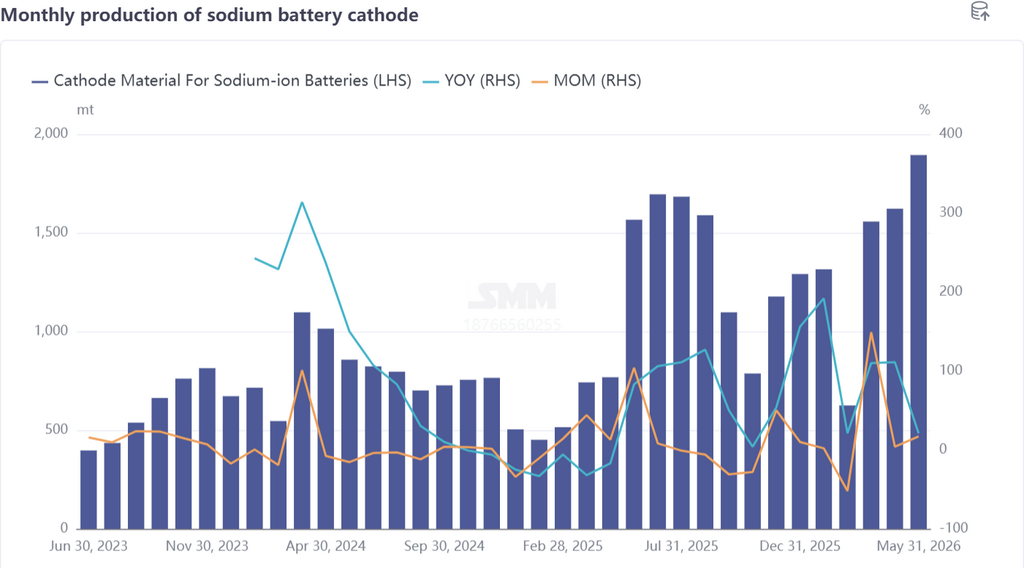
 

However, the current order boom was heavily concentrated among top-tier players. Midstream cathode producers, constrained by capacity scale, continued to produce based on demand, send samples for validation, and develop clients at a gradual pace, and had yet to fully benefit from the demand surge.
Cost side, NFPP raw material costs continued to climb in May: iron phosphate prices rose, and sodium salts such as monosodium phosphate and sodium pyrophosphate also surged. Although mass production scale had improved from earlier and production line processes had been upgraded, the broad-based rise in raw material prices still drove a significant cost increase. Consequently, NFPP prices are expected to increase going forward, to ease cost pressure. In terms of product structure, the share of layered oxide cathodes narrowed further, market concentration continued to rise, and demand was concentrated in niche applications such as two-wheelers and start-stop power supplies.

The layered oxide segment faces the challenge of accelerating contraction. Looking ahead to June, demand for sodium-ion battery cathodes remains on an upward trajectory, production schedules are expected to continue growing, and June output is projected to increase 1% MoM and 24% YoY.

Hard Carbon Anode: Full Capacity Utilization, Toll Processing to Fill Gaps, Sustained Premium for Quality Products 

In May, production of sodium-ion battery anode materials rose 26% MoM and surged 154% YoY, moving in tandem with the cathode side. Leading hard carbon enterprises are in the capacity ramp-up stage, with ample orders on hand and new orders continuing to improve.Shortfalls from insufficient existing capacity are being covered through external toll processing. Recently, some hard carbon producers have brought new capacity on stream, and as this capacity is gradually ramped up and released, the supply side of sodium-ion battery anodes is expected to see a notable boost in Q3. 
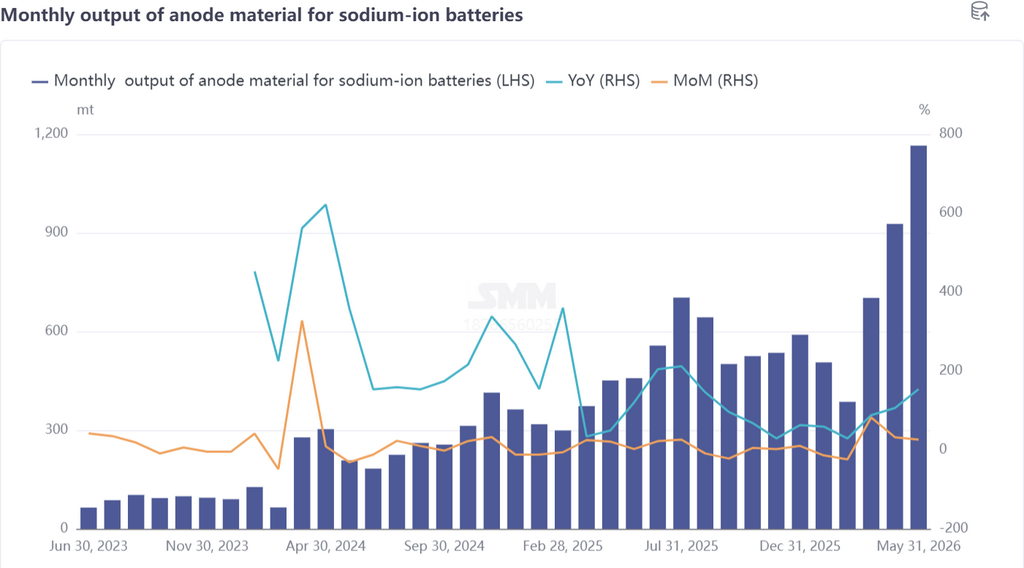
On the price front, premiums for high-performance hard carbon products remain firm. Hard carbon grades with outstanding cycle life, low-temperature performance, and C-rate capabilities are primarily used in energy storage, start-stop, and other applications, with prices generally above 30,000–40,000 yuan/mt and high-end products reaching 50,000–60,000 yuan/mt.

The price spread between premium hard carbon and ordinary products reflects the market’s differentiated pricing logic based on material performance. Looking ahead to June, demand for hard carbon anodes remains favorable, with production expected to increase 9% MoM and 128% YoY. 

Summary 

Overall, the sodium-ion battery cathode and anode material market in May exhibited three core characteristics: First, a pronounced top-tier effect, with orders and capacity expansion concentrated among a few leading enterprises, while mid- and tail-end producers have yet to enter the volume ramp-up stage.Second, cost-side pressure, as rising upstream raw material prices are forcing cathode product prices higher, putting profitability to the test. Third, the pace of capacity expansion is accelerating, and capacity release in Q3 will be a key variable for the scale leap of the sodium-ion battery industry chain in H2. Structurally, the dominance of the polyanion route has been further reinforced, while the space for layered oxide cathodes continues to narrow, making the landscape of technological divergence increasingly clear. Looking ahead to June and Q3, as capacity is gradually brought on stream and demand continues to flow in, the sodium-ion battery material market is expected to enter a new phase of rising volumes and prices.


Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.

For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
[SMM Cobalt Morning Meeting Summary] Post-holiday demand recovery limited, cost support weakening, material prices under pressure
Oct 09, 2026 10:31 (GMT+8)
[SMM Cobalt Morning Meeting Summary] Post-holiday demand recovery limited, cost support weakening, material prices under pressure
Read More
[SMM Cobalt Morning Meeting Summary] Post-holiday demand recovery limited, cost support weakening, material prices under pressure
[SMM Cobalt Morning Meeting Summary] Post-holiday demand recovery limited, cost support weakening, material prices under pressure
The cobalt industry chain remained weak after the holiday, with sluggish demand and lower costs jointly weighing on prices. Refined cobalt consolidated at lows, traders raised spot-futures price spreads, and downstream buying remained primarily need-based restocking. Trading in intermediate products stalled, with a clear gap between the floor purchase price of $14.5/lb and downstream acceptance prices below $13/lb. Cobalt sulphate offers held near 60,000 yuan/mt, but transactions were difficult, and a lower raw material coefficient further weakened cost support. Cobalt chloride and Co3O4 continued to grind lower, enterprises expanded production cuts and suspensions, and new procurement was insufficient. Leading cobalt powder offers fell to around 360,000 yuan/mt, while small and medium-sized enterprises dropped to 330,000–340,000 yuan/mt, with downstream high-priced inventory dragging on purchases. Ternary cathode precursor prices weakened, export orders were relatively strong, domestic production schedule recovery was limited, and spot order coefficients were expected to trend lower. Ternary cathode materials consolidated at lows, battery cell manufacturers held ample inventory and restocked cautiously; LCO was pressured by both falling costs and weak demand. Going forward, close attention should be paid to end-user order recovery, inventory destocking, and the sustainability of restocking.
Oct 09, 2026 10:31 (GMT+8)
[SMM Cobalt-Lithium Morning Meeting Summary] Post-holiday lithium chemical trends diverge; LFP demand improves, materials market under pressure
Oct 09, 2026 10:21 (GMT+8)
[SMM Cobalt-Lithium Morning Meeting Summary] Post-holiday lithium chemical trends diverge; LFP demand improves, materials market under pressure
Read More
[SMM Cobalt-Lithium Morning Meeting Summary] Post-holiday lithium chemical trends diverge; LFP demand improves, materials market under pressure
[SMM Cobalt-Lithium Morning Meeting Summary] Post-holiday lithium chemical trends diverge; LFP demand improves, materials market under pressure
Post-holiday battery materials market trends diverged. Lithium ore quotes rebounded slightly, trade inventories were destocked, and ore prices are expected to consolidate in line with lithium carbonate in the short term. Lithium carbonate futures retreated after a rapid rise, closing at 117,300 yuan/mt, down 1.28%; domestic production declined, downstream inventories were significantly destocked, and salt plants continued to ship mainly under long-term contracts. Lithium hydroxide spot order quotes rose to 130,000–140,000 yuan/mt, but purchasing was cautious and transactions were sluggish. Cobalt products and nickel sulphate remained under pressure, cost support weakened, and demand recovery for ternary cathode materials was limited. LFP orders were relatively strong, leading production lines were near full capacity, finished product inventories declined, and the average price rose to 50,400 yuan/mt; resistance to iron phosphate price increases grew. Artificial graphite had strong cost support, separators were driven by NEV, energy storage, and export rush demand, with a tight supply-demand balance; electrolytes rose due to earlier cost pass-through. In the recycling market, inquiries recovered, but transactions had yet to pick up volume. Going forward, attention should be paid to the sustainability of restocking, the realization of production schedules, and changes in raw material prices.
Oct 09, 2026 10:21 (GMT+8)
Sodium-ion Battery September-October Peak Season in Progress: Holiday Break Does Not Alter Tight Balance [SMM Analysis]
Oct 08, 2026 09:32 (GMT+8)
Sodium-ion Battery September-October Peak Season in Progress: Holiday Break Does Not Alter Tight Balance [SMM Analysis]
Read More
Sodium-ion Battery September-October Peak Season in Progress: Holiday Break Does Not Alter Tight Balance [SMM Analysis]
[SMM Analysis: Sodium-Ion Battery "September-October Peak Season" Underway: Holiday Break Does Not Alter Tight Balance] SMM, October 8: During the National Day holiday, the sodium-ion battery industry chain largely continued the pre-holiday pattern, with no significant changes...
Oct 08, 2026 09:32 (GMT+8)