[SMM Analysis] Cost-Driven Price Game: Market Trend Analysis of 314Ah ESS Battery Cells

Published: Jan 27, 2026 19:37
Source: SMM
From Q4 2025 to early 2026, the global ESS industry chain's upstream raw material market underwent a significant price restructuring. The current battery cell market is in a period of intense competition between "losses" and "delayed price transmission." As battery cell manufacturers generally raised their quotations, the subsequent transaction price levels may continue to rise.

From Q4 2025 to early 2026, the global ESS industry chain's upstream raw material market underwent significant price restructuring. The battery cell market is currently in an intense period of balancing between losses and delayed price transmission. As battery cell manufacturers generally raised their quotations, the central transaction price may continue to rise in the subsequent period.

I. Upstream Raw Material Market: Lithium Chemicals Lead the Gains, Core Materials Surge Across the Board
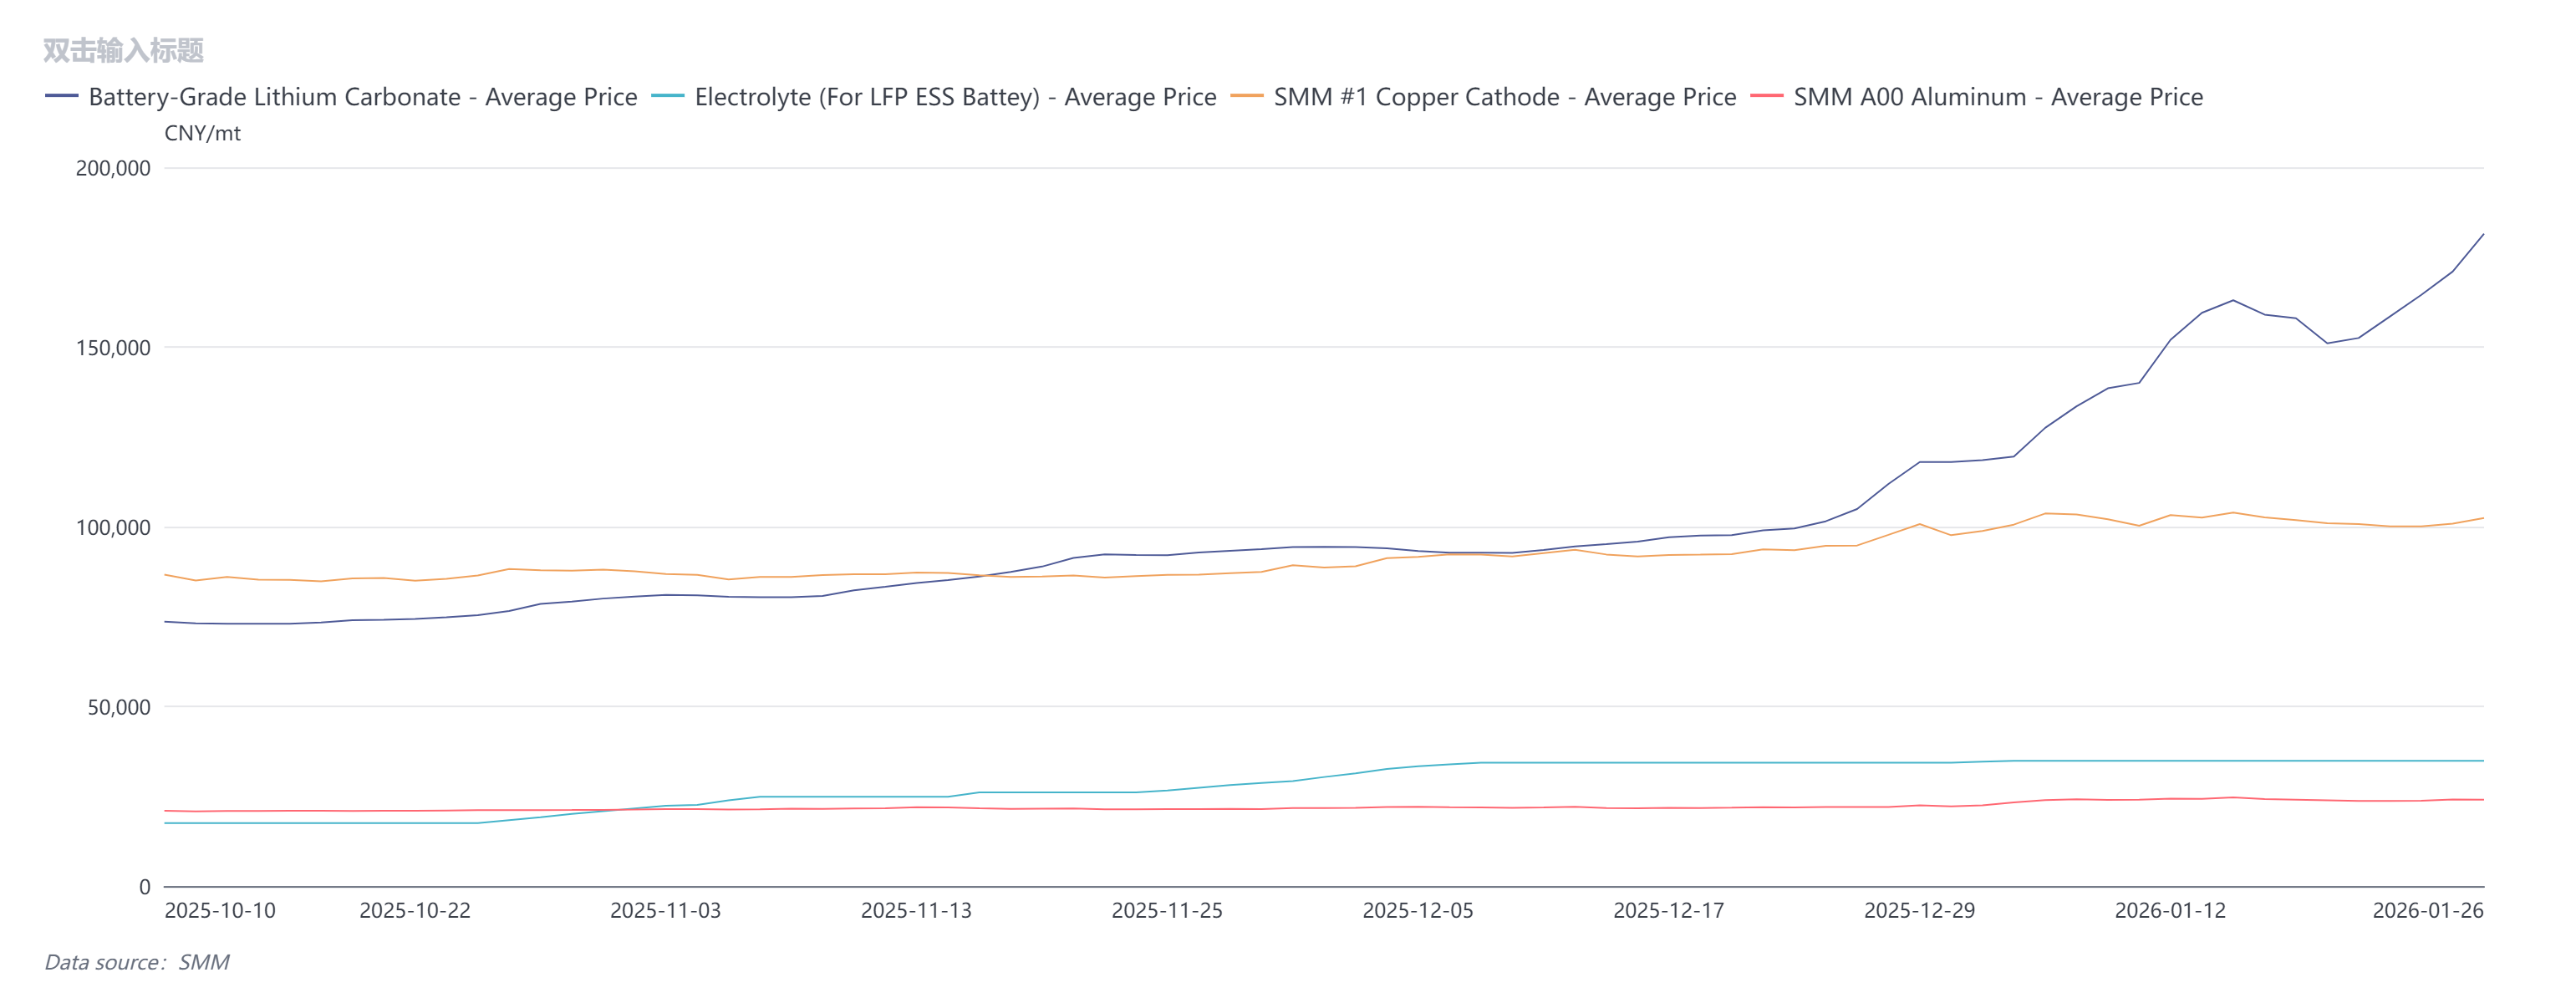
Reviewing the market performance from October 10, 2025, to January 26, 2026, the four key raw materials for ESS battery cells—cathode source (lithium carbonate), electrolyte, anode current collector (copper), and cathode current collector (aluminum)—all showed a unilateral upward trend. Among them, lithium chemicals and electrolyte exhibited explosive increases.
As the core variable determining battery cell cost fluctuations, battery-grade lithium carbonate displayed the most aggressive price movement. According to SMM, the average price of SMM battery-grade lithium carbonate surged from 73,550 yuan/mt in October 2025 to 181,500 yuan/mt on January 26, 2026, an increase of 107,950 yuan/mt, up 146.77%. This doubling growth directly reshaped the BOM cost structure of battery cells. Driven by LiPF6 and solvent prices, the price of SMM electrolyte for ESS (for LFP ESS) rose from 17,550 yuan/mt to 34,850 yuan/mt, an increase of 17,300 yuan/mt, up 98.58%, nearly doubling, significantly raising auxiliary material cost pressure in cell manufacturing.
Additionally, the steady rise in base metals further solidified the cost floor. SMM #1 copper cathode also continued to surge recently, climbing from 86,680 yuan/mt at the beginning of Q4 2025 to 102,435 yuan/mt recently, up 18.17% (+15,755 yuan/mt). During the same period, A00 aluminum prices mildly increased from 20,980 yuan/mt to 24,030 yuan/mt, up 14.54% (+3,050 yuan/mt). The steady rise in copper and aluminum prices further elevated the base cost level of current collectors and structural components, leading to a further increase in battery cell costs.
II. Significant Surge in Theoretical Cost of 314Ah Battery Cells Driven by Cost Transmission Mechanism
Based on the sharp fluctuations in raw material prices mentioned above, a theoretical cost model calculation was conducted for the mainstream 314Ah energy storage battery cells:
Initial Cost (October 2025): When raw material prices were relatively low, the theoretical cost of 314Ah battery cells was approximately 0.2798 Yuan/Wh.
Current Cost (January 2026): Driven directly by the doubling of lithium carbonate and electrolyte prices, coupled with increases in copper and aluminum prices, the current theoretical cost has risen to 0.3683 Yuan/Wh.
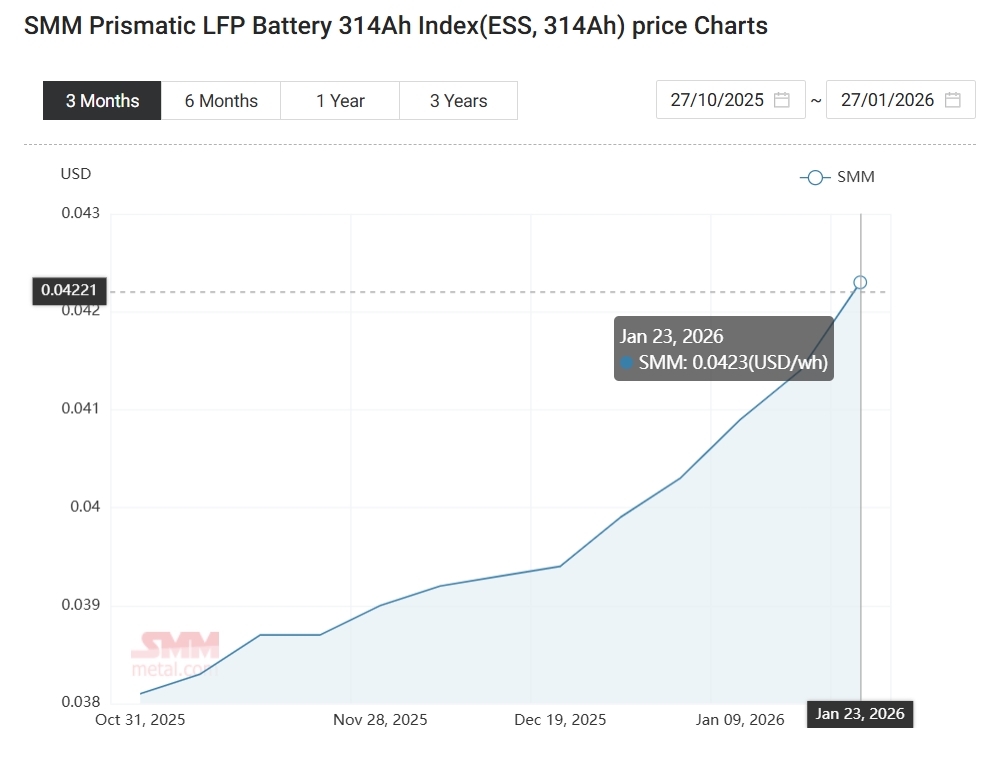
In just three and a half months, the theoretical cost per Wh surged by 0.0885 Yuan/Wh, an increase of about 31.6%. This indicates that the rise in raw material costs is not a mild linear transmission but rather a step-like sharp increase. Although a qualitative change has occurred on the cost side, the spot transaction prices of ESS battery cells have shown significant lag. According to the SMM 314Ah ESS battery cell price index, during the same period, the index rose from 0.2995 Yuan/Wh to 0.3339 Yuan/Wh, revealing a substantial gap between price and cost.

III. Cause Analysis
The current index price (0.3339 yuan/Wh) is significantly lower than the theoretical cost (0.3683 yuan/Wh). This inverted phenomenon, where “flour is more expensive than bread,” may be attributed to the following reasons:
1. The market currently relies mainly on consuming previously accumulated low-cost raw material inventory to sustain deliveries, with some battery cell manufacturers maintaining market share at the expense of profits or even by operating at a loss.
2. Downstream (integrators/end-users): There is strong resistance to rapid price increases, with low acceptance, and the market is still in a phase of price negotiation and re-establishing price benchmarks.

IV. Market Outlook
At this stage, upstream (battery cell manufacturers): Faced with irreversible increases in raw material prices, battery cell manufacturers can no longer maintain their original pricing systems. Market quotations have already reacted proactively, with some prices raised to around 0.35–0.39 yuan/Wh in an attempt to restore profit margins.
Looking ahead, as low-cost inventory is gradually cleared, cost pressures will become more apparent. With the depletion of previously accumulated low-cost lithium carbonate inventory, battery cells produced in the new cycle must bear the current high raw material costs. The price center of the 0.3339 yuan/Wh index is expected to shift upward. The current higher quotation range reflects not only the break-even demands of battery cell manufacturers but also serves as a defense against future raw material uncertainties. As downstream projects commence and rigid delivery requirements approach, the industry chain will be compelled to increase its acceptance of higher prices. The price of 314Ah ESS battery cells may conclude its delayed adjustment phase and enter a round of catch-up increases.


Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.

For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
[SMM News] Premier, Canmax Extend Long Stop Date on Zulu Lithium Offtake Agreement to December 31
9 hours ago
[SMM News] Premier, Canmax Extend Long Stop Date on Zulu Lithium Offtake Agreement to December 31
Read More
[SMM News] Premier, Canmax Extend Long Stop Date on Zulu Lithium Offtake Agreement to December 31
[SMM News] Premier, Canmax Extend Long Stop Date on Zulu Lithium Offtake Agreement to December 31
On September 14th, 2026, London-listed Premier African Minerals agreed with Canmax Technologies to extend the long stop date under their restated offtake and prepayment agreement for the Zulu lithium and tantalum project in Zimbabwe, originally signed in August 2023, to December 31. Premier, Zulu Lithium Private, and Canmax also signed a tripartite priority and subordination agreement, giving Canmax contractual priority over amounts owed by Zulu Lithium to Premier and other Premier group members. Other terms remain unchanged. Amounts owed to Canmax, including outstanding prepayment and accrued interest, rank as senior indebtedness about $48.73-million as at September 10. Amounts owed by Zulu Lithium to Premier, including loans, advances, and intercompany balances, rank as subordinated indebtedness about $55.75-million. Premier MD Graham Hill said the extension provides time and certainty to progress Zulu and reach a long-term resolution with Canmax, while the subordination agreement clarifies creditor positions and preserves Premier's claims against Zulu Lithium.
9 hours ago
[SMM News] Frontier Lithium Taps DRA Americas for Updated PAK Feasibility Study, Targets Q1 2027 Release
9 hours ago
[SMM News] Frontier Lithium Taps DRA Americas for Updated PAK Feasibility Study, Targets Q1 2027 Release
Read More
[SMM News] Frontier Lithium Taps DRA Americas for Updated PAK Feasibility Study, Targets Q1 2027 Release
[SMM News] Frontier Lithium Taps DRA Americas for Updated PAK Feasibility Study, Targets Q1 2027 Release
TSX-V-listed Frontier Lithium has appointed DRA Americas to conduct an updated feasibility study on its PAK lithium project in Ontario, Canada. The study will incorporate work completed since the 2025 feasibility study, including value engineering results, with a focus on optimising project economics and derisking execution. Publication is expected in Q1 2027. Frontier Lithium continues to advance permitting and consultation for PAK under Ontario's One Project, One Process framework, alongside Indigenous engagement, environmental studies, and infrastructure initiatives. CEO Trevor Walker said the update aims to capture progress made to date and position the project's "Mine and Mill" stage for its next phase, citing PAK's high grade lithium resource, Ontario location, and rising North American demand for secure domestic critical mineral supply. The move reflects a broader push by North American jurisdictions to build domestic lithium supply chains as automakers and battery makers look beyond China-linked sources, with the updated study marking a standard step toward a final investment decision.
9 hours ago
[SMM News] Vulcan Energy Secures Second Production Licence for Lionheart Project in Germany
9 hours ago
[SMM News] Vulcan Energy Secures Second Production Licence for Lionheart Project in Germany
Read More
[SMM News] Vulcan Energy Secures Second Production Licence for Lionheart Project in Germany
[SMM News] Vulcan Energy Secures Second Production Licence for Lionheart Project in Germany
Australia and Frankfurt-listed Vulcan Energy has secured a second lithium production licence, valid six years, for its Lionheart project in Germany, currently under construction. The new Ilka licence follows an earlier grant covering the LiThermEx area, making it the second such licence issued in the Upper Rhine Valley Brine Field and Rhineland-Palatinate state. Lionheart's first phase targets 24,000 t/y of lithium hydroxide monohydrate, enough for about 500,000 EVs annually, alongside 275GWh of renewable power and 560GWh of heat per year from its integrated geothermal component, over an estimated 30 year project life. The Ilka licence expires September 2032, after which Vulcan will seek to merge its two production licences into one. CEO Cris Moreno said the licence validates progress toward becoming Europe's leading low-cost lithium producer, with construction on track for first production in 2028. Lionheart combines brine based lithium extraction with geothermal power, positioning it to supply EV battery-grade lithium hydroxide into the European market without reliance on imported spodumene or carbonate feedstock.
9 hours ago
[SMM Analysis] Cost-Driven Price Game: Market Trend Analysis of 314Ah ESS Battery Cells - Shanghai Metals Market (SMM)