Copper prices may regain steam on supportive fundamentals and bets on further US rate cuts

Published: Sep 18, 2025 18:18 (GMT+8)
Source: SMM
Copper prices may regain steam on supportive fundamentals and bets on further US rate cuts

The US Fed cut interest rates overnight as expected, by 25 basis points to a range of 4.00%-4.25%, the lowest level in nearly three years, breaking a nine-month streak of unchanged decisions. According to media reports, "Officials judged that the recent weakness in the labour market has outweighed the resistance from recurring inflation. Slightly more than half of the officials expect at least two more rate cuts this year, implying possible consecutive actions at the remaining two meetings in October and December."

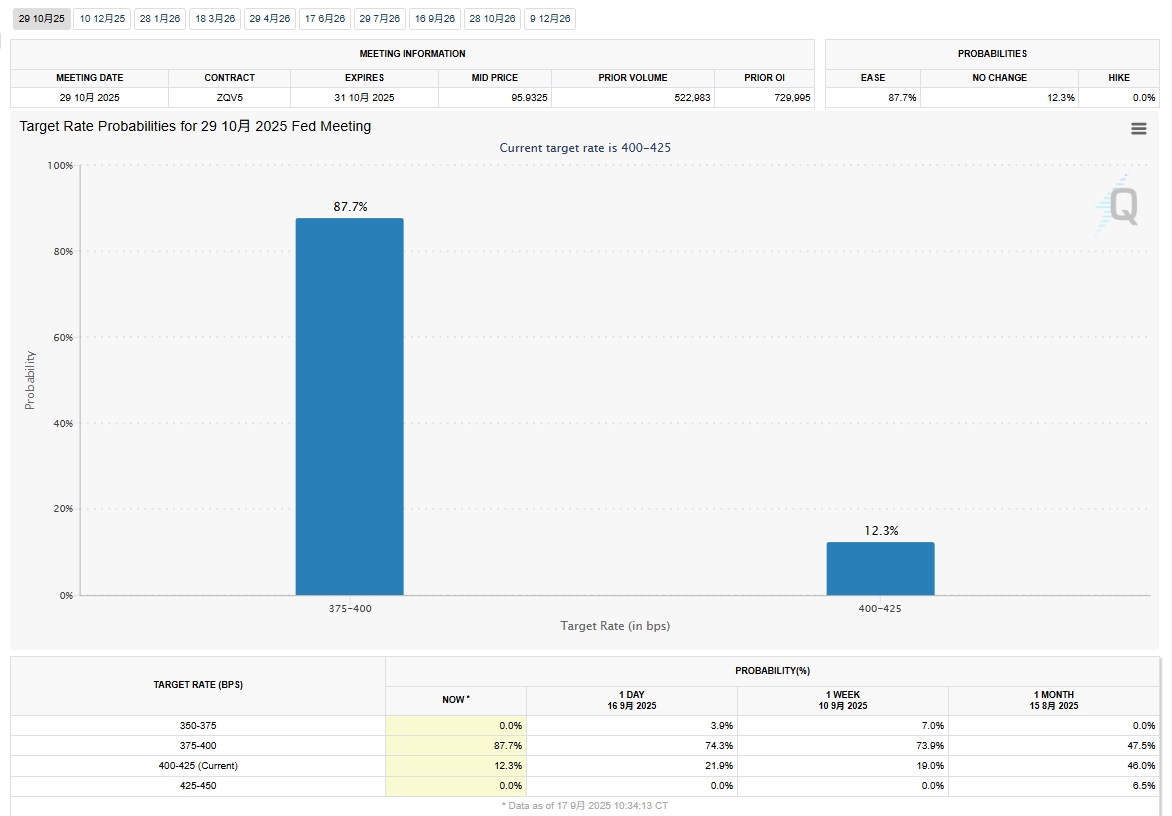
According to the latest data from FedWatch, the probability of the US Fed cutting rates by another 25 basis points in October is 87.7%, significantly higher than before; the probability of no change is only 12.3%.

Data source: FedWatch Tool
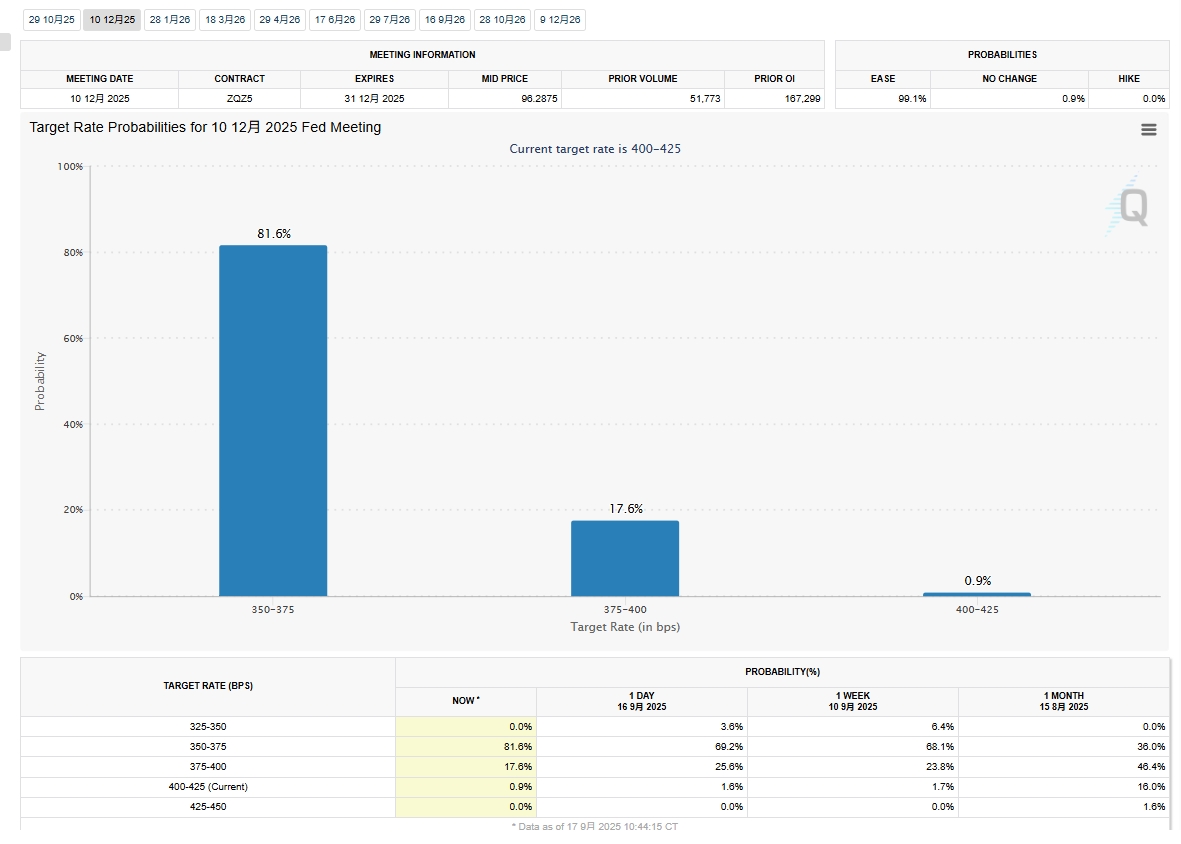
The probability of the US Fed cutting rates by another 25 basis points in December to 3.50%-3.75% on top of November's move has risen to 81.6%, while the probability of maintaining the October cut of 25 basis points to 3.75-4.00% is 17.6%; 0.9% still believe there will be no rate cuts in October or December, meaning rates would remain at 4.00%-4.25%.

Data source: FedWatch Tool
With the September rate cut implemented, the macro tailwinds have temporarily "come to an end." Yesterday afternoon, LME copper led the trading session, with bulls exiting positions. It closed with a long bearish candlestick accompanied by a long lower shadow, hitting a low of $9,927/mt. Overnight, SHFE copper opened lower with a gap, falling below the 80,000 yuan/mt level and probing a low of 79,690 yuan/mt, attracting substantial downstream point pricing of previous orders. The futures then gradually rebounded to fluctuate rangebound between 79,800-79,960 yuan/mt.

Observing the market's reaction to this round of copper price decline from a micro fundamental perspective:
In the morning session, the SHFE copper 2510 contract continued to rise from a low of 79,740 yuan/mt. During the concentrated trading period for spot transactions, the futures briefly touched the 80,000 yuan/mt level again but "faded quickly," indicating a lack of market confidence in copper prices above 80,000 yuan/mt. In the afternoon session, as LME copper declined, SHFE copper opened with a downward trend. Trading activity below 79,800 yuan/mt increased, with the front-month contract reducing positions by over 17,000 lots.

Trading activity significantly increased in the morning session. Most smelting and trading enterprises achieved actual shipments of 500-3,000 mt each between 9:30-11:30. Downstream users shifted from only picking up long-term contracts and just-in-time procurement to increasing spot orders and advance stockpiling.

Based on SMM's exchanges with enterprises:
Smelter 1: Shipments increased MoM from yesterday, with the premium center rising by 20 yuan/mt. Downstream point pricing was relatively active.
Smelter 2: Shipments increased MoM from yesterday, with the premium center rising by 10-20 yuan/mt. Inventories in the Changzhou area were depleted within the day.
Trader 1: Shipments increased MoM from yesterday, and point pricing was active during the overnight night session, but 80% were previously tentative orders. The selling price center rose during the day, with non-registered purchases being the most active.
Trader 2: Shipments increased MoM from yesterday, with low-priced sources being snapped up. Some downstream users inquired about future arrivals, likely preparing for National Day holiday procurement.
Downstream 1: Only picked up long-term contracts yesterday but made spot purchases today. There were new orders, but growth was mild rather than explosive. The procurement price was 10 yuan/mt higher than the spot offers heard yesterday.
Downstream 2: Procurement orders today were 1,000 mt more than yesterday. Stockpiling for the National Day holiday began gradually from yesterday, but order growth remained mild. Non-registered prices were 30 yuan/mt higher than yesterday's procurement price.

Summary:
The September rate cut did not exhaust the bullish factors. The market sensed weak demand at high copper prices and grew concerned about the upside room for copper prices. However, as copper prices fell by just 1,000 yuan/mt, market demand gradually released, with support emerging at 79,500 yuan/mt. If precious metals continue to retreat, copper prices are expected to fall to the 79,000-79,500 yuan/mt range. With only eight trading days left before the National Day holiday, demand is expected to improve.

Supply side: Domestic copper cathode supply remains tight amid concentrated maintenance at domestic smelters in September and October and unclear policies on copper scrap. Import supplements are expected to increase, but production cuts of copper cathode in Africa may impact October supply.
Demand side: Although large-scale downstream stockpiling for the National Day holiday was not widely felt this week, large enterprises are expected to gradually increase daily procurement volume next week. If copper prices reach 79,000 yuan/mt, consumption sentiment is expected to improve further next week, and destocking will accelerate.
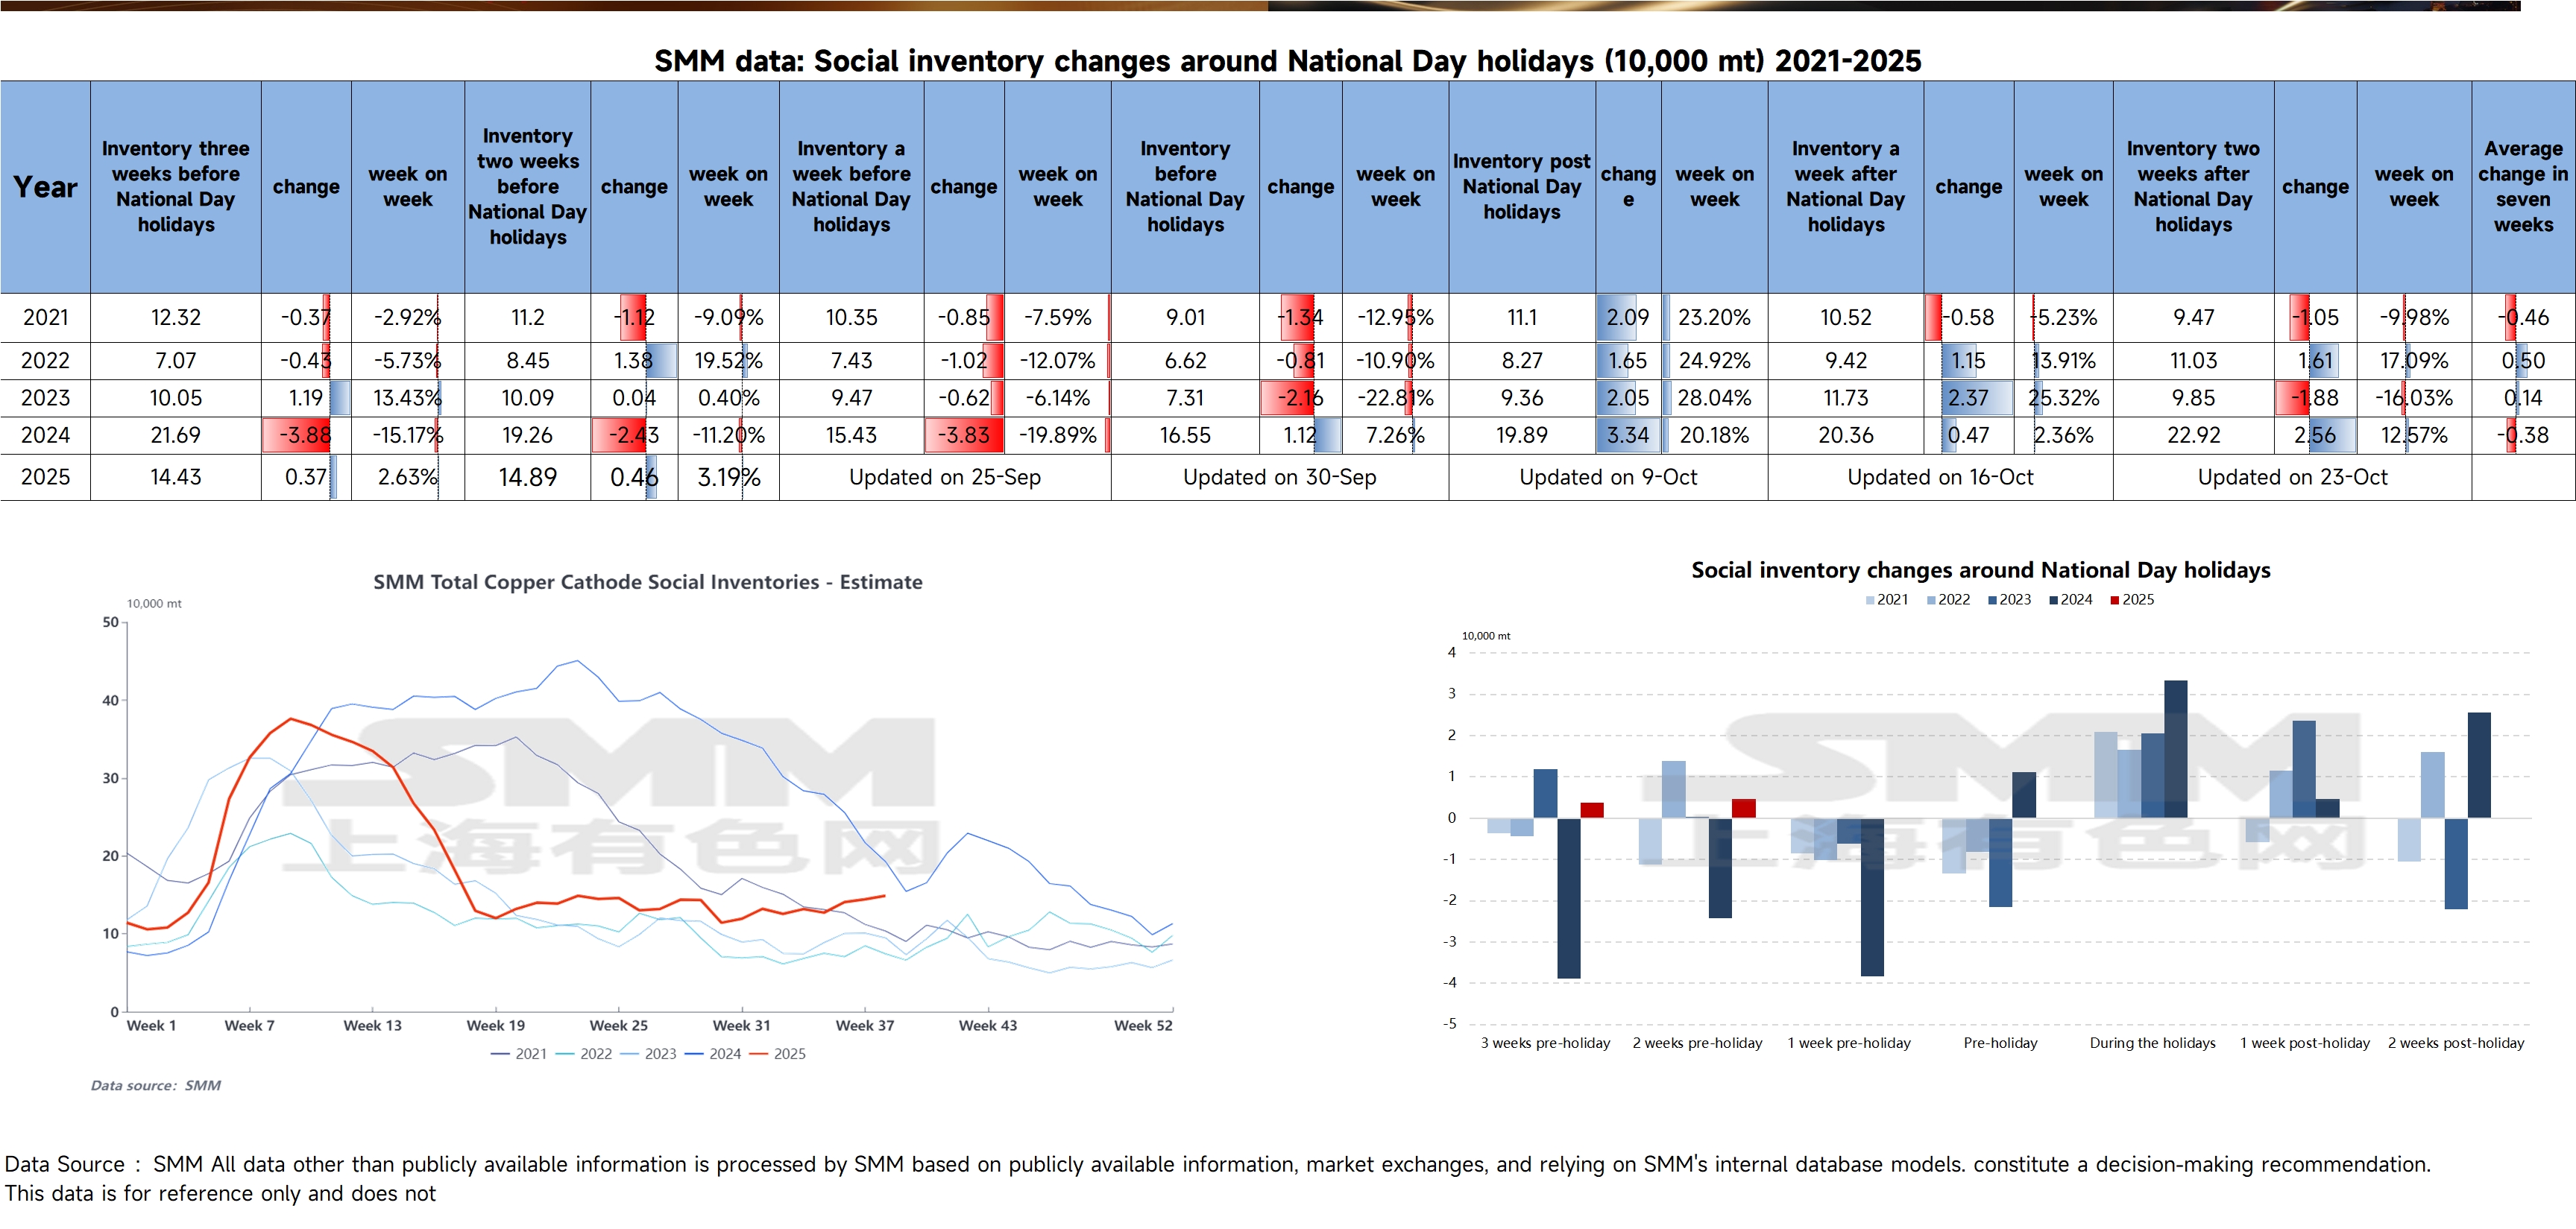
Due to high copper prices and continuous import arrivals, copper inventories were still in a buildup two to three weeks before the National Day holiday in 2025. Against the backdrop of this round of copper price decline and reduced import supplements WoW, destocking is expected to appear on September 25. Fundamental support for copper prices remains. After the brief retreat of macro tailwinds, the market is expected to resume trading expectations for an October rate cut. Key focuses include signs of stabilization in precious metals and fundamental consumption sentiment for copper. Copper prices are expected to pause their decline near 79,000 yuan/mt and gradually recover to fill the gap.


Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.

For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
Centinela Strike Could Cut November Copper Output by Half, Unions Say
2 hours ago
Centinela Strike Could Cut November Copper Output by Half, Unions Say
Read More
Centinela Strike Could Cut November Copper Output by Half, Unions Say
A workers’ strike at Antofagasta’s Centinela copper mine in Chile could reduce the operation’s November copper production by around 50% if the work stoppage continues, according to union representatives. The strike began on October 7 after two unions rejected further negotiations with Antofagasta Minerals following the failure of government-mediated talks to produce an agreement. The labour groups represent more than half of Centinela’s critical mine operators and more than 60% of equipment maintenance workers. The unions said the initial operational impact is expected to worsen gradually because mining and mine-development activities have been affected, while a large volume of waste rock still needs to be removed. They expect the full effect of the strike to become more visible in November, when production could fall by as much as half. Antofagasta has said it continues to maintain its production guidance despite the strike and declined to comment on the unions’ estimate of the potential November production impact. The dispute centres on differences in pay and benefits between union groups. Labour representatives are seeking equivalent benefits for employees regardless of union affiliation, while Antofagasta has said bargaining schedules have been separated since 2020 and wage adjustments have been negotiated at different times. The union estimate of a potential 50% decline in November production materially increases the supply significance of the Centinela strike compared with the initial work stoppage. However, the estimate has not been confirmed by Antofagasta, which continues to maintain its production guidance. The scale of any actual copper loss will therefore depend on the duration of the strike, the extent of disruption to mining and maintenance activities, and whether negotiations resume before November.
2 hours ago
Magna Mining Approves Levack Mine Restart, Targets Mid-2028 Commercial Production
2 hours ago
Magna Mining Approves Levack Mine Restart, Targets Mid-2028 Commercial Production
Read More
Magna Mining Approves Levack Mine Restart, Targets Mid-2028 Commercial Production
Magna Mining has approved the restart of its fully permitted Levack Mine in Ontario, Canada, following completion of a Preliminary Economic Assessment that outlines 7.3 years of commercial production and estimated initial capital requirements of C$70.1 million. The PEA outlines average annual payable production of approximately 36.8 million lb of copper-equivalent over the commercial production period, with output comprising nickel, copper and precious metals. Magna is targeting the start of commercial production in mid-2028. The study estimates an after-tax NPV at a 7% discount rate of C$227.0 million, an after-tax IRR of 92.4%, and a payback period of 0.6 years under the base-case assumptions used in the PEA. The development plan involves restarting the existing underground operation and utilizing established mine infrastructure. Following board approval, Magna plans to advance detailed engineering, underground development and other activities required to support the proposed restart schedule. The PEA includes approximately 2.1 million short tons of Inferred Mineral Resources. Magna cautioned that the assessment is preliminary in nature and that the restart decision was not based on a feasibility study of Mineral Reserves demonstrating economic and technical viability. The board approval moves Levack from technical evaluation toward restart execution, with commercial production targeted for mid-2028 and initial capital estimated at C$70.1 million. The strong PEA economics indicate potentially attractive project returns under the study assumptions, but the inclusion of Inferred Mineral Resources and the absence of a feasibility-level reserve case mean execution and economic uncertainty remain material. Attention will now turn to detailed engineering, underground development and capital deployment as Magna advances toward the planned restart.
2 hours ago
Ivanhoe Reports 76,401 mt Q3 Copper in Saleable Products at Kamoa-Kakula, Guidance Trends Toward Lower End
2 hours ago
Ivanhoe Reports 76,401 mt Q3 Copper in Saleable Products at Kamoa-Kakula, Guidance Trends Toward Lower End
Read More
Ivanhoe Reports 76,401 mt Q3 Copper in Saleable Products at Kamoa-Kakula, Guidance Trends Toward Lower End
Ivanhoe Mines reported that the Kamoa-Kakula Copper Complex in the Democratic Republic of Congo produced 76,401 mt of copper in saleable products in Q3 2026, up approximately 19% from 64,328 mt in Q2. The company maintained its 2026 production guidance of 290,000–310,000 mt, while stating that output is trending toward the lower end of the range. Q3 saleable copper comprised 61,506 mt of copper in anode, 2,347 mt of toll-treated copper in blister, 5,645 mt of copper in slag concentrate, and 6,904 mt of high-grade copper fines designated for sale. Ivanhoe said the high-grade fines had been produced previously and stockpiled before being assayed, surveyed and designated for sale during the quarter. The Phase 1, 2 and 3 concentrators processed a combined 3.493 million mt of ore during Q3, compared with 2.968 million mt in Q2. Combined feed grade averaged 2.22% copper, while recovery reached 87.6%, compared with 87.4% in the previous quarter. Copper contained in concentrate increased to 68,188 mt from 61,134 mt in Q2. Mining rates across Kamoa and Kansoko increased by approximately 30% to more than 700,000 mt/month, equivalent to around 8.5 million mt/year. Ivanhoe said higher mining rates are expected to continue supporting production as underground operations recover. Kamoa-Kakula’s on-site smelter remained at around 60% of its 500,000 mt/year design capacity during the quarter. The smelter also produced a record 118,638 mt of high-strength sulphuric acid in Q3. Ivanhoe continues to work on improving concentrate quality and reducing silica levels that have contributed to increased slag concentrate production. Kamoa-Kakula’s Q3 saleable copper output increased approximately 19% quarter on quarter, supported by higher mining rates, increased concentrator throughput and the designation of previously stockpiled high-grade copper fines for sale. However, Ivanhoe’s indication that 2026 production is trending toward the lower end of its 290,000–310,000 mt guidance range shows that the complex remains in a recovery and ramp-up phase.
2 hours ago
Copper prices may regain steam on supportive fundamentals and bets on further US rate cuts - Shanghai Metals Market (SMM)

