Tin and rare earth permanent magnets provide support, with expected increase in downstream demand for semiconductors and others, minor metal sector strengthens [SMM Flash News]

Published: Jun 27, 2025 15:20 (GMT+8)

SMM June 27:

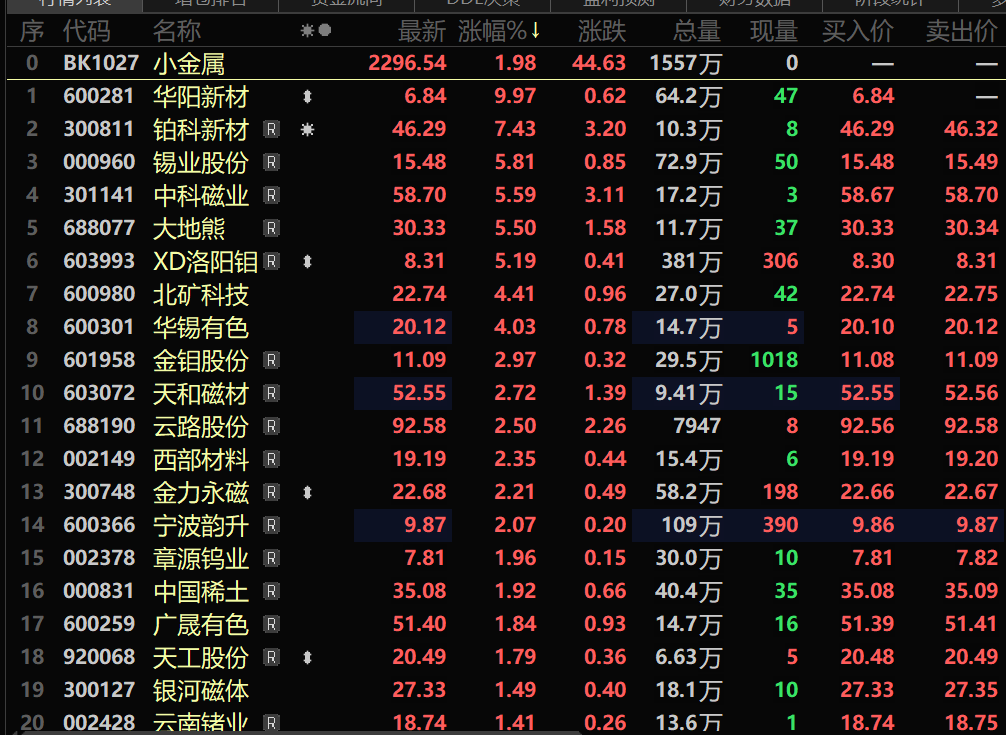
Tin prices were boosted by slower-than-expected production resumptions in Myanmar's Wa State and supply tightness caused by Thailand's restrictions on Myanmar tin ore transit. Rare earth permanent magnets gained policy-driven momentum, with industry chain participants expressing optimism about the rare earth market outlook. Tungsten prices continued hovering at high levels. Rapid development in downstream sectors like new energy, semiconductors, and defense industries strengthened growth expectations for minor metal demand. Market capital's favor towards resource-scarce varieties also contributed to the sector's strength. As of 14:34 on June 27, the minor metal sector rose 1.98%, with Huayang New Materials hitting the limit-up, while Poco New Materials, Yunnan Tin, Sinomag Technology, Earth-Panda, and CMOC led gains.
News

Huayang New Materials announced on June 25 that its related party Huayang Group received an investigation notice from the China Securities Regulatory Commission. The notice stated Huayang Group was being investigated for occupying funds from Yangmei Chemical in 2021 without properly disclosing non-operational capital transactions. The company clarified this incident is unrelated to its operations and won't affect normal production activities, confirming no fund occupation by controlling shareholders or related parties. The event has no direct operational impact. After achieving "four limit-ups in five trading days," Huayang New Materials issued a stock trading abnormal fluctuation warning on June 18, noting its shares had accumulated a 20% price deviation over three consecutive trading days (June 13, 16, and 17, 2025) per SSE regulations. Recent volatile stock movements significantly outpaced industry trends. The company reiterated it has no rare earth permanent magnet business, focusing instead on platinum-group metal recycling, where rising precious metal prices are increasing raw material procurement costs.

Spot Market

Rare earth spot:
》Click for SMM rare earth spot prices

》Subscribe for SMM metal spot historical price trends

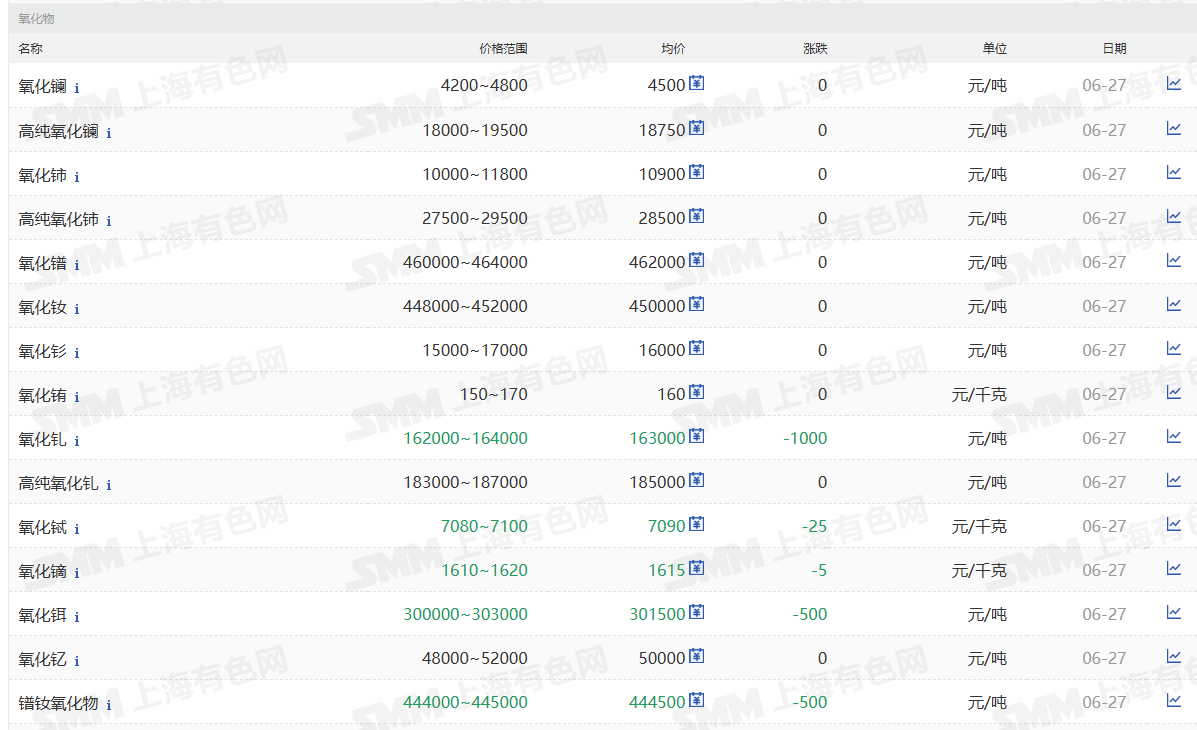
On June 27, SMM's Pr-Nd oxide (1#) quotation range stood at 444,000-445,000 yuan/mt, averaging 444,500 yuan/mt, down 0.11% from the previous trading day. Recently, due to the impact of the traditional rainy season in Southeast Asia, Myanmar's ore imports have declined significantly, and mine-end suppliers have shown weak willingness to sell. Rare earth oxides overall remain slightly in the doldrums, with sluggish inquiries from downstream buyers and some suppliers reducing prices to release small volumes. As downstream industries gradually emerge from the traditional off-season, coupled with frequent positive market news, most industry insiders hold optimistic expectations for future rare earth prices. Under this market sentiment, low-priced cargoes may become even harder to find. Overall, while the rare earth market faces short-term volatility challenges, the industry maintains a generally positive outlook on its long-term development prospects.

Tungsten spot market:
》Click to view SMM tungsten spot prices

》Subscribe to view SMM metal spot price history

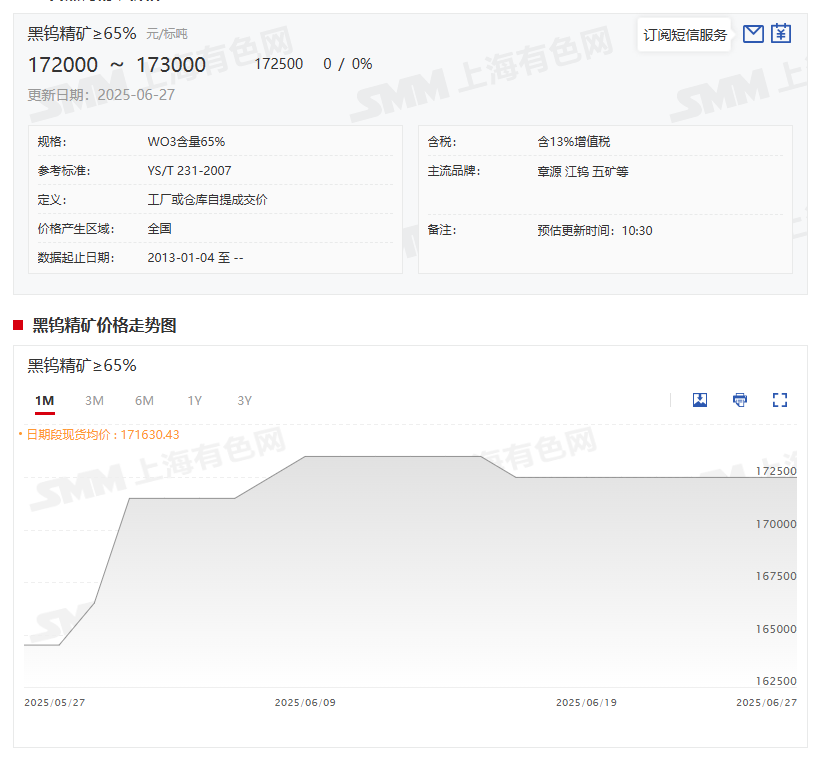
On June 27, the tungsten market primarily exhibited high-level consolidation, with mainstream mine-end suppliers maintaining low inventory levels and insufficient willingness to lower prices. Mine-end declines remained limited, and quotations stayed elevated. Downstream APT enterprises faced poor profitability, leading some smelters to implement production cuts and maintenance. The upstream primarily fulfilled long-term contract shipments, while downstream firms conducted just-in-time restocking, resulting in stable overall transactions. In the short term, macro factors include marginal easing of Middle East tensions and reduced overseas risk aversion. Fundamentals show a tight balance between domestic tungsten's upstream and downstream sectors. With upstream mine-end raw material inventories at low levels coupled with production controls, tungsten price corrections remain limited. Downstream smelters face poor profitability, creating a dual weakness in supply and demand. Structural contradictions in the industry chain are prominent, with a tug-of-war between longs and shorts as the market undergoes restructuring. Short-term maintenance of high-level consolidation is expected. Continued attention should be paid to mainstream companies' July long-term contract pricing and downstream operational rates.

Recommended readings:

》Limited room for raw material-end concessions: Tungsten market to fluctuate at highs in short term [SMM Tungsten Daily Review]

》Rare earth prices continue to stabilize - How will market expectations evolve? [SMM Analysis]

Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.

For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
【Flash | Semtech Adds Cleanroom Space as InP Photonics Demand Ramps】
52 mins ago
【Flash | Semtech Adds Cleanroom Space as InP Photonics Demand Ramps】
Read More
【Flash | Semtech Adds Cleanroom Space as InP Photonics Demand Ramps】
Semtech said in its Aug. 25 earnings presentation that its data-center photonics portfolio spans gain chips, high-power CW lasers, SOAs and high-speed photodiodes, while it has secured FY2027 equipment deliveries and acquired additional cleanroom space. Semtech acquired HieFo in March, adding US-based InP gain-chip and DFB-laser manufacturing. Q2 FY2027 data-center sales reached $100 million, up 39% QoQ and 91% YoY; Q3 sales are targeted to rise 45% QoQ and 160% YoY. SMM believes the buildout supports medium-term demand for InP and high-purity indium, although no nameplate capacity or indium consumption was disclosed.
52 mins ago
[SMM Chromium Flash] Global Chrome Ore Departures Fall 2.74% WoW to 642,500 mt, Maputo Rebounds
17 hours ago
[SMM Chromium Flash] Global Chrome Ore Departures Fall 2.74% WoW to 642,500 mt, Maputo Rebounds
Read More
[SMM Chromium Flash] Global Chrome Ore Departures Fall 2.74% WoW to 642,500 mt, Maputo Rebounds
[SMM Chromium Flash] Global Chrome Ore Departures Fall 2.74% WoW to 642,500 mt, Maputo Rebounds
Global chrome ore departures totaled 642,500 mt in the week ended October 2, down 2.74% week-on-week, according to SMM's latest data. The modest headline decline masks a significant reshuffling beneath the surface, as a sharp rebound at Maputo was offset by pullbacks at Richards Bay and Mersin. Maputo departures rose to 488,800 mt from 340,200 mt, a 43.68% increase that lifted the port's share of total departures back to roughly 76% from about 51.5% a week earlier, reversing the prior week's shift toward a more distributed export mix. Richards Bay fell to 95,700 mt from 227,800 mt, a 57.99% decline that gave back the bulk of the prior week's rebound, while Mersin eased 31.52% to 58,000 mt from 84,700 mt. Beira again recorded no chrome ore departures, remaining inactive for a fourth consecutive week. The week's data points to a reversion toward the more Maputo-concentrated flow pattern seen through most of August and September, with the prior week's broader distribution across ports proving short-lived. Whether Richards Bay's pullback reflects a one-off after an unusually strong prior week or a return to its more intermittent loading pattern will be worth monitoring in the coming weeks.
17 hours ago
[SMM Chromium Flash] China's High-Carbon Ferrochrome Output Drops 3.17% MoM in September as Cost Inversion Bites
18 hours ago
[SMM Chromium Flash] China's High-Carbon Ferrochrome Output Drops 3.17% MoM in September as Cost Inversion Bites
Read More
[SMM Chromium Flash] China's High-Carbon Ferrochrome Output Drops 3.17% MoM in September as Cost Inversion Bites
[SMM Chromium Flash] China's High-Carbon Ferrochrome Output Drops 3.17% MoM in September as Cost Inversion Bites
SMM data showed that China's high-carbon ferrochrome output in September 2026 fell 3.17% MoM, a wider decline than August's 1.25%. Output remained 18.8% higher YoY, though growth slowed from 20.36% in August. Output for January to September was up 30.84% YoY, compared with 32.56% at the end of August. The slowdown reflects squeezed margins. Firm coke prices, higher power tariffs and slow-moving chrome ore prices raised costs, while lower steel mill tender prices pressured ferrochrome prices, so southern producers, where costs are highest, cut output most. Output in the northern producing region held up better and kept national volumes well above last year, which is why YoY and YTD growth remain strong even as the MoM trend turns down. SMM expects output to ease only slightly from here, with weaker stainless steel demand offset by lower chrome ore costs and fixed long-term contract volumes.
18 hours ago


