News of Production Cuts at Stainless Steel Mills: Are Prices Expected to Bottom Out? [SMM Stainless Steel Daily Review]

Published: Jun 24, 2025 18:18 (GMT+8)
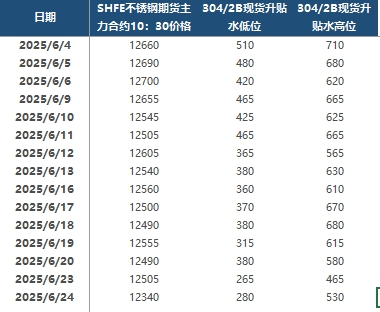
[SMM Stainless Steel Daily Review: Will Stainless Steel Prices Hit Bottom Amid News of Production Cuts by Steel Mills?] SMM reported on June 24 that the SS futures market opened lower and hit bottom, refreshing a new five-year low. However, in the afternoon, influenced by news of production cuts by leading domestic stainless steel mills, the futures market stopped falling and rebounded. In the spot market, Tsingshan once again lowered the plate prices of 300-series stainless steel in the morning, with a decrease of 200-300 yuan/mt, leading to a further decline in spot prices. The base price of 304 cold-rolled steel coil with rough edges had dropped to 12,100 yuan/mt, returning to the price level of early 2020. The continuous decline in prices further intensified the wait-and-see sentiment among downstream buyers, and transactions did not recover despite the price pullback. At noon, news spread in the market about production cuts by leading large domestic stainless steel mills, boosting market sentiment and leading to a simultaneous rebound in futures and spot prices. In the futures market, the most-traded 2508 contract bottomed out and rebounded. At 10:30 a.m., SS2508 was reported at 12,340 yuan/mt, down 165 yuan/mt from the previous trading day. In the Wuxi region, spot premiums and discounts for 304/2B stainless steel were in the range of 280-530 yuan/mt. In the spot market, cold-rolled 201/2B coils in both Wuxi and Foshan were reported at 7,575 yuan/mt; cold-rolled rough-edged 304/2B coils had an average price of 12,575 yuan/mt in Wuxi and the same in Foshan; cold-rolled 316L/2B coils were priced at 23,700 yuan/mt in Wuxi and the same in Foshan; hot-rolled 316L/NO.1 coils were reported at 23,000 yuan/mt in both regions; cold-rolled 430/2B coils were priced at 7,350 yuan/mt in both Wuxi and Foshan...

SMM News on June 24, SS futures market opened lower and hit bottom, refreshing a new five-year low again. However, influenced by news of production cuts at major domestic stainless steel mills in the afternoon, the market bottomed out and rebounded. In the spot market, Tsingshan once again lowered the plate prices for 300-series stainless steel in the morning, with a decrease of 200-300 yuan/mt, leading to a further decline in spot prices in the market. The base price of 304 cold-rolled trimmed steel coils had dropped to 12,100 yuan/mt, returning to the price level seen in early 2020. The continuous decline in prices further intensified the wait-and-see sentiment among downstream buyers, and transactions did not recover despite the price pullback. At noon, news spread about production cuts at major domestic stainless steel mills, boosting market sentiment and leading to a simultaneous rebound in futures and spot prices.

In the futures market, the most-traded 2508 contract bottomed out and rebounded. At 10:30 a.m., SS2508 was reported at 12,340 yuan/mt, down 165 yuan/mt from the previous trading day. Spot premiums and discounts for 304/2B in the Wuxi area ranged from 280-530 yuan/mt. In the spot market, cold-rolled 201/2B coils in both Wuxi and Foshan were reported at 7,575 yuan/mt; cold-rolled trimmed 304/2B coils had an average price of 12,575 yuan/mt in Wuxi and the same in Foshan; cold-rolled 316L/2B coils were priced at 23,700 yuan/mt in Wuxi and the same in Foshan; hot-rolled 316L/NO.1 coils were reported at 23,000 yuan/mt in both regions; cold-rolled 430/2B coils were priced at 7,350 yuan/mt in both Wuxi and Foshan

. Currently, the stainless steel market is in the traditional off-season for consumption, with persistent weakness in downstream demand. Despite widespread losses faced by enterprises, some steel mills have already begun to implement production cuts. However, due to the large production base in the early stage, current market supply remains at a historically high level for the same period, and the contradiction of oversupply is particularly prominent. The pressure on stainless steel mills, agents, and traders to sell has risen sharply. Both in-plant inventory and social inventory remain high, and market pessimism is widespread. Traders are scrambling to sell, leading to a continuous decline in stainless steel quotes. The raw material side is also under tremendous pressure. Influenced by expectations for production cuts at steel mills, prices of raw materials such as high-grade NPI and stainless steel scrap have also weakened simultaneously, further eroding the cost support for stainless steel. The market is waiting to see how the supply-demand relationship will recover after production cuts at stainless steel mills.
Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.

For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
【Flash | Victorio Molybdenum Resource Expands Ahead of New Economic Assessment】
11 hours ago
【Flash | Victorio Molybdenum Resource Expands Ahead of New Economic Assessment】
Read More
【Flash | Victorio Molybdenum Resource Expands Ahead of New Economic Assessment】
Spartan Metals Corp. released an updated mineral resource estimate for the Victorio tungsten-molybdenum project in New Mexico. Measured and indicated resources total 84.54 million short tons grading 0.09% molybdenum, containing 147.85 million lb (about 67,064 tonnes) of molybdenum. Inferred resources total 101.84 million short tons grading 0.06%, containing 130.02 million lb (about 58,976 tonnes). At a US$50-per-short-ton gross metal value cutoff, the two categories increased 9.5% and 31.9%, respectively, from the historical 2012 estimate. The update will support a preliminary economic assessment expected in the fourth quarter of 2026. These are in-situ resources, not reserves or recoverable production; the project has no current supply impact.
11 hours ago
【Flash | Strike Begins at Highland Valley Copper as Operations Fall to Reduced Capacity】
11 hours ago
【Flash | Strike Begins at Highland Valley Copper as Operations Fall to Reduced Capacity】
Read More
【Flash | Strike Begins at Highland Valley Copper as Operations Fall to Reduced Capacity】
Teck Resources confirmed that United Steelworkers Local 7619 has begun strike action at the Highland Valley Copper operation in Canada, with the mine continuing to operate at reduced capacity. The operation’s existing 2026 molybdenum production guidance is 1,500–1,800 tonnes, against approximately 700 tonnes produced in the first half. Teck said the impact on overall production will depend on the duration of the labour action. The company has not disclosed the scale of the operating reduction, quantified any molybdenum production loss or revised its annual guidance. Attention has therefore shifted from whether the strike would begin to how long reduced operations may continue.
11 hours ago
China's molybdenum imports surge while exports nearly halve?! [SMM Analysis]
13 hours ago
China's molybdenum imports surge while exports nearly halve?! [SMM Analysis]
Read More
China's molybdenum imports surge while exports nearly halve?! [SMM Analysis]
In the first three quarters of 2026, China's molybdenum product imports surged 41.4% YoY in physical content, but metal content grew only 9.9%, with about 84% of the physical growth coming from low-grade ore and tailings. Meanwhile, molybdenum oxide exports nearly halved, and ferromolybdenum exports fell 20%, as high domestic costs are eroding the ex-China competitiveness of smelted products. Entering Q4, molybdenum oxide prices in China and ex-China are expected to remain weak, and falling steel tender prices and ferromolybdenum losses may continue to pressure raw material affordability; if the import window remains closed, ex-China molybdenum raw material inflows could also retreat from the highs seen in the first three quarters......
13 hours ago