

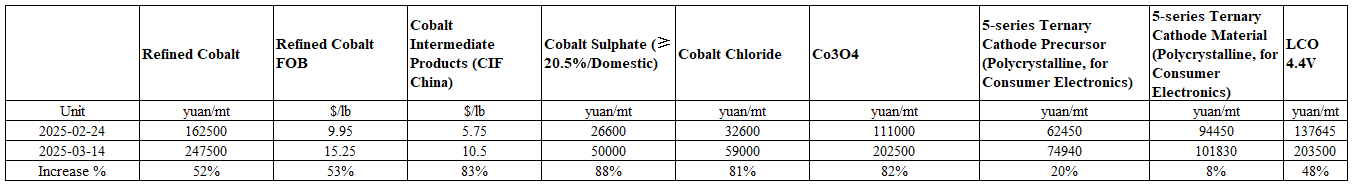
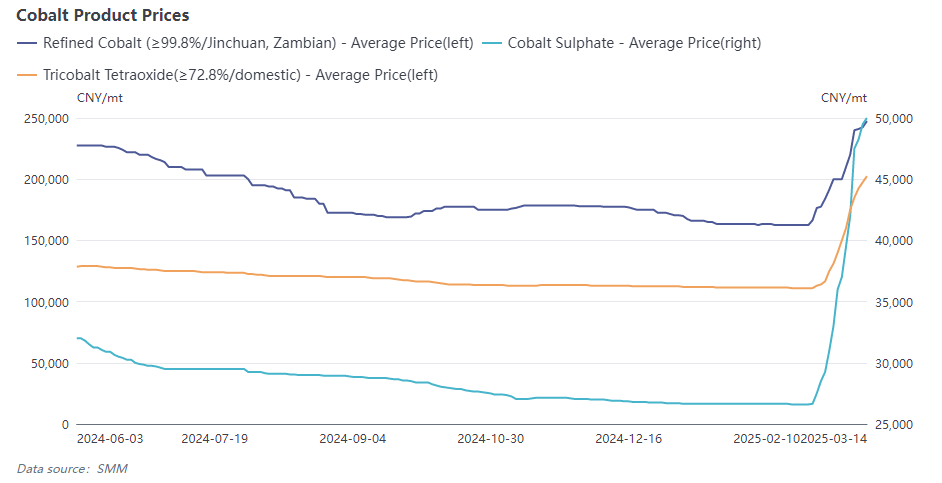
On February 24, 2025, the Democratic Republic of Congo (DRC), the world's largest cobalt supplier, announced a four-month suspension of cobalt exports to address the persistent decline in cobalt prices due to oversupply in the international market. The policy took effect on February 22 and is scheduled for a three-month review to assess its impact and decide on potential adjustments. Since its announcement, this policy has garnered worldwide attention and ignited enthusiasm in the cobalt product market. According to SMM prices, as of March 14, the prices of all cobalt products have seen significant increases. Specifically, the cumulative price increase for cobalt sulfate, cobalt chloride, and cobalt intermediates has exceeded 80%.

Why Did This Ban Attract So Much Attention?
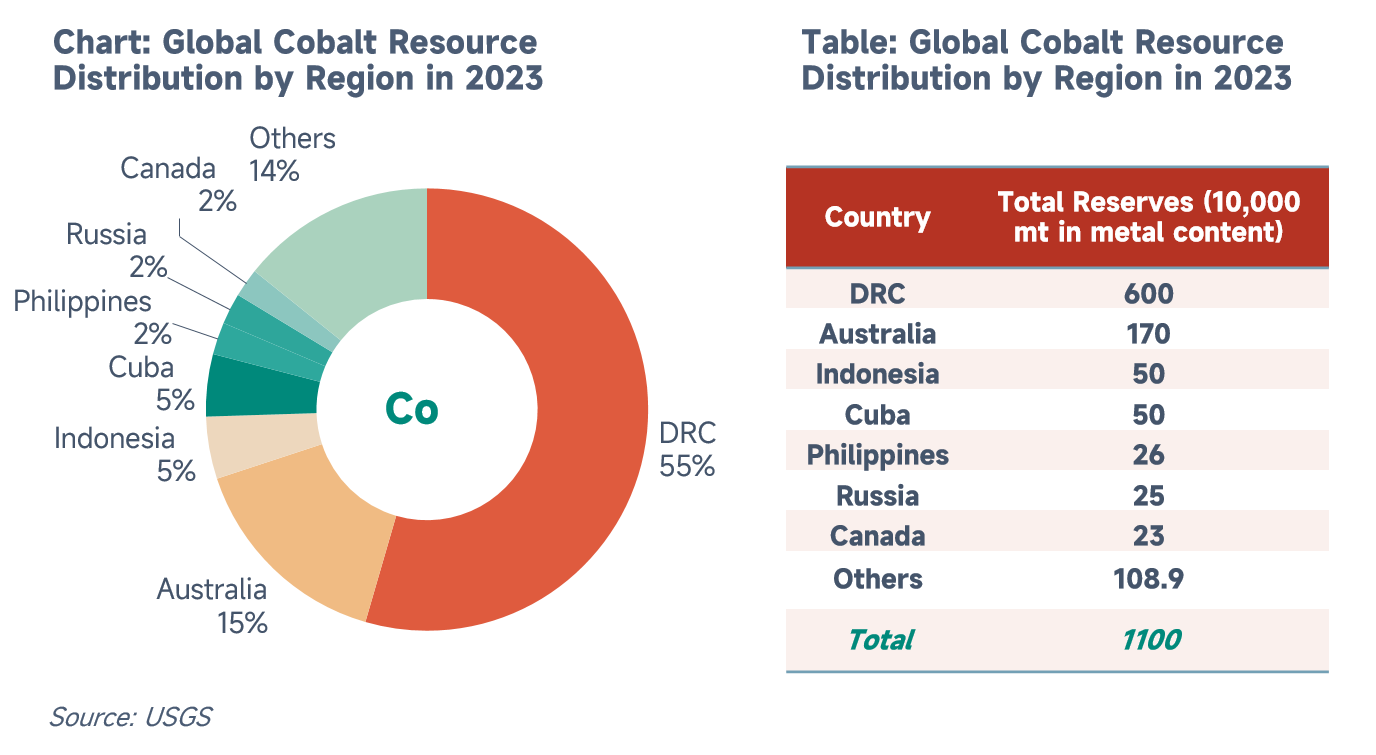
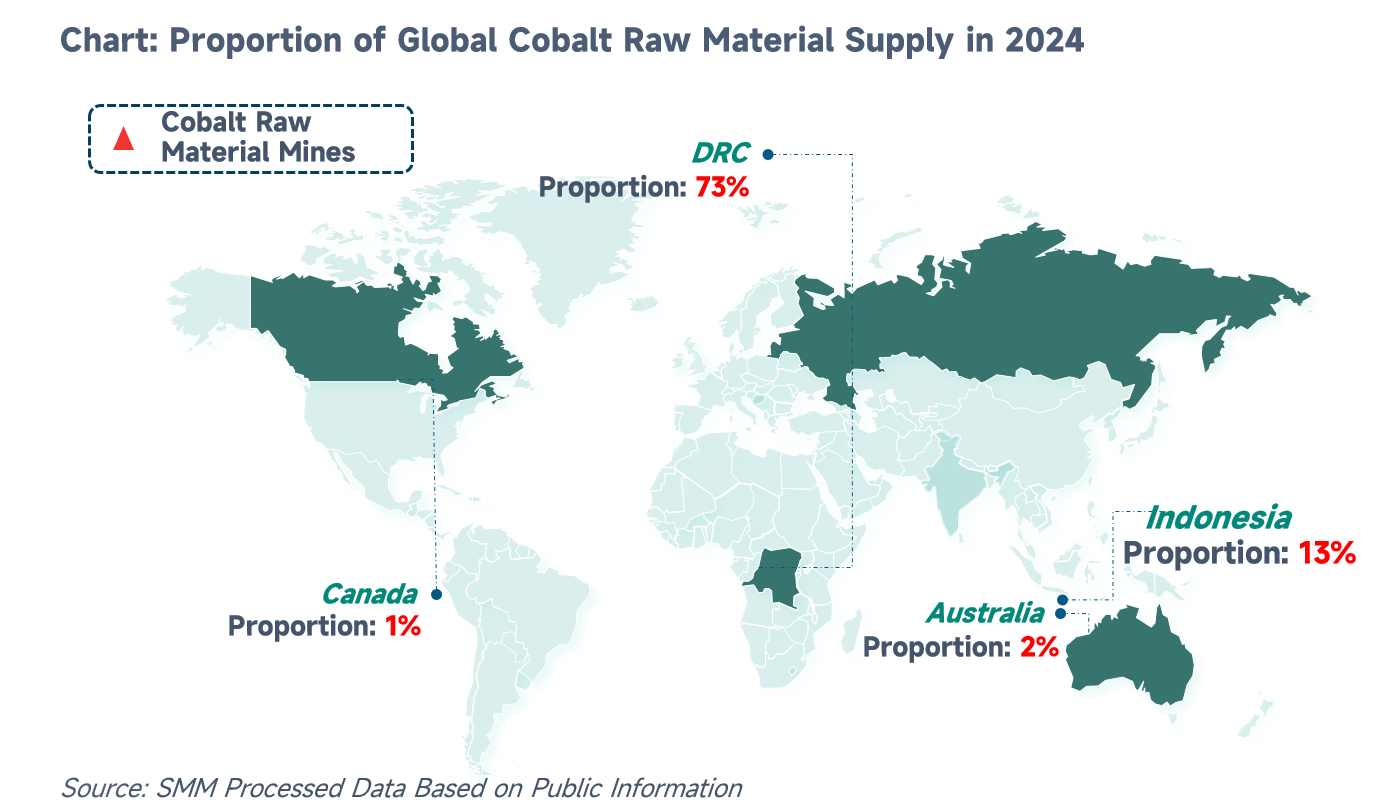
Firstly, in terms of cobalt resource reserves, data from the United States Geological Survey (USGS) shows that the DRC holds an absolute dominant position in cobalt reserves, followed by Australia and Indonesia. From the perspective of overall resource output, the DRC accounted for 73% of the global cobalt resource production in 2024, firmly ranking first in the world. Indonesia, benefiting from the cobalt content in its nickel mines, became the second-largest cobalt supplier globally, with a resource output share of 13%. However, this is still significantly lower compared to the DRC's output share. Therefore, the announcement of this ban has naturally attracted widespread global attention.
Has the Supply-Demand Balance Changed After the Ban?
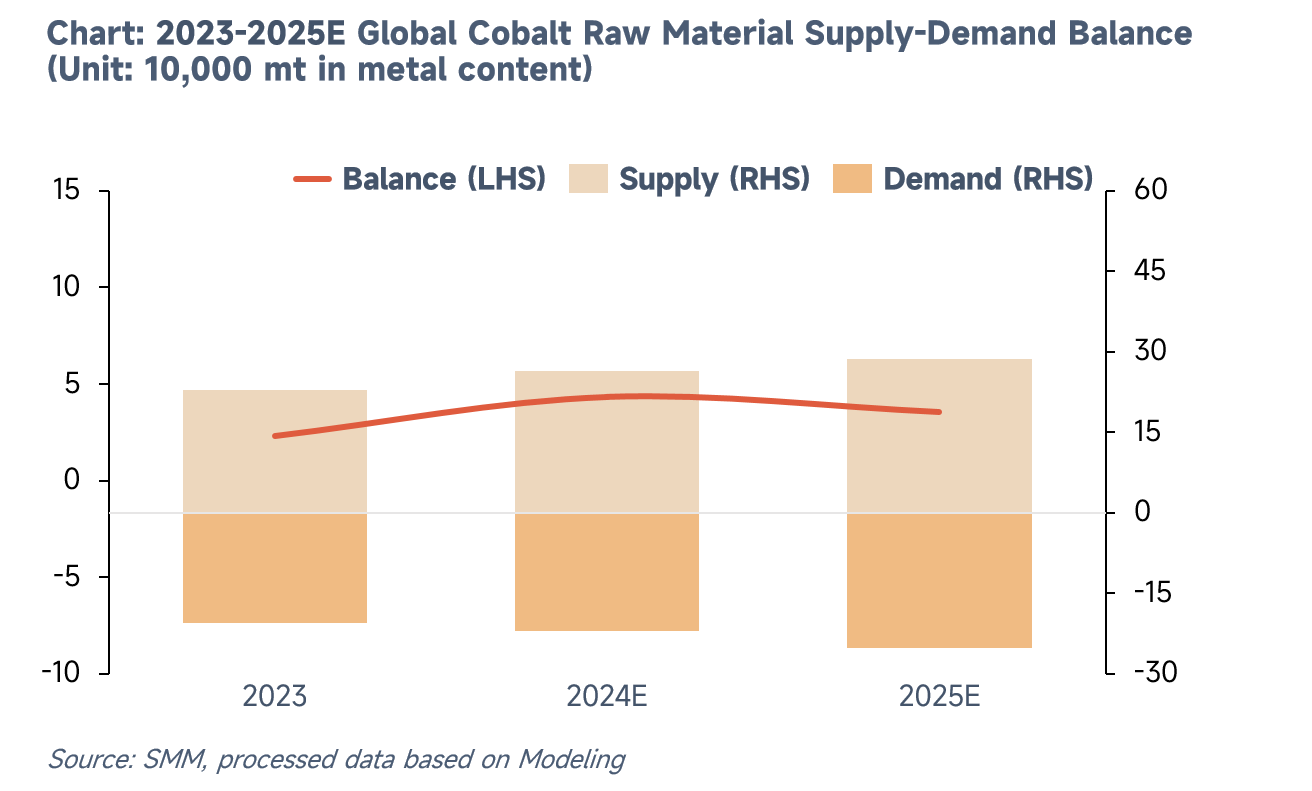
According to SMM's previous estimates, the total global cobalt resource supply in 2025 is expected to be around 290,000 cobalt metal tons, while the global demand is projected at 250,000 cobalt metal tons, indicating that the global market will still remain in a surplus situation. The DRC's output is estimated at around 180,000 cobalt metal tons. Since the DRC's cobalt production is mostly associated with copper, driven by the high copper prices in recent years, the output is currently expected to remain unchanged, with excess production accumulating as local inventory. Therefore, there is no significant adjustment expected in the annual global supply-demand balance. However, the export ban has disrupted the supply chain, potentially causing structural changes in the supply-demand dynamics of different regional markets.
Impact on the Spot Market
The ban will alter the supply-demand expectations in the spot market. As mentioned earlier, based on an annual output of 180,000 cobalt metal tons, the four-month export ban is expected to affect approximately 60,000 cobalt metal tons of cobalt resource circulation. Focusing solely on the four-month ban, it is anticipated that there will be a short-term tightening of cobalt raw material availability, which will boost prices in the short term and drive the digestion of inventories across various channels in the spot market. However, the medium to long-term outlook will still depend on the implementation of subsequent policies. Additionally, the following key factors need to be considered:
- Divergent Inventory Accumulation Across Segments: According to SMM data, the refined cobalt, which has shown the best profit performance from 2023 to 2025, has accumulated a significant amount of inventory over the past two years. In contrast, cobalt sulfate and cobalt oxide, which have shown weaker profit performance, have mostly maintained a small inventory drawdown or a tight balance. The differences in the supply-demand structure of various cobalt products may lead to varying degrees of price support.

- Low Long-term Agreement Ratios: Due to the continuous decline in cobalt prices in the past, the long-term agreement signing ratios for cobalt products (such as the long-term agreement ratio of cobalt salts to cobalt resources, and the long-term agreement ratio of cobalt salts for ternary precursor manufacturers) are generally low. Under significant price fluctuations, a large proportion of spot purchases will further amplify price volatility.
- Structural Mismatch in Cobalt Raw Material Supply and Demand: Leading integrated companies, with ample raw material reserves through multiple channels such as MHP (Mixed Hydroxide Precipitate) and recycling, are less affected. However, some second-tier and non-integrated manufacturers still rely heavily on external raw material purchases. In this situation, they will passively accept high-priced raw materials, which will support cobalt product prices from a cost perspective.
- Significant Cobalt Supply from Indonesian MHP: In terms of MHP production, according to SMM processing data, Indonesia's MHP output was approximately 315,000 nickel tons in 2024, with a cobalt content of around 35,000 cobalt metal tons. Considering the commissioning of new projects and capacity expansion, Indonesia's MHP output is expected to reach about 447,000 nickel tons in 2025, with a cobalt content of around 50,000 tons, which will provide a certain supplement to the resource supply.
Market Performance of Cobalt Products This Week:
- Cobalt Intermediates: Prices continued to rise this week. Manufacturers generally adopted a strategy of stockpiling and withholding sales, resulting in a scarcity of available supply in the market. Downstream salt manufacturers, with low long-term agreement coverage, have a rigid need to replenish their inventories. Active inquiries and purchases, along with sporadic high-priced spot transactions, have driven up spot prices.
- Cobalt Salts: Cobalt salt prices saw a significant increase this week. Following the announcement of the DRC's suspension of cobalt exports, market sentiment continued to heat up, exacerbating the withholding sentiment among cobalt salt manufacturers. Spot prices kept climbing, with an increase of nearly 80%. Many companies adopted a strategy of making a few high-priced transactions, further fueling the rise in cobalt salt spot prices.
- Refined Cobalt: The price of refined cobalt continued to rise this week. On the supply side, the supply of refined cobalt remained relatively ample, with smelters generally adopting a strategy of withholding goods to support prices. On the demand side, downstream inquiries were active, with some follow-up transactions. Foreign trade merchants were also eager to purchase. In the market, the withholding sentiment among smelters remained strong, combined with some traders' selling to fulfill warehouse deliveries, creating a speculative atmosphere and driving spot prices higher.
- Cobalt Oxide (Co3O4): This week, the price of cobalt oxide increased significantly, with a continuous strengthening of market pricing intentions. Due to the general suspension of quotations by smelters and the increasing phenomenon of stockpiling and withholding sales, the market presented a situation of having prices but no goods available. As a result, cobaltate lithium manufacturers increased their inquiries, and there were many high-priced spot transactions, driving the spot price of cobalt oxide higher. At the same time, cobalt salt manufacturers also strengthened their withholding sentiment, further increasing the production cost of cobalt oxide. Under the dual pressures of tight supply and rising costs, the spot price of cobalt oxide has significant potential for further increases.



