Copper Cathode Production at Full Capacity Accelerates Copper Concentrate Inventory Depletion [SMM Analysis]

Published: Mar 09, 2025 19:06 (GMT+8)
[SMM Analysis: Copper Cathode Production in Full Swing Accelerates Copper Concentrate Inventory Depletion] With the increase in China's copper cathode capacity and the rise in production targets at various smelters, the inventory of copper concentrates, the primary raw material for copper cathode, has seen accelerated depletion. Although copper concentrate port inventory cannot fully represent the supply-demand balance of copper concentrates in China, SMM's data shows that the copper concentrate inventory at nine major ports in China dropped from a peak of 1.31 million mt (ore) at the end of last year to 610,000 mt (ore) by early March 2025. This represents a reduction of more than half within less than one quarter, a remarkable pace. Corroborating this is the record-high monthly production of copper cathode in China, as reported by SMM. Meanwhile, the smelting volume of secondary copper, another raw material for copper cathode, has not seen a corresponding increase. According to SMM, the monthly smelting volume of secondary copper is estimated to be around 160,000-170,000 mt (metal content). Furthermore, the implementation of domestic reverse invoicing policies and concerns over the impact of the China-US trade war on imported secondary copper supply have both exerted pressure on the supply side of secondary copper domestically and overseas.

》View SMM Copper Prices, Data, and Market Analysis

》Subscribe to Access SMM Historical Spot Metal Prices

       At the end of last year, driven by the need for winter stockpiling and market share competition, Chinese smelters significantly accumulated copper concentrate raw material inventories. Specifically, by the end of December 2024, SMM copper concentrate inventories at nine ports reached 1.31 million mt, primarily concentrated at Jinzhou Port (mainly serving smelters in north-east China and Inner Mongolia), Yantai Port (mainly serving smelters in Shandong), Fangchenggang (mainly serving smelters in south-west China), and Nanjing Port (mainly serving smelters along the Yangtze River basin).
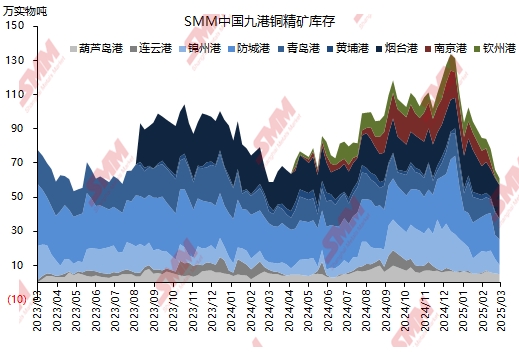
       With the increase in China's copper cathode capacity and the rising production targets of smelters, copper concentrate inventories, the primary raw material for copper cathode, have been rapidly depleted. Although port inventories of copper concentrates cannot fully represent the supply-demand balance of copper concentrates in China, SMM's nine-port copper concentrate inventories dropped from the peak of 1.31 million mt at the end of last year to 610,000 mt by early March 2025. This represents a reduction of more than half within less than a quarter, a remarkably fast pace. Supporting this trend is the record-high monthly production of copper cathode in China, as reported by SMM. Meanwhile, the smelting volume of secondary copper, another raw material for copper cathode, has not seen a corresponding increase. According to SMM estimates, the monthly smelting volume of secondary copper is around 160,000-170,000 mt in metal content. Additionally, the implementation of domestic reverse invoicing policies and concerns over the impact of the China-US trade war on imported secondary copper supply have exerted pressure on both domestic and overseas secondary copper supply chains.
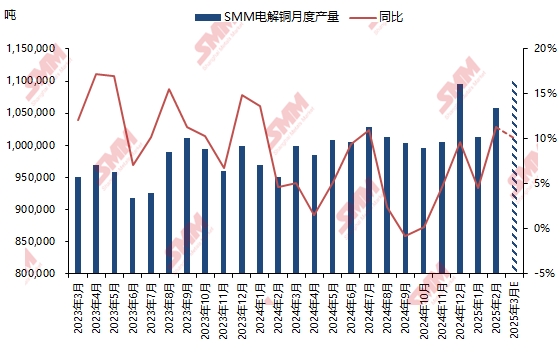
       SMM expects that as China's monthly copper cathode production continues to rise, the total contribution of secondary copper smelting to copper cathode production may continue to decline, with its contribution ratio decreasing. In contrast, the contribution level of copper concentrate raw materials to copper cathode production is expected to increase, implying a continued reduction in copper concentrate port inventories.


》Click to Access the SMM Copper Industry Chain Database
 

Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.

For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
Copper prices saw a slight correction; spot premiums edged up after the backwardation between delivery months narrowed [SMM Shanghai spot copper]
41 mins ago
Copper prices saw a slight correction; spot premiums edged up after the backwardation between delivery months narrowed [SMM Shanghai spot copper]
Read More
Copper prices saw a slight correction; spot premiums edged up after the backwardation between delivery months narrowed [SMM Shanghai spot copper]
[SMM Shanghai Spot Copper] Looking ahead to tomorrow, the current pattern of weak supply and demand in the Shanghai spot market persists. On the supply side, available cargoes in the market remain tight, with some suppliers holding limited inventories and showing little willingness to sell at low prices, providing some support for spot premiums. On the demand side, although SHFE copper prices pulled back notably during the day, procurement enthusiasm among downstream processing enterprises has yet to show significant improvement, with a strong wait-and-see sentiment prevailing in the market. Some buyers are concentrating their bids around premiums of 1,100 yuan/mt, creating a certain divergence from supplier quotes, and actual transactions remain primarily driven by rigid demand. Meanwhile, the intraday backwardation spread between futures contracts fluctuated significantly, widening to above 1,000 yuan/mt at one point. The elevated spread combined with high spot premiums continued to push up procurement costs for downstream buyers, further suppressing market transactions. Overall, tight circulating supply still underpins spot premiums, but weak demand and the high backwardation structure are limiting further upside in premiums. Shanghai spot copper premiums are expected to stay high tomorrow.
41 mins ago
Early trading activity was mediocre, and spot premiums for imported copper held steady [SMM Yangshan spot copper]
49 mins ago
Early trading activity was mediocre, and spot premiums for imported copper held steady [SMM Yangshan spot copper]
Read More
Early trading activity was mediocre, and spot premiums for imported copper held steady [SMM Yangshan spot copper]
49 mins ago
High premiums suppress demand; spot trades in North China sluggish [SMM North China spot copper]
2 hours ago
High premiums suppress demand; spot trades in North China sluggish [SMM North China spot copper]
Read More
High premiums suppress demand; spot trades in North China sluggish [SMM North China spot copper]
In North China today, spot #1 copper cathode was quoted at premiums of 850–960 yuan/mt against the front-month contract, with an average premium of 905 yuan/mt, up 30 yuan/mt from the previous trading day. The average transaction price was 109,505 yuan/mt, down 135 yuan/mt from the previous trading day.
2 hours ago