Stainless Steel Inventory During Chinese New Year Shows No Significant Increase Compared to Previous Years; Post-Holiday Prices May Face Relatively Small Pressure [SMM Analysis]

Published: Feb 06, 2025 16:40 (GMT+8)
[SMM Analysis: Stainless Steel Inventory Increase During Chinese New Year Not Significant Compared to Previous Years; Post-Holiday Prices May Face Relatively Small Pressure] In late January, the stainless steel market gradually entered a holiday state, and port arrivals in the Wuxi region decreased. Although large public warehouses continued to receive shipments, pre-holiday downstream purchasing was largely completed, leading to weak market demand and challenges in digesting inventory.

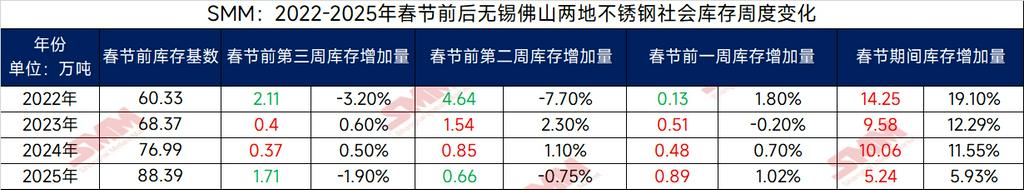
In late January, the stainless steel market gradually entered a holiday mode, with reduced port arrivals in the Wuxi region. Although large public warehouses still received shipments, market demand remained weak as downstream procurement was mostly completed before the holiday, posing challenges for inventory digestion. As of February 6, the total social inventory of stainless steel reached 883,900 mt, with an increase of approximately 52,400 mt during the Chinese New Year holiday, up by about 5.93% compared to pre-holiday levels, and a monthly increase of 37,600 mt. By series: the 200-series inventory increased by approximately 11,900 mt (up 4.48%); the 300-series inventory accumulated an increase of 37,300 mt (up 7.63%); and the 400-series inventory increased by 3,200 mt (up 2.47%). The 200-series saw the smallest inventory growth due to production cuts or shutdowns at several stainless steel mills, coupled with some downstream stockpiling completed before the holiday. Although the 300-series had the highest arrivals, its inventory growth during the Chinese New Year period was not significant compared to previous years. Post-holiday, market inquiries have been relatively inactive, and the pressure from holiday inventory increases on spot prices has yet to materialize. Most traders have not resumed operations, and close attention is still needed on how downstream consumption will digest the inventory.

In early February, social inventory is expected to continue to accumulate slightly. According to the SMM survey, despite the firm performance of spot prices, end-use consumption is expected to remain pessimistic. From late February to March, as inventory pressure rises, spot prices may face some downward pressure. However, since this year's inventory growth during the Chinese New Year period is relatively weaker than in previous years, the downward pressure may be relatively small.
》Click to View Historical SMM Stainless Steel Spot Prices


 

Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.

For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
【Flash | Tubacex October Mo-Bearing Tube Surcharges Are Mixed】
19 hours ago
【Flash | Tubacex October Mo-Bearing Tube Surcharges Are Mixed】
Read More
【Flash | Tubacex October Mo-Bearing Tube Surcharges Are Mixed】
Tubacex issued its October tube alloy surcharges. In euros, hot-/cold-finished 316/316L fell from €5.07/€5.59 per kg (€5,070/€5,590 per tonne) to €5.05/€5.56 per kg (€5,050/€5,560 per tonne). High Mo content materials, with Mo above 2.5%, declined from €5.26/€5.79 to €5.23/€5.76 per kg. Surcharges for 2205 and 2507 were unchanged, while 254 SMO rose from €9.64/€10.62 to €9.67/€10.65 per kg. SMM analysis: most Mo-bearing tube grades were flat or slightly lower, while 254 SMO moved higher, indicating differentiated cost transmission across grades.
19 hours ago
【Flash | Metallus Raises October Molybdenum Surcharge Component for 300M Steel】
19 hours ago
【Flash | Metallus Raises October Molybdenum Surcharge Component for 300M Steel】
Read More
【Flash | Metallus Raises October Molybdenum Surcharge Component for 300M Steel】
Metallus set its October raw-material surcharges for Oct 1–30. The Mo component for 300M steel rose 0.52% to $15.176/cwt, about $334.57/t of steel, from $15.098/cwt, or $332.85/t. The listed total surcharge increased 1.03% to $45.054/cwt. Scrap rose to $17.750/cwt, while the separate energy surcharge for bars and tubes fell from $1.296/cwt, about $28.57/t, to $0.050/cwt, or $1.10/t.
19 hours ago
【Flash | Alleima Raises October Surcharges for Mo-Bearing Tube Grades】
20 hours ago
【Flash | Alleima Raises October Surcharges for Mo-Bearing Tube Grades】
Read More
【Flash | Alleima Raises October Surcharges for Mo-Bearing Tube Grades】
Alleima raised tube alloy surcharges in Europe, Asia, Africa and Oceania from Oct 1. For hot-finished products, 316/316L rose from €5.26/kg (€5,260/t) to €5.33/kg (€5,330/t); High Mo from €5.74/kg (€5,740/t) to €5.81/kg (€5,810/t); SAF 2205 and SAF 2507 increased 2.26% and 1.95%; and 254 SMO rose 0.70%. The hot-finished energy surcharge more than doubled to €0.21/kg (€210/t). SMM analysis: Mo-bearing surcharges broadly rose, but the energy reset means the full increase cannot be attributed to molybdenum.
20 hours ago

