[SMM Rebar Daily Review] Market Gradually Enters Holiday Mode, Prices Expected to Stabilize Next Week

Published: Jan 17, 2025 17:08
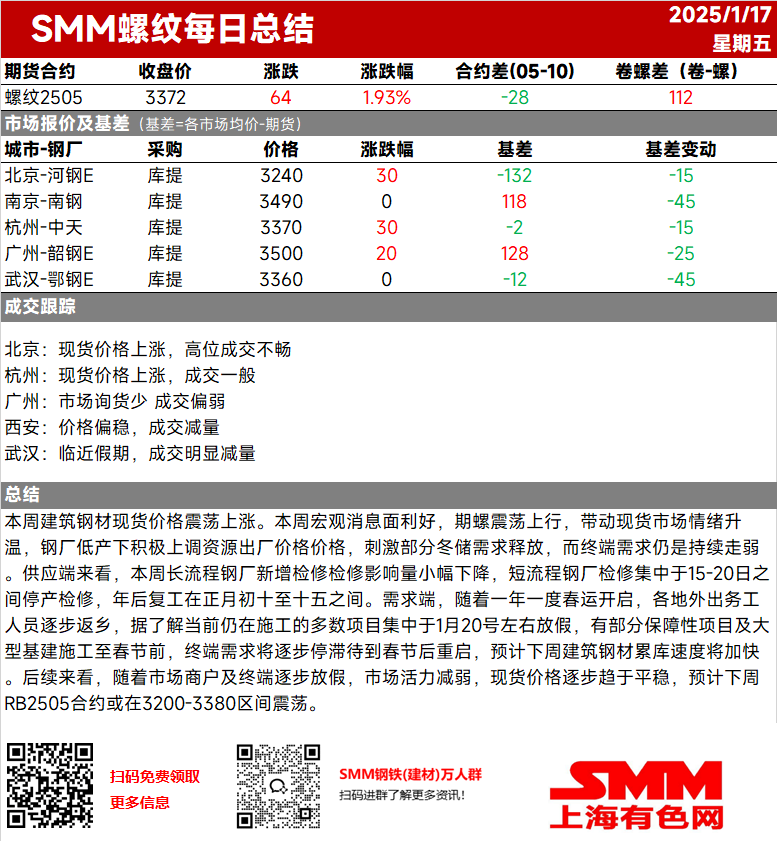
[SMM Rebar Daily Review: Market Gradually Enters Holiday Mode, Prices Expected to Stabilize Next Week] This week, construction steel spot prices fluctuated upward. Positive macro news supported the market, with rebar futures fluctuating upward, boosting market sentiment. Steel mills, operating at low production levels, actively raised ex-factory prices, stimulating partial winter stockpiling demand, while end-use demand continued to weaken...
This week, spot prices of construction steel fluctuated upward. Favorable macro news this week and the upward fluctuation of rebar futures boosted market sentiment. Steel mills, operating at low production levels, actively raised ex-factory prices of resources, stimulating partial winter stockpiling demand, while end-use demand continued to weaken. Supply side, the impact from maintenance at blast furnace steel mills slightly decreased this week, while EAF steel mills concentrated their maintenance shutdowns between the 15th and 20th, with post-holiday resumption expected between the 10th and 15th day of the Chinese New Year. Demand side, with the annual Spring Festival travel rush underway, migrant workers across regions gradually returned to their hometowns. It is understood that most ongoing construction projects are expected to halt around January 20, with some guaranteed housing projects and large-scale infrastructure construction continuing until just before the Chinese New Year. End-use demand will gradually stagnate and resume after the holiday. It is anticipated that the inventory buildup of construction steel will accelerate next week. Looking ahead, as market participants and end-users gradually take their holidays, market activity will weaken, and spot prices will stabilize. It is expected that the RB2505 contract will fluctuate within the range of 3,200-3,380 next week.
Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.

For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
[SMM Coal Flash] Bayan Resources Declares Force Majeure on Coal Supply as 2026 RKAB Approval Remains Pending
45 mins ago
[SMM Coal Flash] Bayan Resources Declares Force Majeure on Coal Supply as 2026 RKAB Approval Remains Pending
Read More
[SMM Coal Flash] Bayan Resources Declares Force Majeure on Coal Supply as 2026 RKAB Approval Remains Pending
[SMM Coal Flash] Bayan Resources Declares Force Majeure on Coal Supply as 2026 RKAB Approval Remains Pending
PT Bayan Resources Tbk and three subsidiaries, PT Tiwa Abadi, PT Tanur Jaya and PT Fajar Sakti Prima, have declared force majeure on coal supply commitments to customers. The move came after the Indonesian government had yet to approve the subsidiaries' revised 2026 RKAB. The three affected subsidiaries are part of Bayan's operations in the Tabang and North Pakar areas. Bayan's Tabang Project produced 62.5 million tonnes of coal in 2025, accounting for 91.9% of the company's total coal production of 68.0 million tonnes. Bayan said the force majeure notification was made to minimise potential risks and consequences to the company and its subsidiaries arising from the pending RKAB approval. Indonesia's Ministry of Energy and Mineral Resources (ESDM) is currently evaluating the RKAB applications and is expected to complete the process this week.
45 mins ago
[India steel, cement emissions up 8% as power-sector CO2 flatlines for two years]
11 hours ago
[India steel, cement emissions up 8% as power-sector CO2 flatlines for two years]
Read More
[India steel, cement emissions up 8% as power-sector CO2 flatlines for two years]
[India steel, cement emissions up 8% as power-sector CO2 flatlines for two years]
India's steel and cement emissions rose 8% y-o-y in H1 2026, together taking a 23% share of national CO2, even as power-sector emissions flatlined for a second year. Crude steel output grew 8% and cement 9%, aided by real-estate investment; steel consumption outpaced output, drawing down inventories, while margins stayed squeezed by costly imported coking coal and Hormuz-related freight. Clean energy covered all of the 7% (63TWh) rise in power demand over two years; coal-fired output was flat for the first time in over 50 years. To secure feedstock, India notified coking coal as a critical and strategic mineral in January, and miners and steelmakers plan new washeries for domestic blending. Jindal Steel already uses gasification syngas in steelmaking; India also targets 100 million tonnes of coal gasification capacity within four years.
11 hours ago
[SMM Analysis]Expectations Game under Cost Squeeze –  September Outlook for Coking Coal, Coke, and Iron Ore
14 hours ago
[SMM Analysis]Expectations Game under Cost Squeeze – September Outlook for Coking Coal, Coke, and Iron Ore
Read More
[SMM Analysis]Expectations Game under Cost Squeeze –  September Outlook for Coking Coal, Coke, and Iron Ore
[SMM Analysis]Expectations Game under Cost Squeeze – September Outlook for Coking Coal, Coke, and Iron Ore
14 hours ago