2024 Magnesium Market Annual Review [SMM Analysis]

Published: Dec 29, 2024 15:02 (GMT+8)
[SMM Analysis: 2024 Magnesium Market Annual Review] Reviewing this year's magnesium market, it can be summarized as short-term uncertainty shrouding the market, while the future remains promising. Against the backdrop of the carbon neutrality era, lightweighting is a crucial approach for the automotive industry to achieve energy conservation and emission reduction. Magnesium, being only two-thirds the weight of aluminum, has made the application of magnesium alloys in automobiles an important trend for weight reduction, bringing magnesium metal gradually into the spotlight...

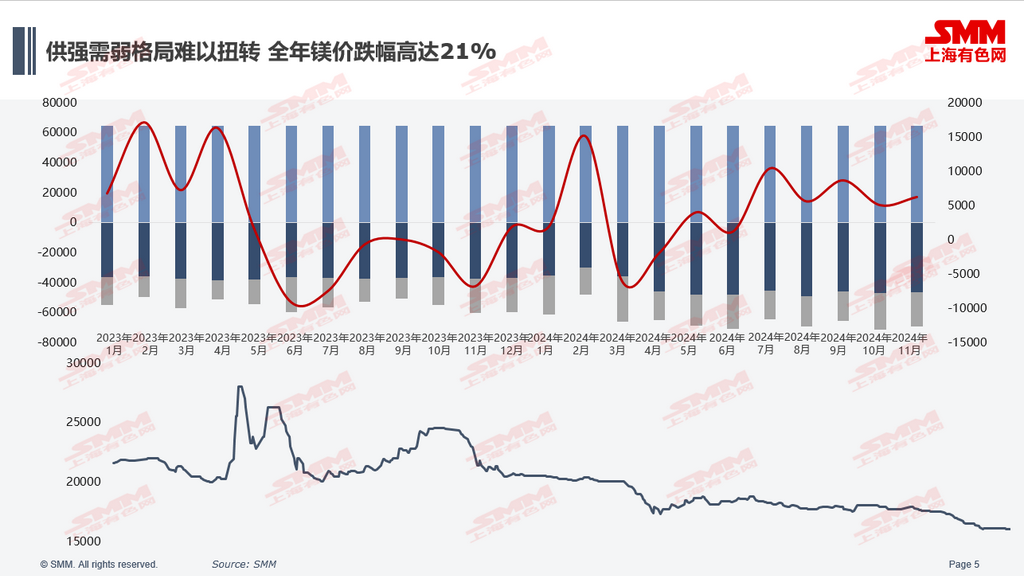
Reviewing this year's magnesium market, it can be summarized as short-term uncertainty but promising prospects for the future. Against the backdrop of carbon neutrality, lightweighting has become a crucial approach for the automotive industry to achieve energy conservation and emission reduction. Magnesium, being only two-thirds the weight of aluminum, has made the application of magnesium alloys in automobiles an important trend for weight reduction, bringing magnesium metal into the spotlight. However, under the guidance of weak current realities but strong expectations, magnesium plants showed unprecedented enthusiasm for resuming production. The concentrated and large-scale resumption of production by magnesium plants led to a supply-demand imbalance in the magnesium ingot market, resulting in a stepwise downward trend in magnesium prices in 2024.

Specifically, by the end of 2023, magnesium plants that had been shut down due to semi coke rectification gradually resumed production, leading to a steady increase in magnesium ingot supply. During the Chinese New Year period, magnesium plants that continued production contrasted sharply with downstream sectors that reduced or halted production, causing magnesium ingot inventory to rise rapidly. Correspondingly, magnesium prices began to plummet, dropping to 17,300 yuan/mt by the end of March.

The significant decline in magnesium prices increased production pressure on magnesium plants, prompting many to announce maintenance plans. In the short term, magnesium prices bottomed out and rebounded. However, the maintenance plans announced earlier by magnesium plants offset the original maintenance schedules for August and September, resulting in a weak supply and demand situation for magnesium prices in Q3. From the overall production data, production in Q2 and Q3 remained relatively stable, with minimal fluctuations.

In Q4, plants that had undergone maintenance gradually returned to full-capacity production. In October, magnesium ingot production increased to 84,000 mt, while magnesium ingot inventory in the Fugu region approached 60,000 mt, with overall inventory expected to exceed 80,000 mt. The supply-strong and demand-weak pattern reopened the downward channel for magnesium prices. As of today, magnesium prices have fallen to 16,000 yuan/mt, marking an annual decline of 14.3%. With magnesium prices breaking through the break-even line for magnesium plants, news of production cuts and halts began to spread in the market. However, supported by the previously accumulated magnesium ingot inventory, downstream sentiment remained pessimistic, leaving little upward momentum for magnesium prices.
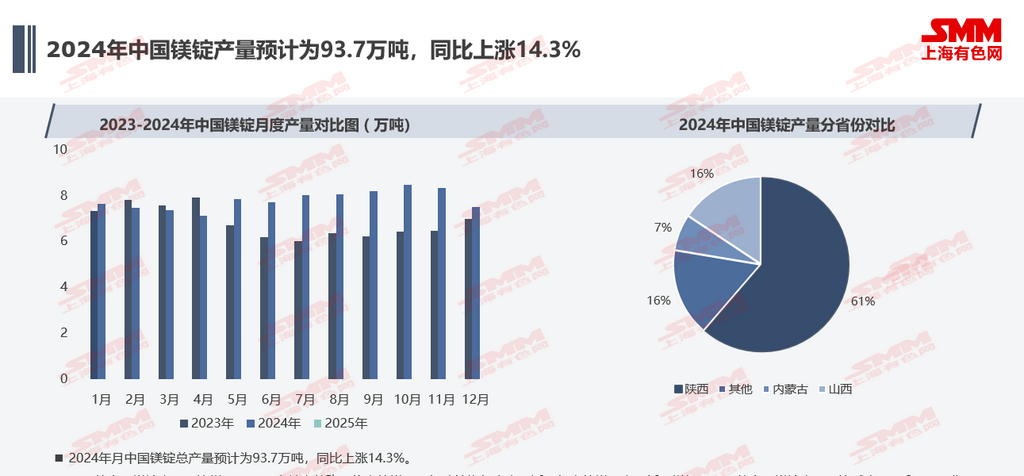
Reviewing China's magnesium ingot supply in 2024, production is expected to reach 937,000 mt, up 14.3% YoY. The increase in China's magnesium ingot production in 2024 mainly stems from the resumption of production by magnesium plants in the Fugu region. According to the 2024 provincial comparison of China's magnesium ingot production, Shaanxi is expected to account for 61% of total magnesium ingot production, up from 50%.
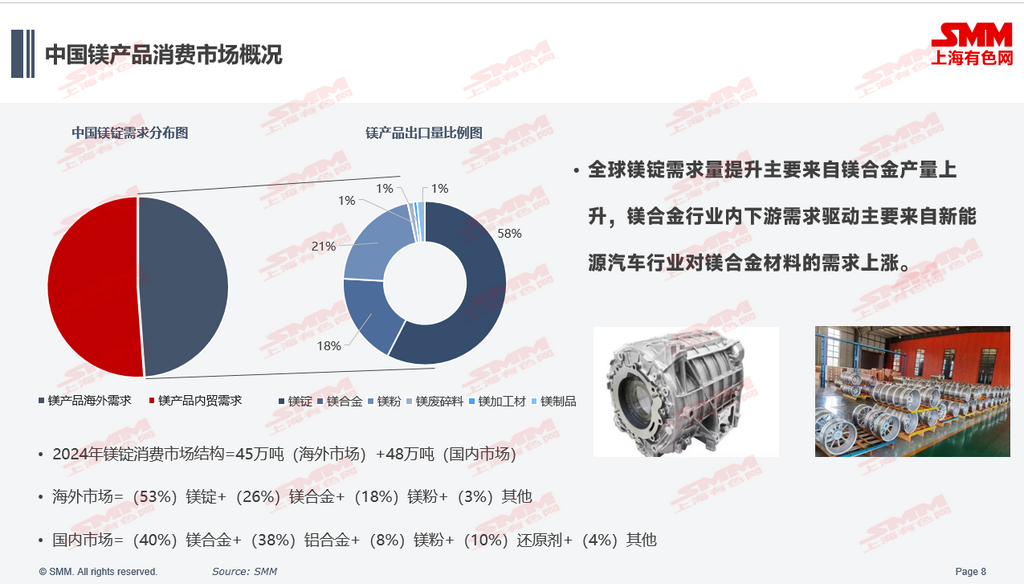
From the perspective of domestic and international demand, the structure of the magnesium ingot consumer market in 2024 can be roughly described as 450,000 mt for the overseas market and 480,000 mt for the domestic market. Looking at the overseas market, magnesium ingots account for 58% of the total export volume of magnesium products in 2024, followed by magnesium alloys and magnesium powder.

In the domestic magnesium ingot market, magnesium alloys hold the largest share at 40%, followed by aluminum alloys at 38%, with desulfurizers and reducing agents accounting for 8% and 10%, respectively. Magnesium ingots are used as additives in aluminum plants, steel mills, and titanium plants, and the demand changes in these three sectors are closely related to the demand conditions of aluminum plants, steel mills, and titanium plants. Growth potential in these three areas is limited. The global increase in magnesium ingot demand mainly comes from the rise in magnesium alloy production, with downstream demand in the magnesium alloy industry primarily driven by the growing demand for magnesium alloy materials in the NEV industry.

Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.

For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
Magnesium ingot demand remains weak, with transaction center edging down [SMM Magnesium Ingot Spot Express]
11 hours ago
Magnesium ingot demand remains weak, with transaction center edging down [SMM Magnesium Ingot Spot Express]
Read More
Magnesium ingot demand remains weak, with transaction center edging down [SMM Magnesium Ingot Spot Express]
[Persistent weak demand for magnesium ingot pulls transaction center slightly lower] The magnesium ingot market in China showed pronounced weakness, with the transaction center pulling back to 15,700 yuan/mt. Smelters' willingness to hold prices firm weakened and low-priced supply increased. Combined with sluggish demand and mounting inventory pressure, market conditions are unlikely to improve in the short term.
11 hours ago
Insufficient Demand Support, Magnesium Ingot Remains in the Doldrums in the Short Term [SMM Magnesium Ingot Spot Express]
Sep 28, 2026 17:30 (GMT+8)
Insufficient Demand Support, Magnesium Ingot Remains in the Doldrums in the Short Term [SMM Magnesium Ingot Spot Express]
Read More
Insufficient Demand Support, Magnesium Ingot Remains in the Doldrums in the Short Term [SMM Magnesium Ingot Spot Express]
[Insufficient demand support; magnesium ingot remains in the doldrums in the short term] The magnesium ingot market is in the doldrums, with stable supply but weak domestic and overseas demand. The double-festival market performance fell short of expectations and is unlikely to see significant fluctuations again. The market turning point is expected after the National Day holiday.
Sep 28, 2026 17:30 (GMT+8)
Weekly Magnesium Output Rises 4.11% as Plants Resume Production, But Future Uncertainty Looms
Sep 28, 2026 09:19 (GMT+8)
Weekly Magnesium Output Rises 4.11% as Plants Resume Production, But Future Uncertainty Looms
Read More
Weekly Magnesium Output Rises 4.11% as Plants Resume Production, But Future Uncertainty Looms
【SMM Weekly Magnesium Output Flash Report】From September 18 to September 24, the weekly output of national sample magnesium plants reached 23,177 tons, with a weekly operating rate of 76.04%, up 4.11% month-on-month. According to research, most of the primary magnesium smelting enterprises that carried out maintenance in the early ten days of this month had a maintenance period of 5 to 10 days, and all of them have successively ignited furnaces or resumed production to produce magnesium ingots since last week, leading to a slight rebound in the market supply of magnesium ingots; another smelting enterprise in Shanxi plans to ignite and resume production next week. However, the supply increment may be difficult to sustain, as some enterprises have stated that they will suspend production for maintenance again after the National Day, mainly due to excessively high production costs. Amid the intertwining of production resumption and maintenance, the subsequent trend of primary magnesium output remains unclear.
Sep 28, 2026 09:19 (GMT+8)