

On October 25, 2024, SMM invited industry representatives to gather in Nanchang, Jiangxi, to participate in a seminar on the recycling and price trends of waste lead-acid batteries. Attendees shared numerous insights on industry pain points, particularly the challenges in recycling, pricing, compliance, and environmental protection policies.
SMM compiled the following based on representative speeches and industry data:
1. Overcapacity and excessive competition: China's secondary lead industry suffers from severe overcapacity, with raw material supply falling short of demand. Companies engage in cutthroat competition to secure battery scrap resources, further driving up material prices and squeezing profit margins. Despite multiple suggestions for cooperation and self-discipline, the actual effect has been limited.
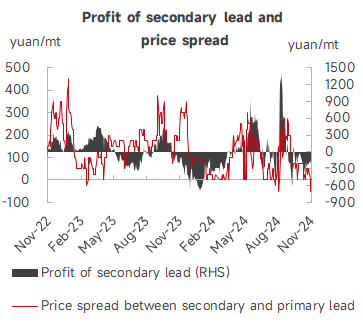
2. Large price fluctuations vs. poor profits: In recent years, the price volatility of waste lead-acid batteries has increased. Even with high lead prices, companies struggle to achieve stable profits. The market pricing mechanism has not effectively transmitted to the end-use sector, resulting in thin profit margins for producers.
3. Lack of a unified pricing mechanism for battery scrap: Nationwide, the battery scrap market still has issues with black market transactions. Some non-compliant companies engage in "grey area" transactions to obtain higher profits, further squeezing the survival space of legitimate enterprises.
4. Imbalance in pricing and pricing mechanisms: The market price of waste batteries does not accurately reflect their scrap nature, with severe price fluctuations. Recyclers leverage resource advantages to raise prices, leading to thin refinery profits and creating a "resource binding" phenomenon, hindering the establishment of a reasonable pricing mechanism. The lack of a unified industry guide price forces companies to raise purchase prices to maintain production.
5. Lack of effective industry self-discipline and alliance mechanisms: The industry lacks strong alliances or self-discipline organizations, leading to frequent cutthroat competition and price wars. The meeting suggested forming industry associations or alliances to promote healthy industry development through price guidance and establishing price control mechanisms.
6. Policy and tax burdens: The reverse invoicing policy and the implementation of the Fair Competition Review Regulations have many uncertainties, such as inconsistent tax policy execution and interpretation across regions, and different tax handling methods among companies, further increasing costs and inconveniences. Factors like tax inconsistency and weak policy enforcement add to the complexity of business operations.
7. Difficulties in integrating the battery scrap recycling end: The meeting pointed out that most recycling companies in China are small-scale and regionally restricted, unable to effectively conduct nationwide business. Different local environmental protection requirements, with some local governments mandating that waste batteries be recycled locally and requiring special permits for cross-province transportation, increase operational difficulty. Such regional segmentation leads to uneven resource distribution and limits the overall development of the industry.
8. Environmental regulations: As China is a party to the Basel Convention, it is difficult to import waste batteries. Other countries, such as South Korea, define battery scrap as "urban mine resources," thereby circumventing solid waste import and export regulations. Attendees called for domestic adoption of similar models to open broader recycling and import channels for domestic companies.
9. High overseas scrap prices: Several speakers noted that the cost of raw materials for waste lead-acid batteries overseas (e.g., the US) has also been rising, from $700/mt in the past to $900/mt now, directly impacting the profit margins of the recycling industry. The increase in raw material prices puts pressure on recycling and production companies, limiting the profitability of companies throughout the industry chain.
In summary, the current pain points of the secondary lead industry are concentrated in overcapacity, insufficient raw material supply, restricted recycling channels, and financial and tax compliance. These factors intertwine, posing significant operational challenges for the industry. These pain points constrain the healthy development of the secondary lead industry, urgently requiring policy coordination and industry self-discipline to achieve standardized and sustainable development.



