SHANGHAI, Jun 1 (SMM) – At the opening of the SMM 2023 Indonesia International Nickel and Cobalt Industry Chain Conference on May 30, SMM is honoured to have invited Luhut, Minister of the Coordinating Ministry of Maritime Affairs and Investment Republic Indonesia and several other important Indonesian government officials.
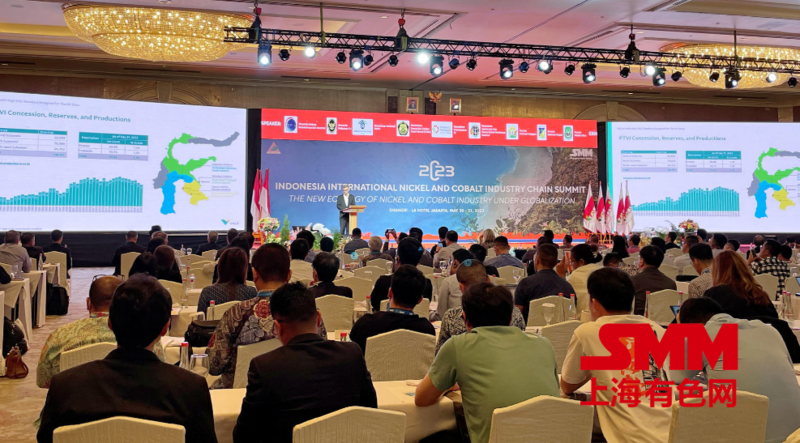
At the meeting, Bai Fan, senior director of SMM Consulting & Research, said that nickel used in power batteries will grow rapidly in the next five years and become the most important force driving of nickel consumption in batteries. The Indonesian stainless steel industry has developed rapidly due to cost and resource advantages, and still has great growth potential. It is estimated that by 2027, the global refined nickel production will reach 1.01 million mt in metal content, and the production growth will mainly come from China's new electrodeposition nickel projects. In order to seek better development, Chinese enterprises are looking for opportunities to "go global". From the perspective of resources, quality, and environmental protection, it is more advantageous to invest in the stainless steel industry in Indonesia.
Background introduction
In the next five years, stainless steel and new energy batteries will remain the main downstream sectors of global nickel consumption, but the historical growth rate will not be sustainable
As an important raw material in batteries, nickel is widely used in electric vehicles, energy storage batteries and other fields. Due to the rapid development of new energy industry, the demand potential for nickel in the battery field is huge. With the increase in the number of power batteries and nickel content of a single power battery, the nickel used in power batteries will grow rapidly in the next five years and become the most important force driving of nickel consumption in batteries.
Indonesian stainless steel industry develops rapidly due to cost and resource advantages
As the region with the highest stainless steel production in the world, mainland China produced 32.39 million mt of stainless steel in 2022. Indonesia's stainless steel industry has developed rapidly due to cost and resource advantages, and still has great development potential in the future.
There are differences in the structure of nickel used in the global #300 stainless steel industry
There are differences in the structure of nickel used in the global #300 stainless steel industry. The proportion of scrap used in #300 stainless steel industry in developed countries is bigger than that in China as the former has more mature recycling system and end-use products reach end-of-life at an earlier date.
Stainless steel raw materials
It is estimated that by 2027 the global refined nickel production will reach 1.01 million mt in metal content
It is predicted that the global refined nickel capacity and production will show positive growth. It is estimated that by 2027, the global refined nickel production will reach 1.01 million million mt in metal content, and the production growth will mainly come from China's new electrodeposition nickel projects.
According to SMM analysis, due to the impact of the Covid pandemic, the output of some overseas companies declined in 2020-2021.
The growth of refined nickel production from 2022 to 2027 will be mainly contributed by China and Indonesia, and the new capacity will basically be electrodeposition nickel. Because China is the main consumer of refined nickel and has a high degree of dependence on imports, China will beef up domestic production to reduce its dependence on imports, making China a major contributor to refined nickel production growth.
It is expected that 2023-2024 will see concentrated release of new electrodeposition nickel capacity
The persistent inversion of the price difference between nickel sulphate and refined nickel has stimulated the expansion of electrodeposition nickel capacity in the past two years, boosting the proportion of electrodeposition nickel in the world's total refined nickel capacity, with China being a major contributor. It is expected that 2023-2024 will see concentrated release of new electrodeposition nickel capacity.
Since the extreme event in nickel market last year, the spot prices of pure nickel have fluctuated at a high level for a long period of time. This drove a large number of domestic nickel salt enterprises to resume production of refined nickel since mid-June 2022. At the same time, driven by high profits, many domestic and overseas companies have started to build new electrodeposition nickel production lines from 2022.
New electrodeposition nickel capacity is forecast to account for 23% of China's total pure nickel capacity in 2023. New electrodeposition nickel capacity will continue to expand in 2024 and may account for 28% of China's total pure nickel capacity under conservative estimates. In addition, there are also new refined nickel projects overseas in 2023, but unlike domestic production lines, they are featured by large capacity in a single project and smaller number of enterprises. It is estimated that new electrodeposition nickel capacity will account for 9% of the global total pure nickel capacity in 2023, and the share is estimated to climb to 10% by 2024, mainly driven by China.
As falling nickel prices in February-March 2023 eroded the profit margins of electrodeposition nickel produced with MHP or nickel sulphate, some electrodeposition nickel producers delayed the commissioning of new production lines. However, it is worth noting that the profit margins of electrodeposition nickel produced with MHP or nickel sulphate are constantly changing. As such, once profit margins are restored, new electrodeposition nickel capacity that has been delayed will be put into operation.
Rapidly expanding NPI production in the next five years threatens to erode the market share of FeNi in downstream applications
Before 2020, NPI capacity was transferring from China to Indonesia, thus China's market share gradually shrank. From 2020 to 2024, Indonesia's NPI capacity showed explosive expansion, causing NPI capacity to shift into a surplus from 2022, while FeNi supply was relatively stable. The downstream sectors of FeNi are mainly stainless steel, alloy and foundry. FeNi will squeeze the market share of pure nickel in stainless steel and will then be eroded by NPI.
In 2022, 300-series dominated stainless steel output, led by#304 stainless steel
Enlightenment on Indonesian investment
Enlightenment on investment in stainless steel industry in Indonesia
(1) Why invest overseas?
Resources: According to SMM statistics, China's nickel sulphide ore output was about 80,000 mt in metal content in 2021, and the total nickel ore import was about 430,000 mt in metal content. Imports of laterite nickel ore were 340,000 mt in metal content and imports of nickel sulphide ore were 90,000 mt in metal content, reflecting heavy reliance on imports. For laterite nickel ore, China not only has small reserves and low grade, but also has high mining costs, which makes China uncompetitive in laterite nickel ore mining. Laterite nickel ore is the main raw material of NPI, while the latter is an important raw material in stainless steel production. As a major stainless steel producer, China needs to import a large amount of laterite nickel ore every year to develop its stainless steel industry. With the implementation of Indonesia’s nickel ore export ban, some Chinese mining companies and smelters began to make plans for building smelting and refining projects overseas.
Cost: NPI is the main raw material for stainless steel production. Compared with Indonesian companies, Chinese companies have obvious disadvantages in NPI production costs. Chinese companies import nickel ore mainly from the Philippines, whose nickel ore is of lower grade and more expensive than Indonesian ore. As a result, the raw material costs of Chinese NPI enterprises are higher than their competitors in Indonesia. As the NPI market is expected to maintain an oversupply in the future, the competitiveness of small stainless steel enterprises with high costs in China will be further weakened. In order to seek better development, Chinese enterprises are looking for opportunities to "go global".
(2) Why invest in Indonesia?
Resources: In terms of reserves, Indonesia is one of the countries with the richest mineral resources in the world, and its nickel ore resources rank first in the world. In 2021, nickel ore reserves in Indonesia were 25.4 million mt in metal content. The Philippines' nickel ore reserves in 2021 were merely 4.04 million mt in metal content, which is only 1/6 of that in Indonesia.
Ore grade: Indonesia is rich in high-grade nickel ore resources, and the grade of laterite nickel ore is significantly higher than that of the Philippines. The grade of nickel ore in the Philippines is mostly between 0.8% and 1.4%.
Other aspects: Indonesia is an important country of the "21st Century Maritime Silk Road" under China's "Belt and Road" initiative. Before 2010, Chinese mining companies began to go to Indonesia to carry out exploration of lateritic nickel ore and mining investment.
Environmental protection: Indonesia's environmental protection policy is less stringent, which is more suitable for enterprises to build factories locally. The strict environmental protection policy in the Philippines leads to high environmental protection expenses in the production process of enterprises.
For more about this conference, please click: 2023 INDONESIA NICKEL AND COBALT INDUSTRY CHAIN CONFERENCE