Copper Inventory in Major Chinese Markets Added 9,100 mt This Week

Published: Feb 17, 2023 13:41 (GMT+8)
Source: SMM
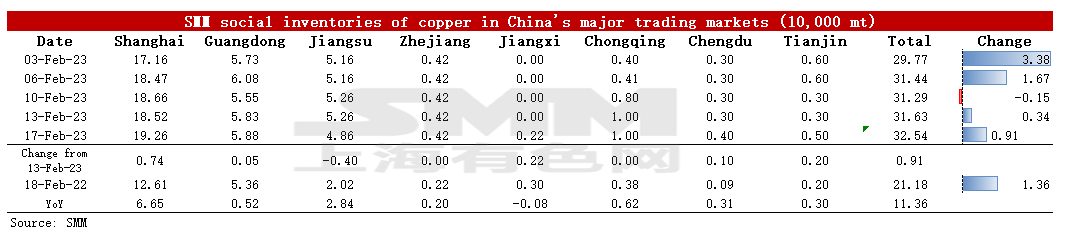
As of Friday February 17, copper stocks in mainstream Chinese Markets tracked by SMM increased by 9,100 mt to 325,400 mt from Monday, an increase of 12,500 mt from last Friday, and an increase of 128,800 mt from the level before Chinese New Year holidays.

SHANGHAI, Feb 17 — As of Friday February 17, copper stocks in mainstream Chinese Markets tracked by SMM increased by 9,100 mt to 325,400 mt from Monday, an increase of 12,500 mt from last Friday, and an increase of 128,800 mt from the level before Chinese New Year holidays. The post-holiday stock accumulation was slightly above the accumulation of 122,700 mt in the same period last year.  National Domestic inventory has accumulated for eight consecutive weeks since the end of December. Only Jiangsu saw inventory declines. Total inventory climbed 113,600 mt compared to 211,800 mt in the same period last year. The inventory was 66,500 mt higher than the same period last year in Shanghai, 5,200 mt higher than the same period last year in Guangdong, and 28,400 mt higher in Jiangsu. The inventory in Zhejiang exceeded the same period last year by 2,000 mt, and that in Chongqing was 6,200 mt more. Chengdu saw a 3,100 mt increase in inventory from the same period last year, and Tianjin reported a growth of 3,000 mt.

Specifically, the inventory in Shanghai increased by 7,400 mt to 192,600 mt compared with Monday. There were large volumes of arriving shipments of domestic copper especially those from smelters to warehouses due to the delivery early in the week. Arrivals of imported copper were limited, though. The inventory in Guangdong increased by 500 mt to 58,800 mt. This week, the consumption in Guangdong has diminished significantly. SMM understood that due to the previous excessive production and the slow stockpiling by downstream producers recently, the copper semis processing plants have high inventories and were forced to lower operating rates. This can also be reflected in the decline in the average daily shipments from Guangdong. The decline in inventory in Jiangsu was mainly due to the improvement in downstream stockpiling.

As far as we know, the arrivals of imported copper next week will remain limited, and the market supply will be mainly domestic copper. The total supply is expected to remain stable. Consumption next week would underperform this week due to the month-end cash flow issues and downstream consumption having not improved noticeably. To sum up, SMM expect that inventory will continue to increase next week.
Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.

For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
Emerita's Iberian Belt West Project PFS Shows $776M NPV, 21-Year Mine Life
Oct 30, 2026 22:39 (GMT+8)
Emerita's Iberian Belt West Project PFS Shows $776M NPV, 21-Year Mine Life
Read More
Emerita's Iberian Belt West Project PFS Shows $776M NPV, 21-Year Mine Life
Emerita releases PFS for Iberian Belt West zinc-lead-copper project: US$776m NPV, 21-year life Emerita Resources (TSXV: EMO) released on 29 October a positive Pre-Feasibility Study (PFS) for its 100%-owned Iberian Belt West (IBW) polymetallic project in Spain's Iberian Pyrite Belt. The study shows an after-tax NPV of US$776 million at 8%, a 23.51% IRR, a 21-year mine life and a 1.9-year after-tax payback. Initial capital is US$567 million including contingency. Initial probable reserves total 23.4 million tonnes grading 2.30% zinc, 1.13% lead, 0.45% copper, 53 g/t silver and 1.07 g/t gold.
Oct 30, 2026 22:39 (GMT+8)
Copper Market Struggles with Tax Changes and Supply Shortages in October 2026
Oct 30, 2026 19:47 (GMT+8)
Copper Market Struggles with Tax Changes and Supply Shortages in October 2026
Read More
Copper Market Struggles with Tax Changes and Supply Shortages in October 2026
In October 2026, the tax-inclusive price spread between primary metal and scrap narrowed from 3,979 yuan/mt at the start of the week to 1,896 yuan/mt, then recovered to the 2,826-2,976 yuan/mt range. The price difference between copper cathode rod and secondary copper rod also compressed from 1,250 yuan/mt to an extreme low below 430 yuan/mt before rebounding to 1,450 yuan/mt. Although the book substitution advantage fluctuated, it was largely eroded by cost factors most of the time.
Oct 30, 2026 19:47 (GMT+8)
【Flash | Busan Molybdenum Oxide Rebounds as Buying Activity Explodes】
Oct 30, 2026 18:09 (GMT+8)
【Flash | Busan Molybdenum Oxide Rebounds as Buying Activity Explodes】
Read More
【Flash | Busan Molybdenum Oxide Rebounds as Buying Activity Explodes】
SMM market research found that Busan molybdenum oxide has rebounded sharply from the October 28 low of $32.30/lb Mo, with actual transactions continuing at $33.10–33.30/lb Mo. One container has been confirmed traded at $33.30/lb Mo. Buying activity in Busan has intensified significantly, and SMM preliminarily estimates that today’s transaction volume has reached seven to eight containers so far, with further deals still emerging. SMM will continue to update the total volume and latest transaction levels.
Oct 30, 2026 18:09 (GMT+8)