Copper Inventory in Major Chinese Markets Increased 33,800 mt

Published: Feb 3, 2023 15:13
Source: SMM
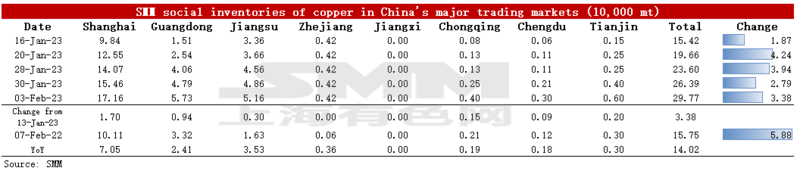
As of Friday February 3, copper stocks in mainstream markets increased by 33,800 mt from Monday to 297,700 mt, and grew by 61,700 mt from Saturday January 28. The inventories increased 101,100 mt from pre-CNY holidays levels and were 86,600 mt above the same period last year.

SHANGHAI, Feb 2 (SMM) - As of Friday February 3, copper stocks in mainstream markets increased by 33,800 mt from Monday to 297,700 mt, and grew by 61,700 mt from Saturday January 28. The inventories increased 101,100 mt from pre-CNY holidays levels and were 86,600 mt above the same period last year. Since the end of December, the domestic copper inventory has increased for six consecutive weeks. The growth is mainly attributable to more shipments from smelters around CNY holidays and inactive downstream purchases. The inventory has increased across China with the total inventory 140,200 mt higher than the 157,500 mt in the same period last year. The inventory was 70,500 mt higher than the same period last year in Shanghai, 24,100 mt higher in Guangdong, and 35,300 mt higher in Jiangsu. The inventory in Zhejiang exceeded the same period last year by 3,600 mt, and that in Tianjin was 3,000 mt higher than the same period last year.

Specifically, the inventory in Shanghai increased by 17,000 mt from Monday to 171,600 mt, and the inventory in Jiangsu increased by 3,000 mt to 51,600 mt. Shipments arrivals of imported cargoes were limited this week, and the stock accumulation was mainly driven by higher shipments from smelters. The smelters in north China delivered cargoes aggressively to east China before delivery of the SHFE front-month copper contract, which is the main cause of the inventory growth in east China. Inventory in Guangdong increased by 9,400 mt to 57,300 mt. The slower downstream replenishment after CNY holidays has resulted in a big growth in inventory, which is reflected in the recent slow growth in the daily average shipments from Guangdong. Overall, the domestic market is in oversupply.

Domestic smelters will contribute to most of the arriving shipments next week as the imports of seaborne cargoes will be limited. Big discounts will fuel the deliveries by smelters. Downstream consumption is expected to gradually recover next week. On the whole, both supply and consumption will pick up next week, and the stock accumulation will be slower than this week.

Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.

For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
Downstream wait-and-see sentiment is strong, SHFE copper premium under pressure at high levels [SMM Shanghai spot copper]
8 mins ago
Downstream wait-and-see sentiment is strong, SHFE copper premium under pressure at high levels [SMM Shanghai spot copper]
Read More
Downstream wait-and-see sentiment is strong, SHFE copper premium under pressure at high levels [SMM Shanghai spot copper]
[SMM Shanghai Spot Copper] Looking ahead to tomorrow, as some imported cargoes gradually arrive at ports, the available supply in the Shanghai market will be somewhat replenished compared with the earlier period, exerting certain pressure on spot premiums. On the demand side, although SHFE copper prices pulled back during last night's night session, according to SMM, actual procurement volumes from end-users remain relatively limited, with downstream players overall maintaining a strong wait-and-see sentiment. Purchases are still mainly need-based, and acceptance of the current high-premium cargoes is not high. Meanwhile, as market pricing gradually shifts to the 2610 contract, spot premiums against the October contract remain at a relatively high level. Although some suppliers are willing to lower their quotes, their willingness to sell at low prices is also limited. Overall, under the combined effect of increased imported arrivals and weak end-use demand, the center of spot copper quotes against the SHFE copper 2610 contract is expected to edge lower tomorrow. However, considering that available circulating cargoes have not yet become notably ample and suppliers still intend to hold prices firm, spot premiums are expected to remain at a relatively high level.
8 mins ago
Contract rollover releases rigid demand; discounts in North China narrow and rise [SMM North China Spot Copper]
2 hours ago
Contract rollover releases rigid demand; discounts in North China narrow and rise [SMM North China Spot Copper]
Read More
Contract rollover releases rigid demand; discounts in North China narrow and rise [SMM North China Spot Copper]
In North China today, spot #1 copper cathode was quoted at a discount of 150-50 yuan/mt against the front-month contract, with an average discount of 100 yuan/mt, up 60 yuan/mt from the previous trading day. The average transaction price was 107,447 yuan/mt, down 1,300 yuan/mt from the previous trading day.
2 hours ago
Large price spread between futures contracts on delivery day; spot trades sluggish [SMM South China spot copper]
2 hours ago
Large price spread between futures contracts on delivery day; spot trades sluggish [SMM South China spot copper]
Read More
Large price spread between futures contracts on delivery day; spot trades sluggish [SMM South China spot copper]
2 hours ago
Copper Inventory in Major Chinese Markets Increased 33,800 mt - Shanghai Metals Market (SMM)