April 14, 2022, Brussels, Belgium
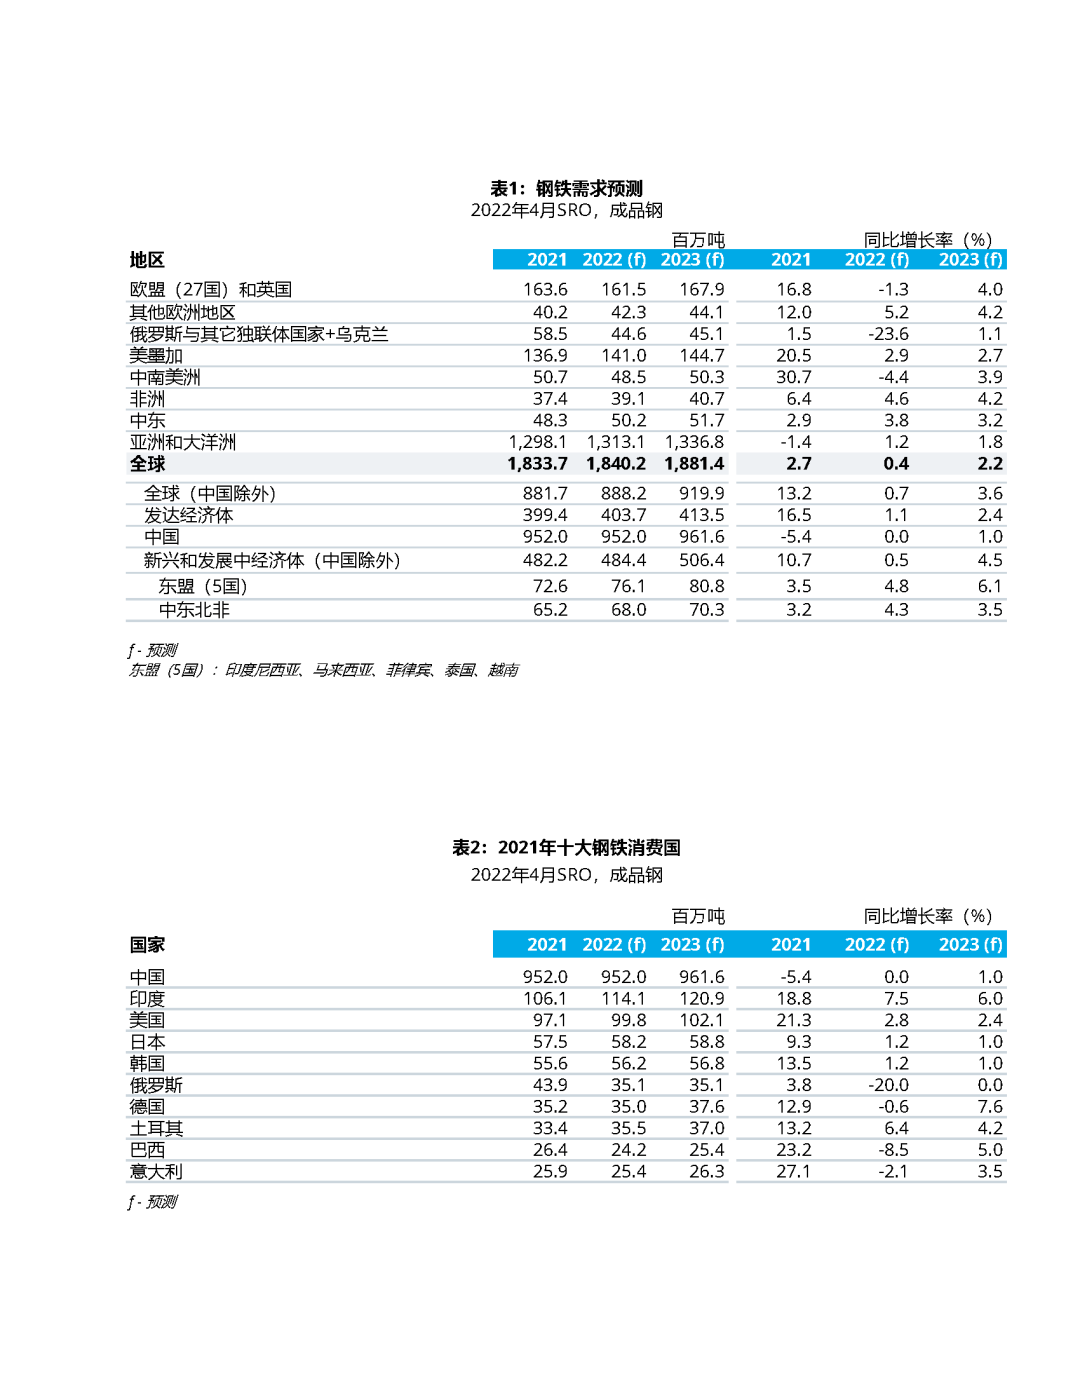
The World Iron and Steel Association today released the latest short-term (2022-2023) steel demand forecast. Global steel demand will continue to grow 0.4 per cent to 1.8402 billion tonnes in 2022, following a 2.7 per cent increase in 2021, according to the report. In 2023, global steel demand will continue to grow by 2.2 per cent to 1.8814 billion tons. In the context of the conflict between Russia and Ukraine, the current prediction results are highly uncertain.
Steel demand forecast is shrouded in inflation and uncertainty
Commenting on the forecast, M á ximo Vedoya, chairman of the World Iron and Steel Association's market research committee, said: "when we release this short-term steel demand forecast, Ukraine is in the midst of a human and economic disaster since Russia launched its military operation. We all hope that this war will come to an end and peace will come as soon as possible.
In 2021, despite the supply chain crisis and several rounds of COVID-19 epidemic, the recovery momentum was stronger than expected in many areas under the impact of the pandemic. However, global steel demand growth slowed in 2021 as a result of an unexpected slowdown in the Chinese economy. Steel demand in 2022 and 2023 is highly uncertain. Our original expectations of a sustained and stable recovery have been shaken by the outbreak of the war in Ukraine and high inflation. "
Forecasting background
The impact of the conflict will also vary from region to region, depending on the region's direct trade and financial exposure to Russia and Ukraine. The conflict has had a direct and devastating impact on Ukraine, with Russia bearing the consequences accordingly, and the European Union has also been greatly affected by its dependence on Russian energy and its geographical proximity to the conflict zone. Not only that, the impact has also spread around the world because of rising energy and commodity prices, especially the raw materials needed for steel production, as well as continued disruptions in the supply chain, which plagued the global steel industry even before the war began. In addition, financial market volatility and a high degree of uncertainty will affect investor confidence.
The global spillover of the war in Ukraine, coupled with a slowdown in China's economic growth, is expected to slow global steel demand growth in 2022. In addition, the continued outbreak of the COVID-19 epidemic in some parts of the world, especially in China, and rising interest rates have also brought downside risks to the economy. The expected tightening of US monetary policy will exacerbate the risk of financial vulnerability facing emerging economies.
The forecast of global steel demand in 2023 is highly uncertain. The premise of our prediction is that the stand-off between Russia and Ukraine in Ukraine will come to an end in 2022, but the sanctions against Russia will remain largely unchanged.
In addition, the geopolitical landscape surrounding Ukraine will have a far-reaching impact on the global steel industry. It includes the adjustment of global trade pattern, the transformation of energy trade and its impact on energy transformation, and the global supply chain is facing continuous reallocation.
China
China's demand for steel slowed significantly in 2021 as a result of tough government controls on real estate developers. Steel demand will remain stable in 2022 as a result of government efforts to promote infrastructure investment and stabilize the real estate market. The stimulus measures introduced in 2022 are likely to support a small increase in steel demand in 2023. If the deteriorating external environment leads to more challenges for the Chinese economy, then the Chinese government will introduce more solid stimulus measures, thus bringing upward potential to the economy.
Developed economy
Despite sporadic outbreaks and manufacturing supply chain constraints, steel demand recovered strongly in 2021, particularly in the European Union and the United States. However, due to inflationary pressures and events surrounding Ukraine, the outlook for steel demand weakens in 2022. The impact of the war in Ukraine is particularly pronounced in the EU region because of its high dependence on Russian energy and the influx of refugees. In developed economies, steel demand is expected to grow by 1.1 per cent in 2022 and 2.4 per cent in 2023, following a 16.5 per cent recovery in 2021.
Developing economies (except China)
In developing economies, the recovery process in developing economies faces additional challenges as the impact of the pandemic continues and inflation outbreaks, as well as the resulting monetary tightening cycle in many emerging economies. Steel demand in developing economies (excluding China) grew by 10.7 per cent in 2021 after falling 7.7 per cent in 2020, slightly higher than our previous forecast. In 2022 and 2023, emerging economies will continue to face challenges from the deteriorating external environment, the war between Russia and Ukraine, and monetary tightening in the United States, which will lead to slow growth in 2022 and 2023, 0.5% and 4.5%, respectively.
Steel consumption industry
Although China's construction activity shrank in 2021, globally, construction activity continued to recover from the epidemic blockade by 3.4%. In many countries, the recovery is driven by infrastructure investment as part of recovery plans, and infrastructure investment and energy transformation investment are likely to continue to drive construction growth in the coming years. However, the construction industry also faces some resistance from high costs and interest rates.
In the automotive industry, supply chain bottlenecks blocked the recovery in the second half of 2021, and the recovery in the global auto industry in 2021 was disappointing. The war in Ukraine is likely to delay the return of the supply chain to normalcy, especially in Europe. Despite the collapse in global car production, the electric vehicle sector grew rapidly during the pandemic. Global electric vehicle sales will reach 6.6 million in 2021, almost twice as many as in 2020. The share of electric vehicles in total car sales rose from 2.49% in 2019 to 8.57% in 2021.