Impact from high copper prices and secondary copper slowed recovery in copper rods produced with copper cathode

Published: Mar 23, 2021 10:27 (GMT+8)
Downstream cable companies have placed orders moderately amid price volatility previously. Weak copper demand resulted in slow delivery-taking, accumulating inventory of raw material or finished products at producers. That increased cash pressure at copper rod plants using secondary copper as feedstock, affecting secondary copper suppliers. Secondary copper suppliers have sold aggressively and collected payments to ease cash flow issues.

SHANGHAI, Mar 23 (SMM)—Downstream cable companies have placed orders moderately amid price volatility previously. Weak copper demand resulted in slow delivery-taking, accumulating inventory of raw material or finished products at producers. That increased cash pressure at copper rod plants using secondary copper as feedstock, affecting secondary copper suppliers. Secondary copper suppliers have sold aggressively and collected payments to ease cash flow issues. Cash flow issues are expected to intensify due to high tax payment in April. As such, factories and suppliers should liquidate stocks.
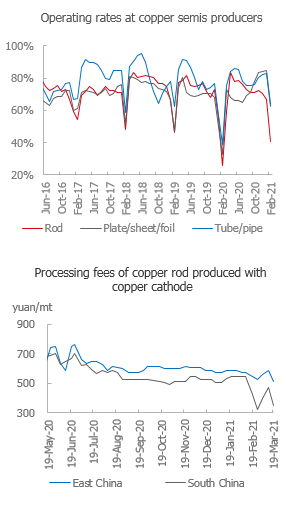
Operating rates at copper rod producers using secondary copper as raw material should return to a high level in March against accumulated orders, boosting secondary copper demand. However, decreased new orders at the end of last week and increased cash flow issues have limited the interest in purchasing. That combined with the demand for stock liquidation at suppliers, will keep normal supply and demand.

The average weekly price of #1 bare bright copper without invoice stood at 59,930 yuan/mt, an increase of 200 yuan/mt compared with the previous week, and the weekly average price difference between copper cathode and copper scrap stood at 2,217 yuan/mt, an increase of 385 yuan/mt. The average weekly discount of copper rod produced with secondary copper stood at 1,464 yuan/mt against the SHFE front-month copper contract, growing the advantage compared to copper rod produced with copper cathode.

For imported copper scrap, cif quotes for #1 copper scrap were Comex July copper less $0.21/lb, and offers for birch/cliff were Comex July copper less $0.36/lb. US brass was quoted at $5,650-5,850/mt. The coefficient for copper granules (98%) against LME copper stood at 93%, and the coefficient for bare bright copper against LME copper at 96-96.5%, on a cif basis.

Improved consumption of copper rod produced with secondary copper had significant impact on consumption of copper rod produced with copper cathode

Many producers of copper rod using secondary copper as feedstock have seen high orders, reporting strong supply and demand. The price spread between copper cathode and copper scrap has returned to above 2,000 yuan/mt, and discounts of copper rod produced with secondary copper reached a high of 1,550 yuan/mt against the SHFE front-month copper contract. Low-priced copper rods produced with secondary copper have been more desirable for downstream companies amid high copper prices, and this depressed consumption of copper rod produced with copper cathode which has been already weak. 

The impact of poor wire and cable demand and secondary copper rods has slowed recovery in the market of copper rod produced with copper cathode. Most of the producers are unlikely to return to normal production levels in March. As consumption picks up amid warmer weather, the market sentiment of the wire and cable industry should rise. Consumption of copper rods produced with copper cathode is expected to improve in April. However, the overly high copper price will depressed consumption. The current inventory of finished products at copper rod producers using copper cathode as feedstock stands at high levels. Producers will prioritise stock depletion and new orders at end users are unlikely to pass to copper rod plants using copper cathode as raw material any time soon. We believe that consumption of copper rods produced with copper cathode in April would hardly return to the peak season level of previous years.


Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.

For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
【Flash | Outokumpu Trims October Surcharges for Several Moly-Bearing Stainless Grades】
46 mins ago
【Flash | Outokumpu Trims October Surcharges for Several Moly-Bearing Stainless Grades】
Read More
【Flash | Outokumpu Trims October Surcharges for Several Moly-Bearing Stainless Grades】
Outokumpu’s October 2026 North American coil alloy surcharges edged lower across several molybdenum-bearing grades. The surcharge for 316L 2.5% Moly fell 0.5% MoM to $4,291.96/t, while 316L/4404 declined 0.7% to $3,886.31/t. Duplex 2205 was broadly flat at $4,225.83/t. Surcharges for 904L and 254 SMO fell 0.8% and 0.6% to $8,236.48/t and $8,914.62/t, respectively. These are alloy surcharges rather than full steel prices and reflect nickel, chromium and other alloy inputs as well as molybdenum.
46 mins ago
【Flash | India’s BHEL Opens Tender for 40 Tonnes of Ferromolybdenum】
49 mins ago
【Flash | India’s BHEL Opens Tender for 40 Tonnes of Ferromolybdenum】
Read More
【Flash | India’s BHEL Opens Tender for 40 Tonnes of Ferromolybdenum】
Bharat Heavy Electricals Limited’s Haridwar plant has opened a tender for 40 tonnes of ferromolybdenum. The procurement uses a reverse auction and may be split 60:40 between up to two suppliers. The delivery schedule calls for 25 tonnes within 30 days of the contract start and 15 tonnes within 60 days. Under the price-adjustment formula, 80% of the invoiced price is linked to the Argus 60% Mo ferromolybdenum ex-works India index. The tender also includes a quantity option of up to 25%. No award or transaction price has yet been disclosed.
49 mins ago
【Flash | US July Molybdenum Shipments Outpace Production as Output Rises YoY】
6 hours ago
【Flash | US July Molybdenum Shipments Outpace Production as Output Rises YoY】
Read More
【Flash | US July Molybdenum Shipments Outpace Production as Output Rises YoY】
USGS reported US molybdenum concentrate production of 3,390 tonnes of contained molybdenum in July 2026, down 2.6% MoM but up 6.3% YoY. Jan–Jul output totaled 24,330 tonnes, up about 4.2% based on monthly data. July shipments reached 3,730 tonnes, up 4.8% MoM and 17.7% YoY, while YTD shipments rose about 5.7% to 24,600 tonnes. Shipments exceeded monthly output by about 340 tonnes. USGS notes that shipments include domestic sales, exports and transfers to company plants, while some producer data are monthly estimates derived from quarterly or annual disclosures.
6 hours ago

