Silicon prices trended lower in December amid weakened demand and capital pressure of cargo holders

Published: Jan 14, 2021 14:30 (GMT+8)
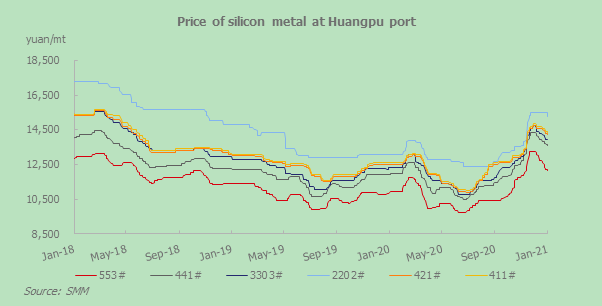
Silicon prices of various grades started to decline after a short period of stability in December 2020. The pressure on the supply side began to appear after the demand fell with high stocks of downstream raw material.

SHANGHAI, Jan 14 (SMM) — Silicon prices of various grades started to decline after a short period of stability in December 2020. The pressure on the supply side began to appear after the demand fell with high stocks of downstream raw material. Traders who stockpiled a large number of low-priced goods continued to cut prices in order to deplete inventories.

In addition, silicon plants were under capital shortage before year-end, and individual large plants were still under pressure to reduce their stocks. Under the combined effects of various negative factors, silicon prices gradually fell.
Operating rates of primary aluminium alloy declined slightly in December due to the decline in end-user automobile demand. Operating rates of secondary aluminium alloy basically maintained, while most aluminium alloy factories actively stockpiled from October to November, so there were only a few orders for rigid demand in December. Most of them are to digest low-priced inventories in the hands of holders, and the overall market turnover weakened significantly.

Secondary aluminium alloy companies in Guangdong, Zhejiang and other regions that rely on imported scrap aluminium as raw materials are facing the dilemma of lack of raw materials in 2021 due to changes in the import of scrap aluminium policies. Sluggish sentiment about future operating rates is also a reason for limiting purchases.

Silicone procurement was relatively stable in December, and two unexpected maintenance companies have not resumed production. Part of the monomer production capacity is planned to be shut down for maintenance before and after Chinese New Year. However, considering the pandemic outbreak and the CNY holiday, most of the organic silicon monomer plants are able meet the production volume of one and a half months to two months in January. Most of chemical-grade silicon is signed in the monthly order, and the price change lags behind that of metallurgical-grade silicon. Therefore, the monthly prices of 421# silicon was basically stable at 14,800-14,900 yuan/mt in early January.

On the export side, large-scale foreign aluminium companies successively restocked in December and released orders for Q2 2021. The number of orders allocated to the Chinese market decreased sharply compared with the previous quarter due to the high domestic silicon prices, the sharp rise in the exchange rate of RMB against the US dollar, and the soaring ocean freight. One of them all transferred to overseas procurement.

The two major downstreams of organic silicon and polysilicon had the willingness to restock in January before CNY. In addition, the overall transaction of the stocks of some aluminium alloy factories was better than that in December. The downstream areas of Hebei, Shandong and other regions were affected by the Covid-19 driven lockdowns in Hebei and completed stockpiling in early January. Inventories plus goods in transit are sufficient until at least the end of February. The pandemic has worsened and CNY is approaching, major Xinjiang manufacturers are worried about shipments, so they continue to cut prices for shipments in January to reduce the inventory pressure caused by the stagnation of transportation.

Domestic transportation vehicles were already less than the same period in previous years in mid-January. It is expected that domestic transactions will basically end around January 20, and the slight downward trend will continue. If the pandemic does not hinder the recovery of domestic automobile transportation after CNY, the inventory pressure accumulated by some small factories during CNY will be gradually released, and it will take time for domestic and overseas demand to recover. Silicon prices are likely to maintain a downward trend in the following weeks.

For more information on the silicon metal sector, please subscribe to China Silicon Metal Monthly database.


Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.

For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
[SMM Chromium Flash] Global Steel Demand Forecast Turns Flat in 2026 as China Weakens, Recovery Expected in 2027
20 hours ago
[SMM Chromium Flash] Global Steel Demand Forecast Turns Flat in 2026 as China Weakens, Recovery Expected in 2027
Read More
[SMM Chromium Flash] Global Steel Demand Forecast Turns Flat in 2026 as China Weakens, Recovery Expected in 2027
[SMM Chromium Flash] Global Steel Demand Forecast Turns Flat in 2026 as China Weakens, Recovery Expected in 2027
The World Steel Association (worldsteel) revised its global steel demand outlook on 12 October, forecasting demand to remain broadly unchanged at 1.722 billion tonnes in 2026, before increasing by 1.7% to 1.752 billion tonnes in 2027. The downgrade largely reflects weaker-than-expected demand in China, where steel demand is projected to contract by 2.0% in 2026 and a further 1.0% in 2027. Outside China, demand is expected to grow by 1.5% in 2026 and accelerate to 4.0% in 2027. For the chromium market, the subdued global steel outlook suggests that a broad-based recovery in steel-related demand may take longer to materialize, although prospects vary by region. India’s steel demand is forecast to grow by 7.9% in 2026, while demand in the United States is projected to increase by 2.0%. These divergent regional trends provide important context for chrome ore and ferrochrome producers assessing end-market conditions. However, the forecast covers total steel demand rather than stainless steel specifically, so it does not directly quantify future chromium consumption.
20 hours ago
[SMM Chromium Flash] South Africa’s August Chrome Ore Exports Fall 11% as Ferrochrome Shipments Rebound 20%​
20 hours ago
[SMM Chromium Flash] South Africa’s August Chrome Ore Exports Fall 11% as Ferrochrome Shipments Rebound 20%​
Read More
[SMM Chromium Flash] South Africa’s August Chrome Ore Exports Fall 11% as Ferrochrome Shipments Rebound 20%​
[SMM Chromium Flash] South Africa’s August Chrome Ore Exports Fall 11% as Ferrochrome Shipments Rebound 20%​
South Africa’s chrome ore exports fell 10.75% month-on-month to 2.36 million tonnes in August 2026, while high-carbon ferrochrome exports increased 20.0% to 117,180 tonnes, highlighting diverging trends in the country’s chromium trade. China remained the leading destination for chrome ore, receiving 1.67 million tonnes, or 70.8% of total shipments, despite a 6.09% monthly decline. Ferrochrome exports, meanwhile, were supported by stronger shipments to North America, with Canada receiving 26,373 tonnes and the United States 26,029 tonnes, together accounting for 44.7% of South Africa’s ferrochrome exports.​ The contrasting movements point to softer overseas demand for raw chrome ore alongside a recovery in ferrochrome shipments, particularly to North America. However, the monthly rebound in ferrochrome exports does not yet establish a sustained recovery in domestic smelting, while China’s dominant share of ore exports leaves South African shipments exposed to changes in Chinese purchasing activity.
20 hours ago
[SMM Chromium Week Review] Export Flows Rebound as China's Port Stocks Rise and African Prices Diverge
21 hours ago
[SMM Chromium Week Review] Export Flows Rebound as China's Port Stocks Rise and African Prices Diverge
Read More
[SMM Chromium Week Review] Export Flows Rebound as China's Port Stocks Rise and African Prices Diverge
[SMM Chromium Week Review] Export Flows Rebound as China's Port Stocks Rise and African Prices Diverge
Published: Oct 16, 2026.
21 hours ago

