Impact on China domestic supply/demand of the new scrap law and the operational challenges of the law to primary and secondary aluminium industries

Đã xuất bản: Dec 4, 2020 16:32
Leo Yi, senior analyst at SMM, explained the challenges posed by the new solid waste law to China’s aluminium scrap supply and operations at secondary aluminium producers

SUZHOU, Dec 4 (SMM)—On today’s Shanghai Metals Market’s 2020 Nonferrous Metals Industry Chain Annual Conference held in Suzhou, Leo Yi, senior analyst at SMM, explained the challenges posed by the new solid waste law to China’s aluminium scrap supply and operations at secondary aluminium producers.  

According to Yi, the new solid waste law will lead to an increase in aluminium ash processing costs due to insufficiency of qualified processing capacity and greater difficulties in trans-provincial transport of hazardous waste.  

“But there are several measures for producers to take to tackle the problem, such as building their own aluminium ash treatment capacity, waiting for the commissioning of new technologies and new processing capacities or reducing production to lower aluminium ash output,” Yi suggested.

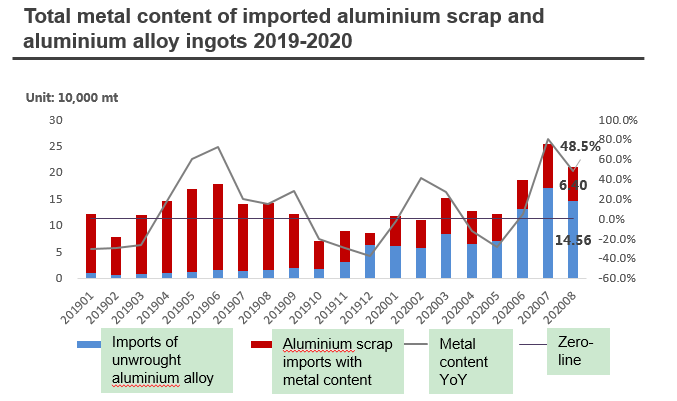
Yi also gave his insights on profits of imported secondary aluminum amid under the new solid waste import policy and COVID-19 pandemic. He said that the abolition of tariffs on secondary aluminium ingots is likely to expand aluminium ingots imports.
Source: SMM

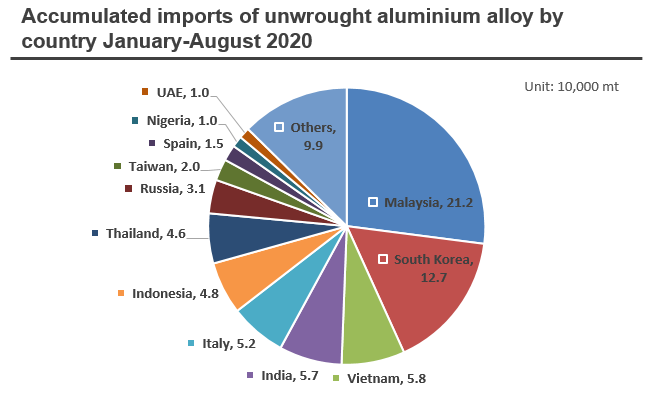
Among the countries that account for over 1% of Chinese unwrought aluminium alloy imports, agreed tariffs in Malaysia, Vietnam, Indonesia, Thailand and other ASEAN countries as well as South Korea stood at zero, with imports of 490,000 mt, accounting for 62.6%; the Asia-Pacific Trade Agreement tariff for India stood at 4.6%, with an import volume from India of 57,000 mt, accounting for 7.3%; imports from the countries with agreed tariffs stood at 547,000 mt, accounting for 69.9% of the total. Imports of aluminium alloy ingots from Italy, Russia, Taiwan, Spain, Nigeria and the United Arab Emirates, which top the list of China’s suppliers, should increase significantly if the import tariffs for secondary aluminium ingots are abolished.
Source: SMM

The import window for aluminium alloy ingots shrank significantly and closed at one point in August 2020, resulting in a sharp decline in new import orders of aluminium alloy ingot. This will reduce aluminium alloy ingots imports noticeably from September to November. If tariffs on imported aluminium alloy ingots are cancelled in November, the window for aluminium alloy ingots imports will expanded, increasing new import orders significantly. In this scenario, aluminium alloy ingots imports from December to January are expected to exceed 100,000 mt, giving an impact on domestic aluminium alloy ingots.

“Import opportunity for non-standard aluminium alloy and aluminium scrap increased amid weaker profits of imported ADC12,” Yi said, “Although aluminium scrap import has been freed up, requirements remain strict. At present, most of the overseas aluminium scrap cannot meet the requirements for direct import. Overseas aluminium scrap processing capacity will be insufficient in the short term. Profits are expected to drive imports of non-standard aluminium alloy due to pricing based on discounts and premiums of aluminium, ensuring profits without risk. Overseas aluminium scrap that has not been processed or is of low quality are likely to be imported in the form of non-standard ingots.”


Tuyên bố về Nguồn Dữ liệu: Ngoại trừ thông tin công khai, tất cả dữ liệu khác được SMM xử lý dựa trên thông tin công khai, giao tiếp thị trường và dựa trên mô hình cơ sở dữ liệu nội bộ của SMM. Chúng chỉ mang tính chất tham khảo và không cấu thành khuyến nghị ra quyết định.

Để biết thêm thông tin hoặc có thắc mắc gì, vui lòng liên hệ: lemonzhao@smm.cn
Để biết thêm thông tin về cách truy cập báo cáo nghiên cứu, vui lòng liên hệ:service.en@smm.cn
Tin Liên Quan
Nhập khẩu và xuất khẩu hợp kim nhôm chưa gia công của Trung Quốc cho thấy xu hướng trái chiều trong tháng 8 năm 2026
2 giờ trước
Nhập khẩu và xuất khẩu hợp kim nhôm chưa gia công của Trung Quốc cho thấy xu hướng trái chiều trong tháng 8 năm 2026
Đọc thêm
Nhập khẩu và xuất khẩu hợp kim nhôm chưa gia công của Trung Quốc cho thấy xu hướng trái chiều trong tháng 8 năm 2026
[SMM Nhôm nhanh] Theo số liệu hải quan, nhập khẩu hợp kim nhôm chưa gia công tháng 8/2026 đạt 71.500 tấn, tăng 0,2% so với cùng kỳ và tăng 19,5% so với tháng trước. Lũy kế nhập khẩu từ tháng 1 đến tháng 8/2026 đạt 564.900 tấn, giảm 17,4% so với cùng kỳ. Xuất khẩu hợp kim nhôm chưa gia công tháng 8/2026 đạt 51.600 tấn, tăng 77,6% so với cùng kỳ nhưng giảm 11,9% so với tháng trước. Lũy kế xuất khẩu từ tháng 1 đến tháng 8/2026 đạt 348.700 tấn, tăng 100,1% so với cùng kỳ.
2 giờ trước
Sản lượng pin lithium của Trung Quốc dự kiến tăng 9% trong tháng 9 nhờ nhu cầu lưu trữ năng lượng toàn cầu
18 giờ trước
Sản lượng pin lithium của Trung Quốc dự kiến tăng 9% trong tháng 9 nhờ nhu cầu lưu trữ năng lượng toàn cầu
Đọc thêm
Sản lượng pin lithium của Trung Quốc dự kiến tăng 9% trong tháng 9 nhờ nhu cầu lưu trữ năng lượng toàn cầu
Theo dữ liệu khảo sát hàng tháng từ nhiều chuỗi ngành, lịch sản xuất pin lithium tháng 9 của Trung Quốc dự kiến vượt 330 GWh, tăng khoảng 9% so với tháng trước. Pin lưu trữ năng lượng chiếm khoảng 130 GWh, gần 40% tổng lượng. Tăng trưởng mảng lưu trữ năng lượng chủ yếu đến từ các dự án quy mô lớn ở nước ngoài, với nhiều trạm lưu trữ năng lượng tại Trung Đông, châu Âu và Mỹ đang gấp rút hòa lưới trước cuối năm. Khách hàng nước ngoài đang tập trung mua pin lưu trữ năng lượng dung lượng lớn từ 314Ah trở lên, các dây chuyền sản xuất hiện có của các nhà sản xuất pin hàng đầu đã kín lịch đến giữa tháng 10.
18 giờ trước
Doanh số xe năng lượng mới tháng 9/2026 tăng 45,6% so với cùng kỳ, thị phần tiến gần 50%
18 giờ trước
Doanh số xe năng lượng mới tháng 9/2026 tăng 45,6% so với cùng kỳ, thị phần tiến gần 50%
Đọc thêm
Doanh số xe năng lượng mới tháng 9/2026 tăng 45,6% so với cùng kỳ, thị phần tiến gần 50%
Dữ liệu từ CAAM cho thấy sản lượng và doanh số xe năng lượng mới (NEV) tháng 9/2026 lần lượt đạt 1,617 triệu và 1,604 triệu chiếc, tăng 42,7% và 45,6% so với cùng kỳ năm trước. Tỷ trọng NEV trong tổng doanh số xe mới đạt 49,7%. Sản lượng/doanh số NEV lũy kế từ tháng 1 đến tháng 9 đạt khoảng 12,6 triệu chiếc, thị phần tiến gần một nửa. Xuất khẩu NEV tháng 9 đạt 222.000 chiếc, tăng hơn gấp đôi so với cùng kỳ. Dữ liệu từ CPCA cho thấy doanh số bán lẻ xe du lịch NEV nội địa tháng 9 đạt khoảng 1,296 triệu chiếc, tăng 15,5% so với cùng kỳ, tỷ lệ thâm nhập hàng tháng đạt 57,8%, mức cao kỷ lục mới.
18 giờ trước