[SMM Hot Volume] short-term inventory reduction is difficult to stop supply growth and subsequent regional inventory may be differentiated.

Published: Oct 31, 2019 17:17 (GMT+8)

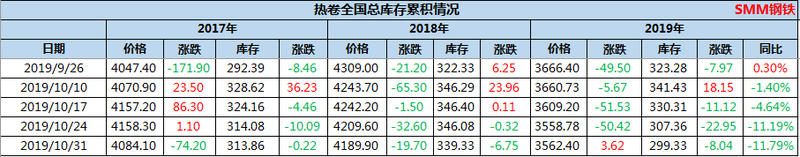
The total national stock of hot rolling this week was 2.9933 million tons, a month-on-month ratio of-2.6% and a year earlier of-10.9%. Although the overall still continues to fall, driving the fundamental pressure to ease. However, it is worth noting that the rate of decline has narrowed compared with last week. If the environmental protection production line is not as strong as expected, the overall inventory may have a tendency to accumulate under the circumstances of the increase in new production capacity of steel mills, the entry of foreign imported resources into the market, and the relative decline in demand in the north. At the same time, it is expected that there may be differentiation in the degree of regional accumulation. Among them,


Social inventory: 2.0837 million tons this week, month-on-month-4.1%, year-on-year-14.5%. The social library still continues to descend the database state, but the speed of lowering the library has slowed down. The continuation of the decline this week is mainly due to the persistence of rigid demand, and in recent days, when the rebound in futures volumes has boosted market sentiment and spot prices have been relatively stable, overall transaction recovery has led to a decline in the social base. However, the main reason for the slowdown is that under the influence of the Wuxi viaduct incident in the past few weeks, traffic control in most areas has been tightened, and the speed of spot storage in ports has dropped sharply. After a few weeks of adjustment, the pace of storage of resources has recovered slightly, and the total amount of storage has increased compared with the previous two weeks, which has led to a narrowing of the rate of decline this week.


Steel mill inventory: 909600 tons this week, month-on-month + 1.0%, year-on-year-1.2%. The decline and increase of the factory reservoir is mainly due to the resumption of production at the end of the maintenance of some steel mills and the weak receipt of orders by the lock price steel mills. According to SMM research statistics, Angang, WISCO, Angang and other steel mills this week hot rolling line maintenance basically completed at the beginning of this week, the average daily output is about 35000 tons. At the same time, the steel mill resource shipment maintained a stable pace in the early stage, so in the case of the increase in production, the steel mill inventory has accumulated. In addition, the current market pessimism is pervasive, traders have a strong willingness to reduce the warehouse, coupled with continued losses, so the lock price steel mills book fewer resources. In addition, most of the terminals are mainly purchased on demand, so the overall result is that the lock price steel factory receives the order weakly and the steel factory inventory increases.


In addition, it is worth noting that although the pace of storage of resources has slightly recovered this week, the transport of one car, one roll mode still can not keep up with the unloading speed of incoming resources, resulting in the port backlog of resources is still too much, the actual social library pressure is greater than the data feedback. In addition, Shenglong Metallurgical new 1780mm hot rolling line has now been put into production, the follow-up new production will increase one after another, and mainly put in South China, superimposed foreign import resources will soon enter the market (this part of the resources invested in the South China market) and the northern resources continue to go south, then the inventory pressure in the follow-up South China market may further increase, when the South China spot price will continue to fall in the case of the intensification of the contradiction between supply and demand.


Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.

For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
Western Mining Subsidiary Receives 17-Year License for Qinghai Polymetallic Mine
14 hours ago
Western Mining Subsidiary Receives 17-Year License for Qinghai Polymetallic Mine
Read More
Western Mining Subsidiary Receives 17-Year License for Qinghai Polymetallic Mine
On September 22, Western Mining announced that its wholly owned subsidiary, Qinghai Ganxin Mining Development Co., Ltd. (“Ganxin Mining”), recently obtained a Mining License issued by the Department of Natural Resources of Qinghai Province. The mine, named the Geermu Tuwenchahan Iron Polymetallic Mine of Qinghai Ganxin Mining Development Co., Ltd., covers iron, copper, gold, molybdenum, zinc, lead, and silver as the permitted mining commodities. The mining license is valid from August 3, 2026, to August 30, 2043.
14 hours ago
Korea Zinc's $7.4B US Project Passes Environmental Assessment, Set for 2029 Trial Operations
Sep 21, 2026 17:02 (GMT+8)
Korea Zinc's $7.4B US Project Passes Environmental Assessment, Set for 2029 Trial Operations
Read More
Korea Zinc's $7.4B US Project Passes Environmental Assessment, Set for 2029 Trial Operations
On September 21, Korea Zinc announced that its $7.4 billion US manufacturing project had passed the environmental impact assessment. The facility is scheduled to begin trial operations in 2029 and commercial production the following year, producing 11 critical minerals, 12 non-ferrous metals and semiconductor-grade sulfuric acid. In April, Korea Zinc said it had completed the acquisition of a local zinc smelter and other related companies. The company plans to implement the project by expanding and upgrading the existing facilities.
Sep 21, 2026 17:02 (GMT+8)
Australia Reviews Anti-Dumping Duties on Galvanized Steel from India, Malaysia, Vietnam Amid Zinc Concerns
Sep 11, 2026 18:30 (GMT+8)
Australia Reviews Anti-Dumping Duties on Galvanized Steel from India, Malaysia, Vietnam Amid Zinc Concerns
Read More
Australia Reviews Anti-Dumping Duties on Galvanized Steel from India, Malaysia, Vietnam Amid Zinc Concerns
On September 9, 2026, Australia initiated its second sunset review of anti-dumping measures on galvanized steel sheet from India, Malaysia and Vietnam, and separately launched a sunset review of countervailing measures on imports from India. The review covers July 2025-June 2026, with the final report expected by February 11, 2027. As galvanized steel is the largest end-use sector for zinc, the measures directly affect export costs and competitiveness, potentially impacting Australia’s domestic zinc demand and supply chain. Maintaining the duties would provide some protection for domestic steel and coating capacity, while termination could increase low-priced imports and affect regional zinc consumption. The final outcome remains subject to the authorities’ determination.
Sep 11, 2026 18:30 (GMT+8)

