[SMM Thread] Regional differences are prominent, and spot prices fall differently after National Day.

Đã xuất bản: Oct 22, 2019 17:29
Recently, environmental production restrictions have not been significantly effective, supply does not reduce but rose slightly, making the market bearish sentiment shrouded in heavy inventory for a long time. According to SMM statistics, the current mainstream market thread spot price decline in 30-270 yuan / ton, of which most concentrated in the 100-200 yuan / ton decline range. Due to the great differences between regions, SMM has carried out a follow-up study of this phenomenon.

SMM10, 22nd:

Recently, environmental production restrictions have not been significantly effective, supply does not reduce but rose slightly, making the market bearish sentiment shrouded in heavy inventory for a long time.
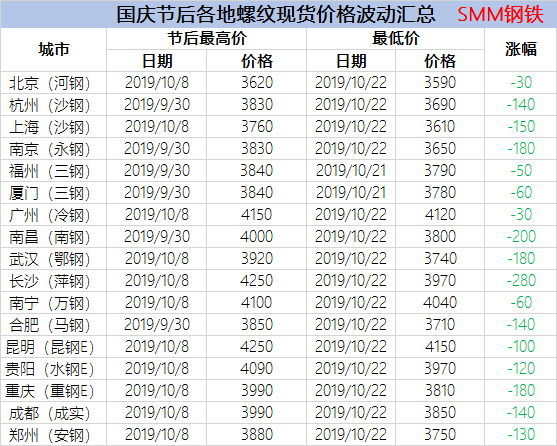
According to SMM statistics, the current mainstream market thread spot price decline in 30-270 yuan / ton, of which most concentrated in the 100-200 yuan / ton decline range. Due to the great differences between regions, SMM has carried out a follow-up study of this phenomenon.

Tons of steel fell in the area of 100-200 yuan: the mainstream area.

According to SMM research, in addition to the northeast due to the gradual cold weather, demand weakening, the current rigid demand for building materials in other regions show full toughness, good shipping condition. However, the phenomenon of large inventory pressure is more common. And at present, in addition to Beijing, Tianjin, Hebei and surrounding areas, other areas controlled by environmental protection and production restrictions in previous years (such as Jiangsu) have no policy notice, the market generally has increased expectations for supply pressure, so the operation of selling goods at low prices before the arrival of the off-season is more common.

At the same time, as pessimism still occupies the mainstream of the market, if the scope of production restriction has not been further expanded, the late spot price or weak back to the sky, continue to operate weakly.

In the range of $30 to $60 per ton of steel:

North China: Hebei, Shanxi and other Beijing-Tianjin-Hebei and surrounding areas have entered the stage of environmental protection and production restriction during the heating season, especially under the influence of pollution weather. Tangshan City, a "major town", issued two more stringent notices on the 15th and 18th of this month, and a number of traders reported that they had fewer supplies in their hands, supporting the market price to a certain extent. In addition, in Beijing, for example, inventories in September have been lower than in the same period last year. Although the recent year-on-year growth turned negative to positive, but the current local demand performance is still good, inventory pressure is not great, so the market mentality is also more rational, spot prices are more resilient.

Fujian market: steel mills have a large bargaining power for the market, with a strong willingness to raise prices, coupled with some business feedback has part of the phenomenon of relative shortage of specifications.

South China market: the demand performance is good, the Nanning market has the specification shortage situation, the spot price has the strong support. However, it is reported that the north material southward is already in the start-up, and there will be a more concentrated increment in November, when the increase in supply pressure will suppress the local spot price.

Region with a decline of more than 200 yuan per ton of steel: Hunan

Spot prices in Hunan rose rapidly in September, mainly due to on the one hand, a number of mainstream steel mills production reduction, making the market out of stock phenomenon is more common; on the other hand, the demand suppressed by torrential rain has been concentrated.

The production of mainstream steel mills resumed in October, and due to the high prices in the previous period and the small inflow of external resources, the shortage phenomenon was solved, at the same time, the demand was also stable, so the decline in spot prices after the festival was also beyond the reach of other regions.


 

Tuyên bố về Nguồn Dữ liệu: Ngoại trừ thông tin công khai, tất cả dữ liệu khác được SMM xử lý dựa trên thông tin công khai, giao tiếp thị trường và dựa trên mô hình cơ sở dữ liệu nội bộ của SMM. Chúng chỉ mang tính chất tham khảo và không cấu thành khuyến nghị ra quyết định.

Để biết thêm thông tin hoặc có thắc mắc gì, vui lòng liên hệ: lemonzhao@smm.cn
Để biết thêm thông tin về cách truy cập báo cáo nghiên cứu, vui lòng liên hệ:service.en@smm.cn
Tin Liên Quan
Úc Rà soát Thuế chống bán phá giá đối với Thép mạ kẽm từ Ấn Độ, Malaysia, Việt Nam trong bối cảnh lo ngại về kẽm
11 Sep 2026 18:30
Úc Rà soát Thuế chống bán phá giá đối với Thép mạ kẽm từ Ấn Độ, Malaysia, Việt Nam trong bối cảnh lo ngại về kẽm
Đọc thêm
Úc Rà soát Thuế chống bán phá giá đối với Thép mạ kẽm từ Ấn Độ, Malaysia, Việt Nam trong bối cảnh lo ngại về kẽm
Ngày 9 tháng 9 năm 2026, Australia khởi xướng rà soát cuối kỳ lần thứ hai đối với biện pháp chống bán phá giá thép mạ kẽm từ Ấn Độ, Malaysia và Việt Nam, đồng thời tiến hành rà soát cuối kỳ riêng đối với biện pháp chống trợ cấp áp dụng cho hàng nhập khẩu từ Ấn Độ. Kỳ rà soát từ tháng 7/2025 đến tháng 6/2026, với báo cáo cuối cùng dự kiến công bố trước ngày 11 tháng 2 năm 2027. Do thép mạ kẽm là lĩnh vực tiêu thụ kẽm lớn nhất, các biện pháp này ảnh hưởng trực tiếp đến chi phí xuất khẩu và năng lực cạnh tranh, có khả năng tác động đến nhu cầu kẽm nội địa và chuỗi cung ứng của Australia. Việc duy trì thuế sẽ mang lại sự bảo hộ nhất định cho năng lực sản xuất thép và mạ trong nước, trong khi chấm dứt thuế có thể làm gia tăng hàng nhập khẩu giá rẻ và ảnh hưởng đến tiêu thụ kẽm trong khu vực. Kết quả cuối cùng vẫn phụ thuộc vào quyết định của cơ quan chức năng.
11 Sep 2026 18:30
Dự án mở rộng trị giá 200 triệu USD của JCC Hongyuan Copper đặt mục tiêu nâng công suất lên 550.000 tấn vào năm 2027
7 Sep 2026 15:43
Dự án mở rộng trị giá 200 triệu USD của JCC Hongyuan Copper đặt mục tiêu nâng công suất lên 550.000 tấn vào năm 2027
Đọc thêm
Dự án mở rộng trị giá 200 triệu USD của JCC Hongyuan Copper đặt mục tiêu nâng công suất lên 550.000 tấn vào năm 2027
Dự án mở rộng sản xuất đồng cathode 300.000 tấn/năm của Công ty Đồng Hồng Nguyên JCC, công ty con của Tập đoàn Đồng Giang Tây, đã bước vào giai đoạn thông báo công khai trước khi phê duyệt đánh giá tác động môi trường vào ngày 4 tháng 9, với tổng vốn đầu tư khoảng 1,416 tỷ nhân dân tệ. Dự kiến khởi công vào tháng 9 năm 2026 và hoàn thành vào tháng 12 năm 2027. Sau khi hoàn thành, tổng công suất của Hồng Nguyên JCC sẽ tăng từ 250.000 tấn lên 550.000 tấn.
7 Sep 2026 15:43
Đồng Yên Nhật tăng giá, USD/JPY giảm xuống dưới 159 giữa đồn đoán can thiệp
3 Sep 2026 19:00
Đồng Yên Nhật tăng giá, USD/JPY giảm xuống dưới 159 giữa đồn đoán can thiệp
Đọc thêm
Đồng Yên Nhật tăng giá, USD/JPY giảm xuống dưới 159 giữa đồn đoán can thiệp
[SMM Tin nhanh Kim loại quý] Đồng yên Nhật tăng vọt trong phiên giao dịch thứ Tư, với tỷ giá USD/JPY giảm xuống dưới 159 và đóng cửa giảm 0,92% ở mức 158,69, làm dấy lên đồn đoán về sự can thiệp tiền tệ của Nhật Bản. Chỉ số đô la cũng giảm mạnh, với môi trường đô la yếu hơn hỗ trợ cho kim loại quý.
3 Sep 2026 19:00

