Since the beginning of August, China’s solar cell market has staged a sharp reversal. TOPCon cell prices bottomed out in late July and rebounded rapidly. Compared with the lows seen from late July to early August, mainstream prices as of August 18 had risen by more than 20% across major formats, with gains in some specifications approaching 30%.
The rally was initially supported by a rising cost floor. Since mid-August, however, the pace of price increases has clearly exceeded what can be explained by cost recovery alone. Following the rollout of the U.S. Section 232 measures, expectations for front-loaded procurement across supply chains serving the U.S. market have intensified. Traders have increasingly become marginal buyers of higher-priced cells, further amplifying gains in the spot market.
In contrast, domestic module manufacturers remain reluctant to accept current high cell prices. This means that while the market is being supported by the policy window and export-related stockpiling, whether the rally can evolve from a short-term move into a more sustainable uptrend will ultimately depend on whether higher cell costs can be passed through to module prices and whether domestic demand can take over once the policy-driven export window begins to close.
Current Market: Cost Recovery Sets the Floor, Export Stockpiling Amplifies the Rally
The market began to reverse rapidly in August. According to SMM data, as of August 18, mainstream price ranges for TOPCon G12R, M10 and G12 cells had risen to RMB 0.316-0.367/W, RMB 0.316-0.367/W and RMB 0.319-0.352/W, respectively. Offers for some G12R and M10 cells briefly reached around RMB 0.38/W.
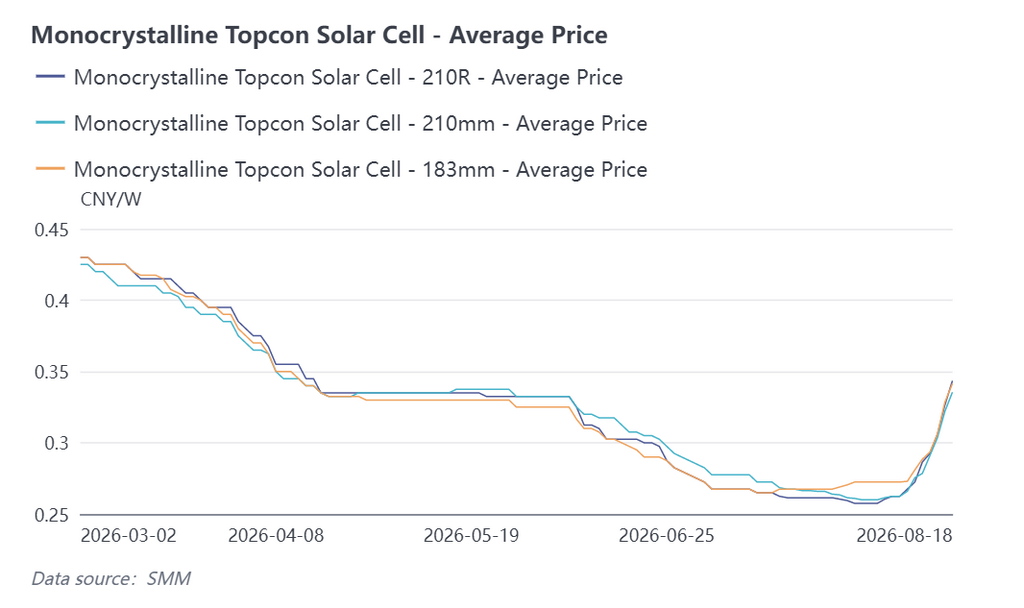
Costs provided the initial foundation for the rebound. Since late July, stronger expectations for higher polysilicon prices, a rapid recovery in wafer prices, and rising costs for silver paste and other auxiliary materials have jointly lifted the cost floor for solar cells and strengthened producers’ willingness to hold firm on offers.
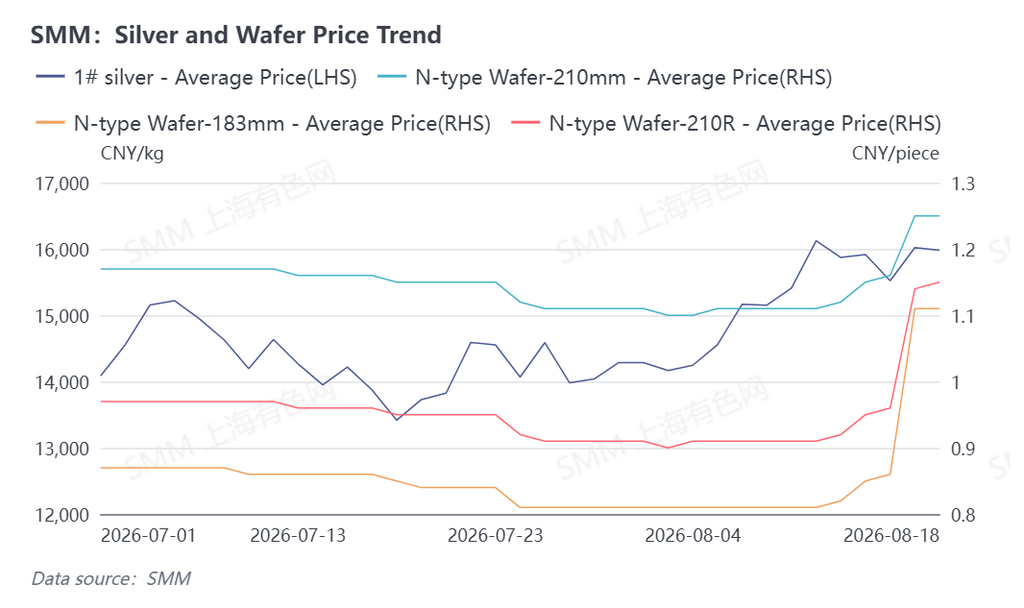
However, cost movements can largely explain why prices were able to rebound from low levels; they do not fully explain the pace of gains since mid-August. The stronger driver behind the acceleration has been rapidly rising expectations for advance procurement following the rollout of the U.S. Section 232 measures.
On August 6, the United States formally announced Section 232 measures covering polysilicon and its derivatives. The measures set minimum import prices of $0.22/W for solar cells and $0.38/W for solar modules. They will take effect at 12:01 a.m. U.S. Eastern Time on December 4, 2026, for covered products entered for consumption or withdrawn from warehouse for consumption. Certain polysilicon derivatives listed in the announcement will also be subject to additional ad valorem duties.
The transition period between the announcement and implementation has prompted front-loaded procurement and inventory building across the Asian solar supply chain serving the U.S. market. Based on current transaction patterns, this incremental demand is becoming an increasingly important marginal driver in the spot market.
According to feedback from supply-chain traders surveyed by SMM, the market could see around 15-20 GW of solar cell stockpiling demand during the policy window, with traders also emerging as key buyers of some higher-priced material.
It is important to stress that the 15-20 GW figure remains an industry survey estimate and market expectation. It does not represent volumes that have already been contracted, prepaid, assigned shipping schedules or exported. Only if a substantial portion of this expected demand is ultimately converted into actual purchase orders will it materially affect near-term cell shipment flows and spot inventories.
Module Makers: Domestic Demand May Take Over, but Acceptance of High Cell Prices Remains Limited
Compared with traders, domestic module manufacturers remain cautious about purchasing high-priced cells.
On the one hand, domestic project demand is expected to improve in Q4, which could support a sequential recovery in module production schedules and cell procurement. On the other hand, module producers remain constrained by end-market tender prices, project returns and their own inventory positions. At present, module makers generally view RMB 0.33-0.35/W as a more acceptable procurement range for solar cells.
In terms of cost pass-through, solar cells have responded relatively quickly in the current round of price increases, but whether module prices can rise in tandem remains uncertain. If module selling prices fail to absorb the increase in cell costs, module producers are more likely to delay procurement, reduce safety inventories, prioritize internally produced cells or adjust production schedules rather than continue chasing higher-priced external supply.
This is likely to lead to greater market segmentation. Cell producers with well-secured export orders may be able to maintain firmer offers, while standard domestic orders and more abundantly supplied formats may remain subject to pricing pressure from module makers.
As a result, the current rally is more likely to remain structural rather than develop into a synchronized increase across all formats and all producers.
Why Could Mid-October Become a Key Turning Point?
It is worth noting that the Section 232 measures do not provide an unrestricted window for imports ahead of implementation. The U.S. presidential proclamation also states that if the Secretary of Commerce determines that a company has stockpiled polysilicon or its derivatives before the measures take effect, the department may coordinate with U.S. Customs and Border Protection to impose import restrictions.
Advance procurement by traders therefore should not be viewed as risk-free front-loading. How U.S. authorities distinguish between normal inventory preparation and policy-avoidance stockpiling, as well as how strictly the provision is ultimately enforced, could also affect actual shipment flows.
The Section 232 measures are scheduled to take effect on December 4, 2026. According to trader feedback, arranging shipments from China or other major Asian production hubs, completing ocean freight and clearing U.S. customs generally requires at least around 40-45 days.
Working backward from the implementation date, shipments intended to enter the U.S. before the new measures take effect may therefore need to depart by around mid-October to provide a more comfortable logistics buffer. From a procurement perspective, the closer the market gets to mid-October, the less time remains to arrange new export orders, which could gradually reduce traders’ willingness to chase higher prices.
Assuming no major changes in logistics conditions, trader purchasing patterns or subsequent U.S. implementation rules, the market could follow a baseline pattern in which export-related stockpiling continues to support orders and prices through August and September. As the available shipping window narrows and compliance risks rise in October, new inquiries may gradually decline. If incremental export procurement weakens materially by mid- to late October, domestic module producers could once again become more influential in setting solar cell prices.
Q4 Outlook: Domestic Demand May Provide a Floor, but Correction Risks Rise After October
From a supply-demand perspective, the solar cell market could see two distinct phases of demand in Q4.
The first phase is concentrated procurement linked to front-loaded exports. Such orders tend to be released quickly and are highly sensitive to delivery timing. Traders may be willing to pay a certain premium to secure product within the available policy window, helping reduce inventories at cell producers and providing continued support to prices.
The second phase would depend more heavily on domestic demand. Q4 project deliveries could lift module production schedules and, in theory, increase solar cell consumption. However, domestic module producers are much more cost-sensitive than traders purchasing against a time-limited export window. Their procurement is more closely tied to immediate production needs, and they are less willing to absorb elevated prices.
In other words, stronger domestic demand could provide downside support, but may not be sufficient to sustain the high prices created during the export-driven procurement window.
Based on this logic, SMM expects solar cell prices to remain relatively firm through August and September, while upward momentum could gradually weaken after entering October. If new export orders begin to decline from early October while module producers continue to resist higher prices, the probability of a downward shift in transaction prices will increase in mid- to late October.
The scale of any correction will depend on the actual volume purchased by traders, incremental production at cell manufacturers and the strength of domestic module demand.
At the same time, if a substantial portion of the expected 15-20 GW of stockpiling demand is converted into trader purchases but downstream consumption ultimately lags the pace of earlier inventory building, stock pressure could increase once the policy window closes.
If part of the material remains in trader inventories or overseas warehouses, subsequent channel restocking demand may effectively have been pulled forward, potentially weakening export orders further in November and December.
Three Indicators to Watch
First, changes in the volume and pricing of solar cell purchases by module manufacturers. If higher-priced transactions remain concentrated among traders while module makers continue to procure only on a low-inventory, just-in-time basis, the rally will still lack sustained downstream support.
Second, cell producer inventories and production schedules. If manufacturers rapidly increase output in response to stronger export orders, but the additional production encounters weaker export demand after October, inventories could begin building again and amplify downward price pressure.
Third, order divergence among different cell formats. High-efficiency products and formats better suited to export demand may remain relatively firm, while more abundantly supplied products primarily serving the domestic market could feel pricing pressure from module makers earlier.
Overall, the impact of the current Section 232-driven market on China’s solar cell sector can be summarized as “near-term export-led destocking, a shift in demand drivers around October, and a return to domestic fundamentals in Q4.”
With traders still driving a significant share of high-priced procurement and module producers yet to broadly accept current cell prices, the rally remains clearly cyclical and structural in nature. As the front-loading window narrows after mid-October, the risk of a correction in solar cell prices is likely to rise materially.
||]