Imported Ore:
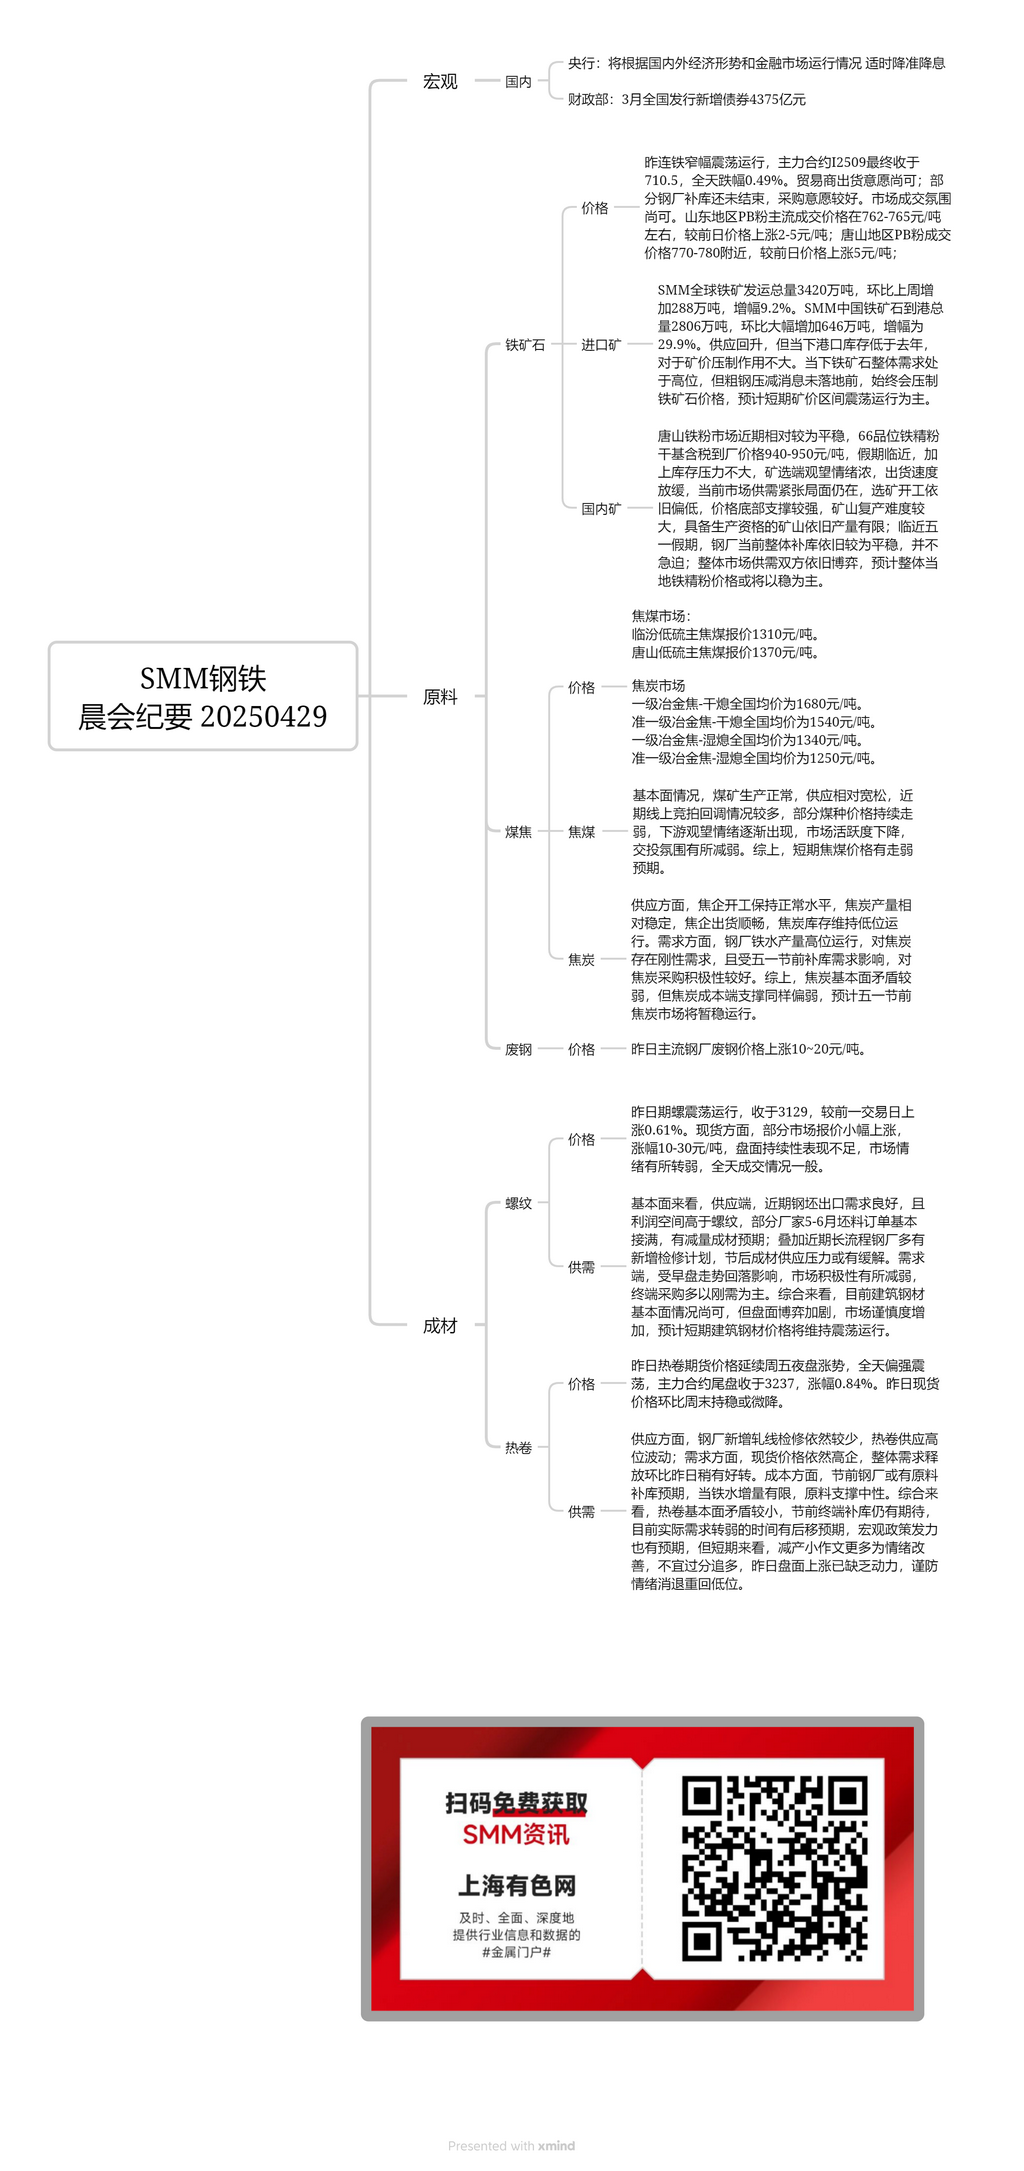
Yesterday, DCE iron ore futures fluctuated rangebound, with the most-traded contract I2509 closing at 710.5, down 0.49% for the day. Traders' willingness to sell was moderate; some steel mills were still in the process of restocking, showing good purchase willingness. The market trading atmosphere was moderate. In Shandong, the mainstream transaction prices of PB fines were around 762-765 yuan/mt, up 2-5 yuan/mt from the previous day. In Tangshan, the transaction prices of PB fines were around 770-780 yuan/mt, up 5 yuan/mt from the previous day. SMM's total global iron ore shipments reached 34.2 million mt, increasing by 2.88 million mt WoW, a 9.2% increase. SMM's total iron ore arrivals in China reached 28.06 million mt, significantly increasing by 6.46 million mt WoW, a 29.9% increase. Supply rebounded, but current port inventory was lower than last year, exerting limited downward pressure on ore prices. Currently, the overall demand for iron ore remained high, but until the news of crude steel production cuts was confirmed, it would continue to suppress iron ore prices. It is expected that ore prices will mainly fluctuate sideways in the short term.
Domestic Ore:
The Tangshan iron ore fines market has been relatively stable recently. The dry-basis, tax-inclusive delivery-to-factory prices of 66% grade iron ore concentrates were 940-950 yuan/mt. As the holiday approaches and inventory pressure is not significant, mines and beneficiation plants have strong wait-and-see sentiment, slowing down the selling speed. The current tight supply and demand situation in the market persists, with beneficiation plants still operating at relatively low levels. Prices have strong support at the bottom, making it difficult for mines to resume production. Mines with production qualifications still have limited output. As the Labour Day holiday approaches, steel mills' overall restocking remains relatively stable and not urgent. The overall supply and demand in the market are still in a tug-of-war, and it is expected that the local iron ore concentrate prices will remain stable.
Coking Coal Market:
The quoted price of low-sulphur coking coal in Linfen is 1,310 yuan/mt. The quoted price of low-sulphur coking coal in Tangshan is 1,370 yuan/mt.
In terms of fundamentals, coal mine production is normal, and supply is relatively loose. There have been many instances of online auction price corrections recently, with prices of some coal types continuing to weaken. Downstream wait-and-see sentiment is gradually emerging, market activity is declining, and trading atmosphere has weakened somewhat. In summary, there is an expectation of weakening coking coal prices in the short term.
Coke Market:
The nationwide average price of premium metallurgical coke (dry quenching) is 1,680 yuan/mt. The nationwide average price of quasi-premium metallurgical coke (dry quenching) is 1,540 yuan/mt. The nationwide average price of premium metallurgical coke (wet quenching) is 1,340 yuan/mt. The nationwide average price of quasi-premium metallurgical coke (wet quenching) is 1,250 yuan/mt.
In terms of supply, coking enterprises' operations remain at normal levels, with relatively stable coke production. Coke shipments from coking enterprises are smooth, and coke inventory remains at low levels. In terms of demand, steel mills' pig iron production is fluctuating at highs, creating rigid demand for coke. Additionally, influenced by restocking demand before the Labour Day holiday, steel mills' enthusiasm for coke purchases is good. In summary, the fundamental imbalance in the coke market is relatively weak, but the cost support for coke is also weak. It is expected that the coke market will remain stable before the Labour Day holiday.
HRC:
Yesterday, HRC futures prices continued the upward trend from Friday's night session, fluctuating up strongly throughout the day. The most-traded contract closed at 3,237, up 0.84%. Yesterday's spot prices held steady or slightly decreased compared to the weekend. In terms of supply, steel mills still have relatively few new rolling line maintenance plans, and HRC supply fluctuates at high levels. In terms of demand, spot prices remain high, and overall demand release has slightly improved compared to yesterday. In terms of costs, steel mills may have expectations of raw material restocking before the holiday, but with limited increases in pig iron production, raw material support is neutral. Overall, the fundamental imbalance in the HRC market is relatively small. There are still expectations for end-user restocking before the holiday. The timing of the actual demand weakening is expected to be postponed, and there are also expectations for macroeconomic policy efforts. However, in the short term, the news of production cuts is more about improving sentiment, and it is not advisable to excessively chase long positions. Yesterday's futures market rally has lacked momentum, and caution should be taken against sentiment fading and prices returning to lows.
Rebar:
Yesterday, rebar futures fluctuated, closing at 3,129, up 0.61% from the previous trading day. In the spot market, some quotes rose slightly, with increases of 10-30 yuan/mt. The futures market's sustained performance was insufficient, and market sentiment weakened somewhat, with general trading conditions throughout the day. From a fundamental perspective, in terms of supply, recent export demand for billets has been good, and profit margins are higher than those for rebar. Some manufacturers have basically filled their billet orders for May-June, expecting a decrease in finished steel output. Additionally, many blast furnace steel mills have recently added new maintenance plans, and the supply pressure for finished steel after the holiday may ease. In terms of demand, influenced by the morning session's price pullback, market enthusiasm has weakened somewhat, with terminal purchases mainly driven by rigid demand. Overall, the current fundamental situation of construction steel is moderate, but the tug-of-war in the futures market has intensified, and market caution has increased. It is expected that construction steel prices will maintain a fluctuating trend in the short term.