The market share of BC technology continues to rise, squeezing TOPCon's market presence.
In April, BC modules accounted for nearly 5% of shipments, showing significant growth compared to March. Their higher cost-effectiveness has made them the preferred choice for Distributed Photovoltaic(DPV) customers. There are relevant data to show that 182mm BC modules delivering around 30W more per panel than TOPCon modules. Currently, TOPCon modules market share has dropped below 82%, showing a declining trend, while other technologies like HJT remain relatively stable. In the future, the competition of enterprises will focus on the DPV market.
Solar module manufacturers ramp up production ahead of the May 31 deadline.
Due to changes in the IRR (Internal Rate of Return) model, module makers are accelerating shipments before May 31st, leading to a notable increase in production from March to April. DPV shipments grew 5% faster than Concentrated Photovoltaic (CPV) shipments. According to SMM estimates, production schedules will see significant adjustments by early to mid-May.
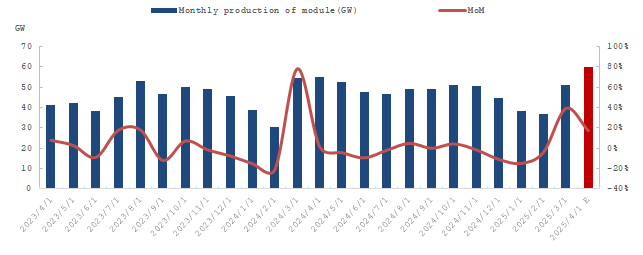
According to SMM statistics, China's photovoltaic module production in March 2025 increased by 3.9% compared to February, with an industry operating rate of approximately 35.91%. P-type module production rose by 7.25%, accounting for 2.7% of total output, while N-type module production increased by 40.2% month-on-month, making up 97.3% of total output. The operating rate for domestic photovoltaic module production in March was about 49.94%.
Looking ahead, will a significant module production increase necessarily lead to a price crash?
The answer is not necessarily. Module manufacturers are ramping up production mainly to meet shipment deadlines before May 31, so short-term price fluctuations may occur. However, long-term trends depend heavily on end demand and order saturation. In early April, domestic wafer and cell prices began to decline, and silicon material order prices also showed signs of softening, indicating a clear cost-reduction trend across the photovoltaic supply chain. Module companies aim to maintain prices as much as possible before the May 31 deadline, but end-user price tolerance remains far below manufacturer quotes. Shipment bottlenecks have forced companies to tighten inventory cycle management. Competition in the residential market remains fierce, while recent signs in the utility-scale market suggest a less optimistic outlook. Divergent strategies have emerged among leading module manufacturers—some have already begun cutting prices to gain market share, while most are holding firm on quotes. Second- and third-tier manufacturers, weighed down by prolonged losses, remain indifferent to future market trends.
SMM data shows that China's photovoltaic module production in April 2025 is expected to grow by around 17.2%, with the industry operating rate rising to 58.55%. By technology type, P-type module output remains flat month-on-month, accounting for 2.3% of total production, while N-type module output declines by 17.7%, making up 97.7% of total production. The domestic operating rate for April is projected at 58.55%. By mid-to-late April, a relatively significant price adjustment is expected across the entire supply chain, starting with modules. So far, industry players are speculating on how much room remains for market demand after electricity market liberalization. Most companies hold a pessimistic outlook on price trends, but a price drop could still trigger another surge in end-user demand.