Copper Cathode Production at Full Capacity Accelerates Copper Concentrate Inventory Depletion [SMM Analysis]

게시됨: Mar 09, 2025 19:06 (GMT+8)
[SMM Analysis: Copper Cathode Production in Full Swing Accelerates Copper Concentrate Inventory Depletion] With the increase in China's copper cathode capacity and the rise in production targets at various smelters, the inventory of copper concentrates, the primary raw material for copper cathode, has seen accelerated depletion. Although copper concentrate port inventory cannot fully represent the supply-demand balance of copper concentrates in China, SMM's data shows that the copper concentrate inventory at nine major ports in China dropped from a peak of 1.31 million mt (ore) at the end of last year to 610,000 mt (ore) by early March 2025. This represents a reduction of more than half within less than one quarter, a remarkable pace. Corroborating this is the record-high monthly production of copper cathode in China, as reported by SMM. Meanwhile, the smelting volume of secondary copper, another raw material for copper cathode, has not seen a corresponding increase. According to SMM, the monthly smelting volume of secondary copper is estimated to be around 160,000-170,000 mt (metal content). Furthermore, the implementation of domestic reverse invoicing policies and concerns over the impact of the China-US trade war on imported secondary copper supply have both exerted pressure on the supply side of secondary copper domestically and overseas.

》View SMM Copper Prices, Data, and Market Analysis

》Subscribe to Access SMM Historical Spot Metal Prices

       At the end of last year, driven by the need for winter stockpiling and market share competition, Chinese smelters significantly accumulated copper concentrate raw material inventories. Specifically, by the end of December 2024, SMM copper concentrate inventories at nine ports reached 1.31 million mt, primarily concentrated at Jinzhou Port (mainly serving smelters in north-east China and Inner Mongolia), Yantai Port (mainly serving smelters in Shandong), Fangchenggang (mainly serving smelters in south-west China), and Nanjing Port (mainly serving smelters along the Yangtze River basin).
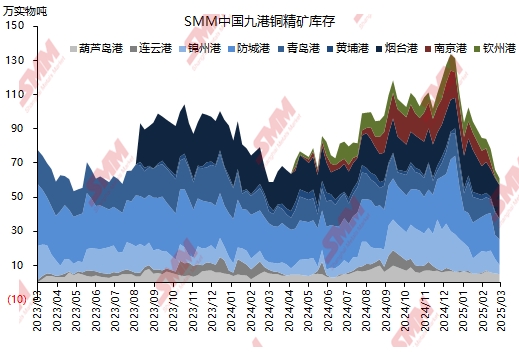
       With the increase in China's copper cathode capacity and the rising production targets of smelters, copper concentrate inventories, the primary raw material for copper cathode, have been rapidly depleted. Although port inventories of copper concentrates cannot fully represent the supply-demand balance of copper concentrates in China, SMM's nine-port copper concentrate inventories dropped from the peak of 1.31 million mt at the end of last year to 610,000 mt by early March 2025. This represents a reduction of more than half within less than a quarter, a remarkably fast pace. Supporting this trend is the record-high monthly production of copper cathode in China, as reported by SMM. Meanwhile, the smelting volume of secondary copper, another raw material for copper cathode, has not seen a corresponding increase. According to SMM estimates, the monthly smelting volume of secondary copper is around 160,000-170,000 mt in metal content. Additionally, the implementation of domestic reverse invoicing policies and concerns over the impact of the China-US trade war on imported secondary copper supply have exerted pressure on both domestic and overseas secondary copper supply chains.
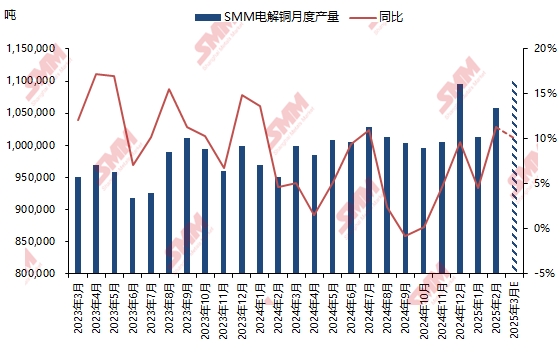
       SMM expects that as China's monthly copper cathode production continues to rise, the total contribution of secondary copper smelting to copper cathode production may continue to decline, with its contribution ratio decreasing. In contrast, the contribution level of copper concentrate raw materials to copper cathode production is expected to increase, implying a continued reduction in copper concentrate port inventories.


》Click to Access the SMM Copper Industry Chain Database
 

데이터 출처 설명: 공개 정보를 제외한 모든 데이터는 SMM이 공개 정보, 시장 커뮤니케이션 및 SMM 내부 데이터베이스 모델을 기반으로 가공한 것입니다. 본 자료는 참고용이며 의사결정 권고를 구성하지 않습니다.

문의 사항이 있거나 자세한 정보를 원하시면 아래로 연락해 주시기 바랍니다: lemonzhao@smm.cn
리서치 보고서 열람 방법에 대한 자세한 내용은 아래로 문의하시기 바랍니다:service.en@smm.cn
관련 뉴스
구리 가격이 소폭 조정을 보였고, 인도월 간 백워데이션이 축소된 후 현물 프리미엄이 소폭 상승했다 [SMM 상하이 현물 구리]
41분 전
구리 가격이 소폭 조정을 보였고, 인도월 간 백워데이션이 축소된 후 현물 프리미엄이 소폭 상승했다 [SMM 상하이 현물 구리]
더 보기
구리 가격이 소폭 조정을 보였고, 인도월 간 백워데이션이 축소된 후 현물 프리미엄이 소폭 상승했다 [SMM 상하이 현물 구리]
[SMM 상하이 현물 구리] 내일을 전망하면, 현재 상하이 현물 시장의 공급과 수요가 모두 약세인 구도가 지속되고 있다. 공급 측면에서는 시장 내 유통 물량이 여전히 부족하며, 일부 공급업체는 보유 재고가 한정적이어서 저가 매도 의사가 낮아 현물 프리미엄에 일정 부분 지지력을 제공하고 있다. 수요 측면에서는 SHFE 구리 가격이 장중 뚜렷하게 하락했음에도 불구하고, 하류 가공업체들의 구매 적극성은 아직 뚜렷한 개선을 보이지 않고 있으며, 시장에는 관망 심리가 강하게 자리 잡고 있다. 일부 구매자들은 톤당 1,100위안 수준의 프리미엄에 입찰을 집중하고 있어 공급업체 호가와 일정한 괴리가 발생하고 있으며, 실제 거래는 여전히 강성 수요 중심으로 이루어지고 있다. 한편, 장중 선물 계약 간 백워데이션 스프레드가 크게 변동하며 한때 톤당 1,000위안 이상으로 확대되었다. 높은 스프레드와 높은 현물 프리미엄이 겹치면서 하류 구매자들의 조달 비용을 계속 끌어올려 시장 거래를 더욱 위축시키고 있다. 종합하면, 유통 물량 부족이 여전히 현물 프리미엄을 지지하고 있으나, 약한 수요와 높은 백워데이션 구조가 프리미엄의 추가 상승을 제한하고 있다. 상하이 현물 구리 프리미엄은 내일도 높은 수준을 유지할 것으로 예상된다.
41분 전
초반 거래 활동은 부진했으며, 수입 동 현물 프리미엄은 보합세를 유지했다 [SMM 양산 현물 동]
49분 전
초반 거래 활동은 부진했으며, 수입 동 현물 프리미엄은 보합세를 유지했다 [SMM 양산 현물 동]
더 보기
초반 거래 활동은 부진했으며, 수입 동 현물 프리미엄은 보합세를 유지했다 [SMM 양산 현물 동]
49분 전
높은 프리미엄이 수요를 억제하며, 화북 지역 현물 거래 부진 [SMM 화북 현물 구리]
2시간 전
높은 프리미엄이 수요를 억제하며, 화북 지역 현물 거래 부진 [SMM 화북 현물 구리]
더 보기
높은 프리미엄이 수요를 억제하며, 화북 지역 현물 거래 부진 [SMM 화북 현물 구리]
오늘 중국 화북 지역에서 1호 전기동 현물은 근월물 대비 프리미엄 850~960위안/톤에 호가되었으며, 평균 프리미엄은 905위안/톤으로 전 거래일 대비 30위안 상승했다. 평균 거래 가격은 109,505위안/톤으로 전 거래일 대비 135위안 하락했다.
2시간 전