LME & COMEX Copper Price Spread Hits Historical High Again: What's Driving It? [SMM Analysis]

게시됨: Jan 10, 2025 14:02 (GMT+8)
출처: SMM
[SMM Analysis]: In May 2024, due to ultra-low COMEX copper inventories, a historically rare short squeeze occurred in the COMEX copper market. A large influx of funds went long in COMEX copper futures, creating a squeeze on arbitrage funds and hedging enterprises already in the market. The intraday price spread between LME and COMEX copper once exceeded $1,000/mt, with the cross-market price spread widening to extreme levels. Traders began transporting copper to US warehouses to profit from the ultra-high price spread and alleviate the pressure from the short squeeze, leading to a gradual rebound in COMEX copper inventories. By January 9, 2025, the intraday premium of COMEX copper over LME copper exceeded $600/mt, nearing historical highs. Meanwhile, COMEX inventories were at historical highs, and the fundamentals could hardly support such a large price spread. What is the reason behind this?

In May 2024, due to ultra-low COMEX copper inventories, a historically rare short squeeze occurred in the COMEX copper market. A large influx of funds went long in COMEX copper futures, creating a squeeze on arbitrage funds and hedging enterprises already in the market. The intraday price spread between LME and COMEX copper once exceeded $1,000/mt, with the cross-market price spread widening to extreme levels. Traders began transporting copper to US warehouses to profit from the ultra-high price spread and alleviate the pressure from the short squeeze, leading to a gradual rebound in COMEX copper inventories. By January 9, 2025, the intraday premium of COMEX copper over LME copper exceeded $600/mt, nearing historical highs. Meanwhile, COMEX inventories were at historical highs, and the fundamentals could hardly support such a large price spread. What is the reason behind this?

The Washington Post reported on January 6, 2025, that aides to US President-elect Trump are exploring a tariff plan applicable to "all countries" for critical imported goods. This contradicts Trump's statements during his presidential campaign. Notably, on November 25, 2024, after his election victory, Trump stated that on his first day in office, he would impose an additional 10% tariff on all imports from China. Regarding the January 6, 2025, report by The Washington Post, Trump dismissed the news in a post, calling it "another fake news" and asserting that his tariff policy would not be scaled back.
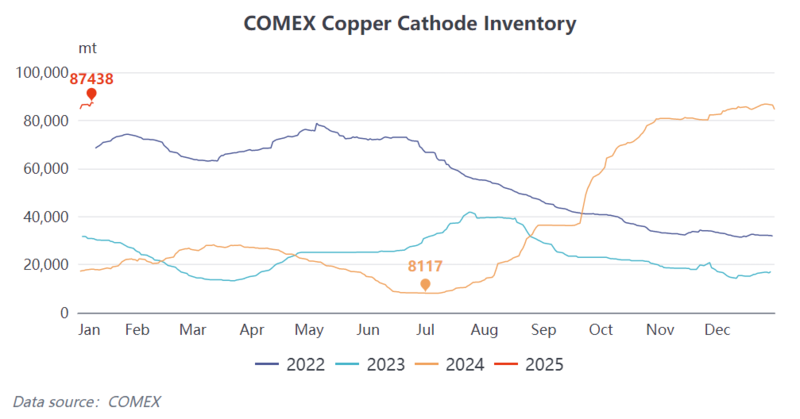
Before Trump's inauguration on January 20, under the expectation of a "universal" tariff of 10% or 20%, or even higher, financial markets were filled with uncertainty about the potential impact of his trade policies. COMEX became the preferred choice for some speculative capital in US commodities, leading to a new round of surges in the price spread between the two markets. This may result in some copper traders engaging in cross-market arbitrage by buying LME copper futures contracts while selling COMEX futures, which would cause the price spread to narrow. It could also lead to a widening of the LME & SHFE copper price spread, an increase in domestic import losses, and even the opening of the export window.
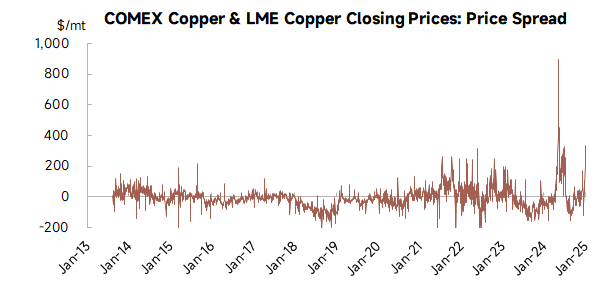
According to SMM, some traders will lock in price spread profits by shipping copper from South America to North America. However, some traders are concerned about the potential extreme widening of the price spread between the two markets due to the fermenting expectations of new policies such as tariffs, which could lead to losses. In the Chinese market, the availability of deliverable copper sources for COMEX is relatively small. Considering factors such as transportation distance, time, and capital costs, the operational space is limited. As cross-market arbitrage positions enter the market, the price spread between the two markets is expected to gradually narrow. In the future, COMEX copper warehouse inventories may continue to grow, but based on US copper consumption expectations, this is not expected to exert pressure on its fundamentals.


데이터 출처 설명: 공개 정보를 제외한 모든 데이터는 SMM이 공개 정보, 시장 커뮤니케이션 및 SMM 내부 데이터베이스 모델을 기반으로 가공한 것입니다. 본 자료는 참고용이며 의사결정 권고를 구성하지 않습니다.

문의 사항이 있거나 자세한 정보를 원하시면 아래로 연락해 주시기 바랍니다: lemonzhao@smm.cn
리서치 보고서 열람 방법에 대한 자세한 내용은 아래로 문의하시기 바랍니다:service.en@smm.cn
관련 뉴스
KGHM과 South32, 시에라 고르다 확장에 7억 2,500만 달러 투자…구리 생산능력 26% 증대
13시간 전
KGHM과 South32, 시에라 고르다 확장에 7억 2,500만 달러 투자…구리 생산능력 26% 증대
더 보기
KGHM과 South32, 시에라 고르다 확장에 7억 2,500만 달러 투자…구리 생산능력 26% 증대
KGHM과 South32가 칠레 아타카마 지역의 시에라 고르다 구리-몰리브덴 광산에서 네 번째 분쇄 라인 건설에 착공했다. 7억 2,500만 달러 규모의 이번 확장 공사는 2027년 1월부터 3년간 진행되며, 2029년 말 완공 후 2030년 하반기에 전체 생산량에 도달할 예정이다. 광석 처리 능력은 하루 13만 1,000톤에서 16만 5,000톤으로 26% 증가한다. 연간 구리 생산량은 2025년 16만 5,000톤에서 19만 5,000톤으로 늘어날 전망이며, 부산물로 몰리브덴 6,000톤, 금 5만 8,000온스, 은 170만 온스가 생산된다. 이 프로젝트는 900개 이상의 직접 일자리를 창출하며, 운영 현금 흐름과 부채로 자금을 조달한다. 단위 운영 비용은 약 10% 감소할 것으로 예상된다.
13시간 전
에메리타, 이베리안 벨트 웨스트 PFS 최종 검토 연장, 수 주 내 발표 예정
14시간 전
에메리타, 이베리안 벨트 웨스트 PFS 최종 검토 연장, 수 주 내 발표 예정
더 보기
에메리타, 이베리안 벨트 웨스트 PFS 최종 검토 연장, 수 주 내 발표 예정
Emerita Resources는 스페인 소재 이베리안 벨트 웨스트 다금속 프로젝트의 예비 타당성 조사(PFS)에 대한 업데이트를 제공하며, 해당 조사가 상당히 진행되었으나 최종 기술 검토가 남아 있다고 밝혔다. 회사 측은 발표 전 추가적인 기술 및 품질 보증 감독을 포함하도록 검토 절차를 확대했다고 설명했다. 이에 따라 Emerita는 PFS가 기존에 제시된 시기가 아닌 향후 수주 내에 발표될 것으로 예상하고 있다. 이베리안 벨트 웨스트는 구리, 아연, 납, 금, 은 광화대를 보유하고 있으며 Emerita가 스페인에서 보유한 주요 개발 단계 자산 중 하나다. PFS는 제안된 광산 계획, 처리 구성, 자본 요건, 운영 비용 및 프로젝트 경제성에 대한 업데이트된 세부 내용을 제공할 것으로 기대된다. Emerita는 추가 검토 작업이 조사 확정 전에 해당 조사에 기여하는 기술 분야 전반의 일관성과 완전성을 보장하기 위한 것이라고 밝혔다. 회사는 수정된 구체적인 발표일을 공지하지 않았으며, 이번 최신 업데이트에서 새로운 생산량, 자본 또는 경제성 수치도 공개되지 않았다. 검토 기간 연장으로 이베리안 벨트 웨스트의 다음 주요 기술적 이정표가 지연되지만, 회사는 PFS가 완료 단계에 가까워지고 있다고 계속해서 밝히고 있다. 구리 시장의 경우, 이번 조사의 중요성은 궁극적으로 공개될 생산 프로필과 프로젝트 경제성, 특히 프로젝트의 기타 유가 금속 대비 구리의 기여도에 달려 있다. 따라서 PFS 발표 시기와 최종 조사가 프로젝트 개발 전망을 실질적으로 변화시키는지 여부에 관심이 집중될 것이다.
14시간 전
카스카디아, 카맥스 구리-금 프로젝트에서 75.55m 구간 1.19% Cu 교차
14시간 전
카스카디아, 카맥스 구리-금 프로젝트에서 75.55m 구간 1.19% Cu 교차
더 보기
카스카디아, 카맥스 구리-금 프로젝트에서 75.55m 구간 1.19% Cu 교차
Cascadia Minerals는 캐나다 유콘주 Carmacks 구리-금 프로젝트의 2026년 탐사 프로그램에서 추가 시추 결과를 보고했으며, 새로운 외곽 시추를 통해 Zone 2000S의 광화대가 기존 광물자원 경계를 넘어 확장되고 있음을 확인했다. 시추공 CD-26-058에서는 75.55m 구간에서 구리 1.19%, 금 0.97g/t, 은 10.4g/t, 몰리브데넘 335ppm을 기록했으며, 이는 구리 등가 2.18%에 해당한다. 이 구간에는 48.66m 구간에서 구리 1.61%, 금 1.39g/t, 은 15.1g/t, 몰리브데넘 475ppm을 기록한 고품위 구간이 포함되며, 이는 구리 등가 3.03%에 해당한다. 같은 시추공 내 14.50m의 고품위 구간에서는 구리 2.30%, 금 2.68g/t, 은 29.5g/t, 몰리브데넘 1,015ppm을 기록했으며, 이는 구리 등가 5.08%에 해당한다. 두 번째 시추공 CD-26-059에서는 93.99m 구간에서 구리 0.96%, 금 0.70g/t, 은 4.6g/t, 몰리브데넘 919ppm을 기록했으며, 이는 구리 등가 1.94%에 해당한다. 이 구간에는 63.97m 구간에서 구리 1.26%, 금 0.96g/t, 은 6.3g/t, 몰리브데넘 1,049ppm을 기록한 구간이 포함되며, 이는 구리 등가 2.52%에 해당한다. Cascadia는 이번 결과가 현재 광물자원 범위를 넘어 Zone 2000S의 광화대를 지속적으로 확장하고 있으며, 연장부의 고품위 특성을 부각시킨다고 밝혔다. 보고된 시추 구간은 시추 두께이며, 실제 폭은 약 60~70%로 추정된다. 이번 외곽 시추 결과는 Zone 2000S의 구리-금 광화대가 현재 Carmacks 광물자원 경계를 넘어 연장되고 있음을 보여준다. 넓은 광화 구간과 고품위 내부 구간은 추가 시추를 통해 연속성이 확인될 경우 향후 자원 확장을 뒷받침할 수 있다. 다만, 새로운 교차 구간은 아직 갱신된 광물자원 추정치에 반영되지 않았으므로 프로젝트 규모와 광산 계획에 미치는 최종 영향은 아직 결정되지 않았다.
14시간 전

