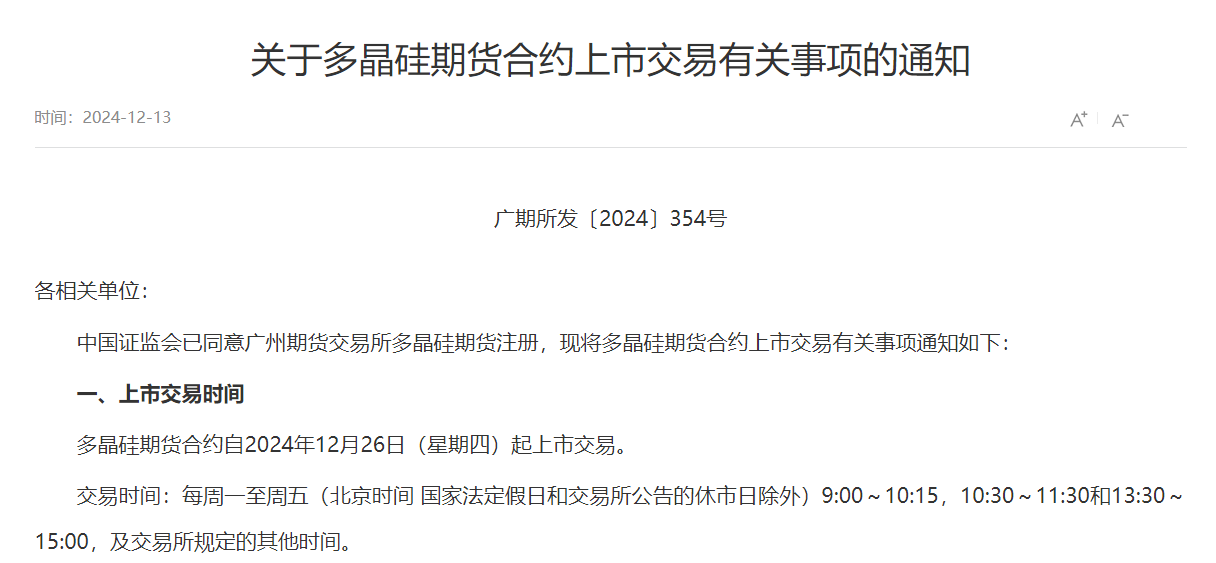
SMM, December 19: On December 13, the Guangzhou Futures Exchange announced that polysilicon futures contracts will be listed for trading starting Thursday, December 26, 2024. Trading hours will be Monday to Friday (excluding national public holidays and exchange-announced non-trading days) from 9:00 to 10:15, 10:30 to 11:30, and 13:30 to 15:00 Beijing time, as well as other times specified by the exchange. Polysilicon options contracts will be listed for trading starting Friday, December 27, 2024, with trading hours consistent with those of polysilicon futures contracts.
As the third new energy futures product listed on the Guangzhou Futures Exchange after silicon metal and lithium carbonate, polysilicon futures have garnered widespread market attention since being proposed by the exchange. Over the past three years, polysilicon prices have experienced significant volatility, similar to the earlier trends in lithium carbonate, with sharp price fluctuations causing mixed reactions among industry chain enterprises.
The Guangzhou Futures Exchange stated that while the polysilicon industry has been developing rapidly, it faces numerous challenges such as a lack of forward price signals and risk management tools, periodic supply-demand mismatches, disordered market competition, and severe price volatility. The listing of polysilicon futures and options is urgently needed to establish objective, continuous, and authoritative price signals and provide risk management tools, thereby supporting the stable development of the industry. Against this backdrop, the launch of polysilicon futures and options is "timely."
Polysilicon Prices Have Been Highly Volatile in Recent Years, Leading to Significant Declines in Silicon Enterprises' Performance
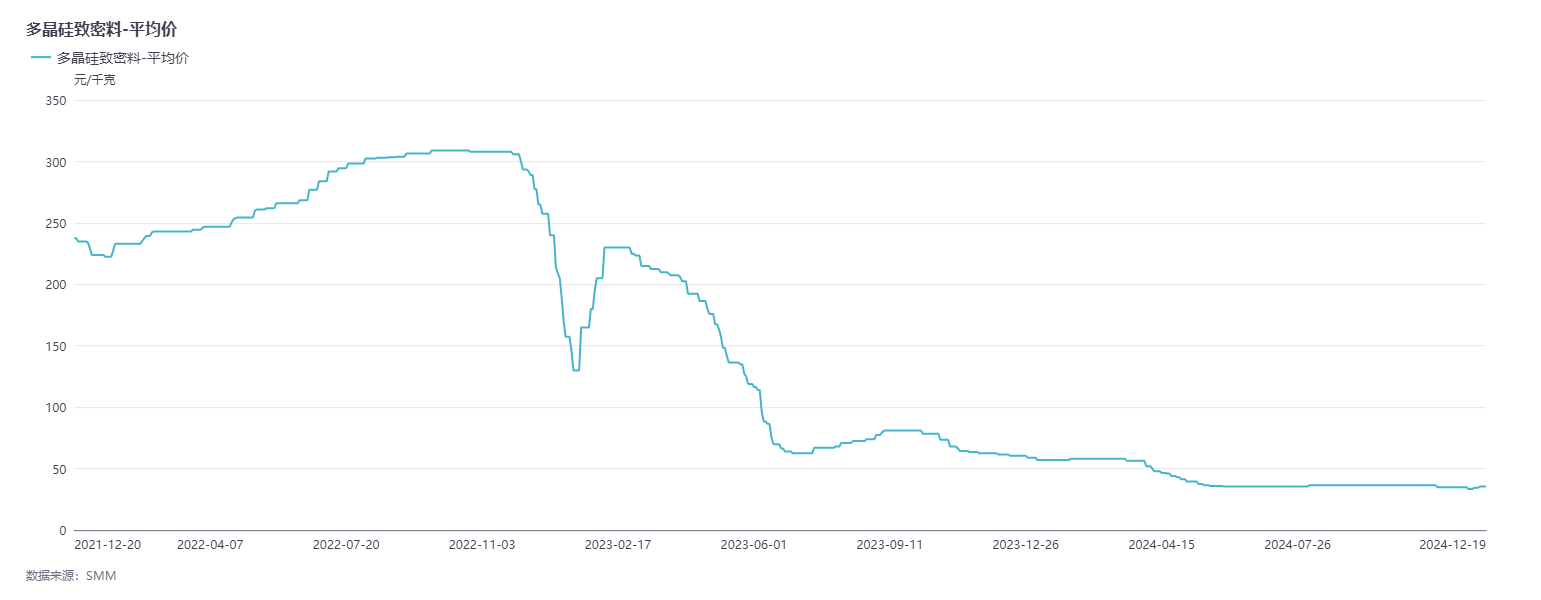
The significant volatility in polysilicon prices can be partially observed from SMM's polysilicon price quotes. Taking dense polysilicon as an example, SMM's historical data shows that since 2022, polysilicon prices have been driven upward due to supply-demand imbalances caused by capacity mismatches. Prices peaked at 309 yuan/kg in 2022. However, near the end of 2022, with the concentrated release of new polysilicon capacity in China, the supply-demand relationship in the polysilicon market reversed. In December 2022, several polysilicon enterprises began experiencing inventory buildup. Coupled with the continuous decline in downstream wafer prices and the collapse of market sentiment, polysilicon prices faced a "Waterloo."
》Click here for SMM PV product spot prices
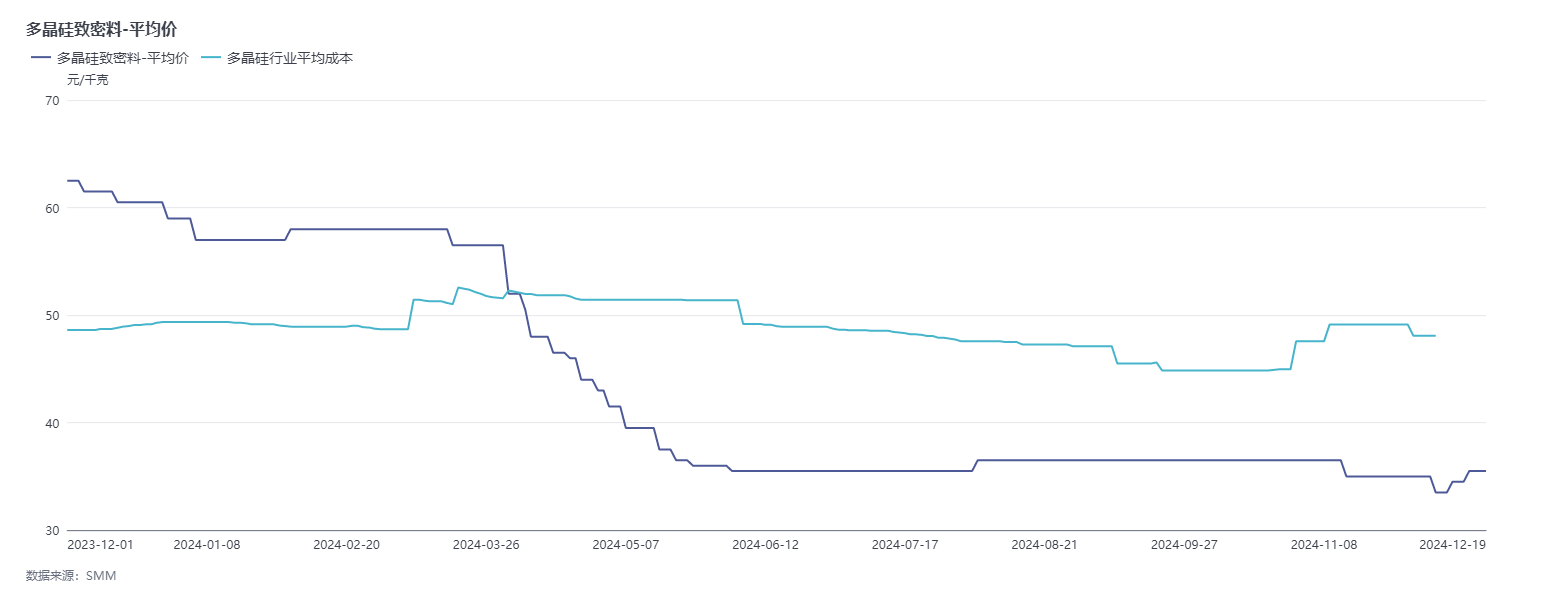
In 2023, although polysilicon prices rebounded quickly in Q1 under the "joint efforts to stand firm on quotes" by top-tier enterprises, the oversupply situation in the market remained unchanged. After a brief "resurgence," polysilicon prices entered a downward trajectory again and have since remained in a low-level fluctuation. During this period, the spot price of dense polysilicon fell to a three-year low of 33.5 yuan/kg on December 6, 2024, a sharp decline of 89.16% from its previous peak of 309 yuan/kg.
As polysilicon prices continued to decline, spot prices fell below the average cost line of the polysilicon industry as early as April 2024, increasing production pressure on polysilicon-related enterprises.
Consequently, many leading domestic enterprises have seen their performance significantly impacted by the rapid pullback in polysilicon prices since 2023. For example, top-tier polysilicon enterprise Daqo New Energy reported a net loss attributable to shareholders of publicly listed firms of 1.099 billion yuan in the first three quarters of 2024, compared to a profit of 5.115 billion yuan in the same period of 2023, representing a YoY decline of 121.49%. Tongwei Co., a dual leader in polysilicon and solar cells in China, reported a net loss attributable to shareholders of publicly listed firms of 3.973 billion yuan in the first three quarters of 2024, a decrease of 20.275 billion yuan compared to the same period last year, representing a YoY decline of 124.37%. GCL Technology reported a net loss attributable to shareholders of publicly listed firms of approximately 2.971 billion yuan in the first three quarters of 2024, while its net profit for the entire year of 2023 was 2.51 billion yuan.
Under these circumstances, the launch of polysilicon futures can help enterprises hedge against market price risks, lock in raw material costs or sales profits, and smooth out profit volatility, thereby providing a competitive advantage over companies not engaged in hedging.
Industry Chain Enterprises Hold Mixed Views on Polysilicon Futures; Recent Market Sentiment Improves
Unlike the rush by many industry chain enterprises to announce plans for hedging with lithium carbonate futures before their launch, polysilicon enterprises have largely adopted a wait-and-see attitude as the listing of polysilicon futures approaches. Wang Yanqing, a senior analyst at China Securities Futures, stated in an interview with Shell Finance that both upstream and downstream polysilicon players are currently cautious about participating in the futures market. Due to the periodic supply-demand pattern, upstream players show slightly higher enthusiasm than downstream players, potentially leading to a sequence where the futures market first attracts upstream participants with high prices, followed by downstream participants with lower prices.
Currently, Jinko Solar appears to be the first company to explicitly state in its announcement that it will participate in polysilicon futures trading. On December 11, the company announced that its engagement in commodity futures hedging aims to mitigate the impact of raw material price fluctuations on production and operational costs. By leveraging the hedging function of the futures market, the company seeks to effectively control market risks without engaging in speculative trading for profit, thereby enhancing its overall risk resistance and financial stability. The trading products include raw materials related to the production and operations of the company and its subsidiaries, such as copper, aluminum, silver, tin, and polysilicon.
Although some enterprises have shown limited enthusiasm for the listing of polysilicon futures, the Guangzhou Futures Exchange emphasized that the listing of polysilicon futures plays a crucial role in the stable and healthy development of the new energy industry and in accelerating the formation of new productive forces. First, it helps reduce costs and improve efficiency in the PV industry, ensures supply chain security, guides and regulates the rational layout of various segments of the industry chain, and accelerates the formation of "new productive forces" in the PV sector. Second, it promotes the integration of industry and finance, synergizes with silicon metal futures, supports the national strategy for developing western China, and contributes to the economic development and stability of western regions. Third, it facilitates the internationalization of China's PV industry, supports the "Belt and Road" energy initiative, and enhances China's pricing power in international trade.
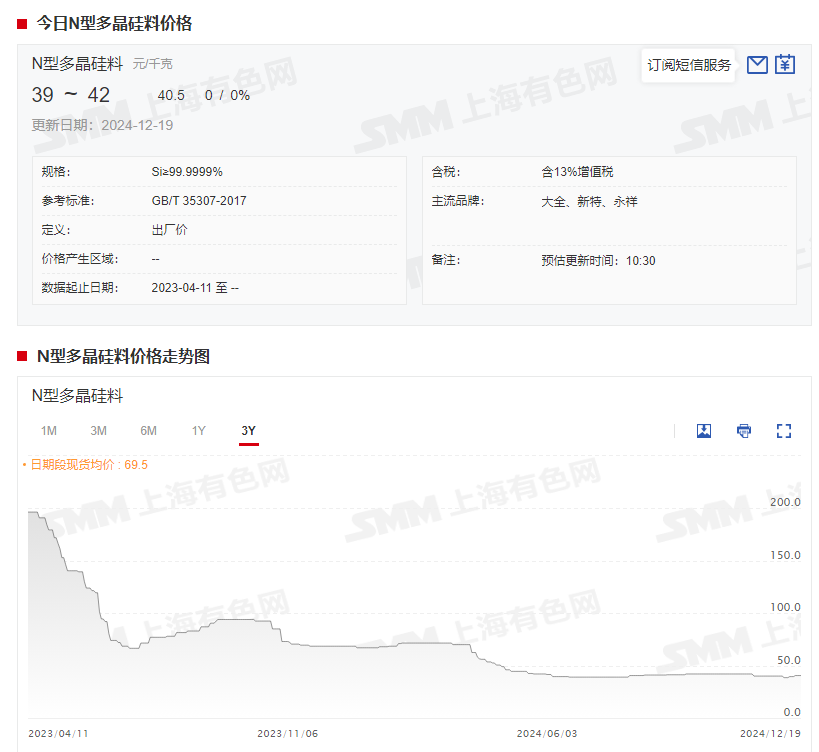
Notably, since December 6, when the China Photovoltaic Industry Association announced that multiple PV industry chain enterprises had formally signed a self-discipline agreement at a meeting, subsequent signatories have begun capacity control measures, leading to a partial recovery in market confidence. According to SMM spot price data, polysilicon prices, which had been stagnant at the bottom for a long time, began to recover in early December, with two consecutive weeks of increases. At the end of November, polysilicon transaction prices were around 38 yuan/kg. As of now, some delivery prices have approached 40 yuan/kg, with mainstream producers quoting 42 yuan/kg during the order signing period.
Regarding the reasons for the recent increase in polysilicon prices, SMM understands that the primary driver has been the proactive efforts of mainstream enterprises to stand firm on quotes. The industry self-discipline achieved through the association's meeting has led to a partial recovery in market confidence. Additionally, the upcoming launch of polysilicon futures on December 26 provides polysilicon manufacturers with more options. Combined with other factors, such as rising downstream prices, polysilicon prices have increased.
For the future trend of polysilicon prices, SMM understands that the current sentiment among polysilicon manufacturers to stand firm on quotes is relatively strong, with some high-quality silicon materials even quoted at 44-45 yuan/kg. Coupled with the potential for increased wafer production, the likelihood of higher polysilicon order signing prices in the near term is significant, with the market showing high acceptance of the 42 yuan/kg price. However, it is worth noting that the rise in polysilicon prices still lacks support from supply-demand fundamentals. In January and February, traditionally an off-season, weak component demand may continue to limit price support. 》Click here for more details