Copper prices have been rising since March 13 following a series of news about "possible production cuts by Chinese smelters." During this period, geopolitical factors, the US dollar trend, favourable macro front in China, and the COMEX short squeeze event pushed copper prices to a historical high in May. As bullish funds retreated from high levels and downstream operations suffered under high copper prices, leading to negative feedback on consumption, copper prices began to decline gradually from June. In early August, the market briefly traded on recession logic, with LME copper falling to $8,714/mt, then rebounding slightly to $9,200/mt. From June to August, during the continuous decline in copper prices, SMM copper cathode social inventory showed a significant destocking trend, but global visible inventory continued to build up.
Please note that in this article, the visible inventories of the three major global exchanges are SHFE + LME + COMEX; the total global researchable inventory (hereinafter referred to as the total global inventory) is SMM China's domestic and bonded copper cathode social inventory + SMM China's smelter copper cathode inventory + SMM China's consumer copper cathode inventory + LME + COMEX.
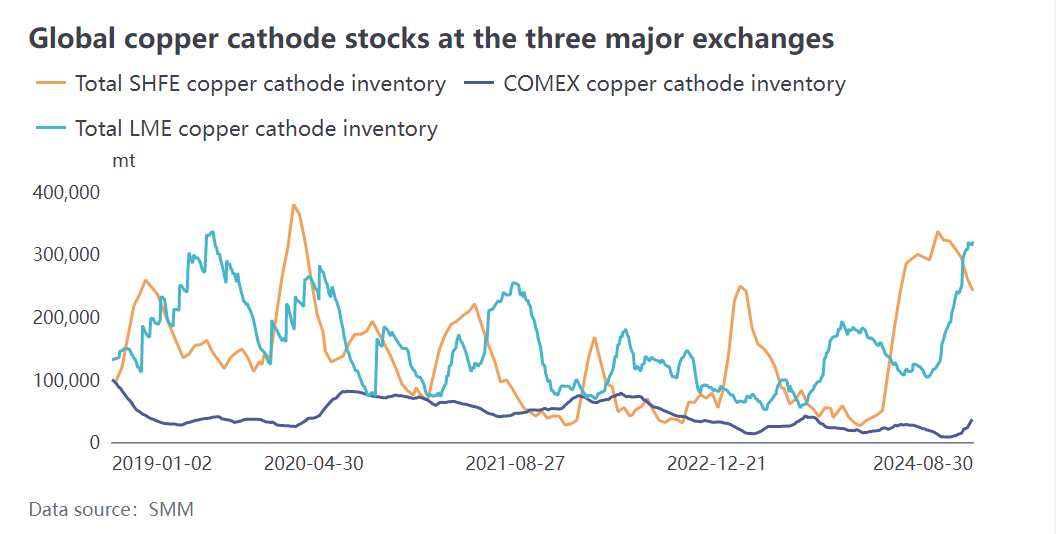
First, let's observe the trends in visible inventories at the world's three major exchanges. Since returning from the Chinese New Year, SHFE inventories have continued to rise as smelters delivered most of their supplies to the delivery inventory, leading to an increase in stocks. During this period, LME and COMEX inventories remained at historically low levels. Subsequently, copper prices have been rising continuously since March 13, and the SHFE copper futures structure has turned into a contango structure, with spot copper showing a significant discount. The high copper prices have reduced downstream purchasing demand, and holders have maintained delivery actions from the 2403 contract to the 2406 contract, making it difficult for SHFE inventories to decrease.

However, after April, copper cathode saw export opportunities, and smelters actively prepared for export actions. According to customs data, China exported 326,100 mt of copper cathode from April to July, with the cumulative value reaching a historical high. Subsequently, LME copper inventories began to increase continuously, with the most significant growth in Asia, undoubtedly due to the high proportion of exports from China, while inventories in Europe and the US did not increase but rather decreased.
According to SMM data, the visible inventories of the three major exchanges were 330,155 mt on February 23 and 597,300 mt on July 26, an increase of 221,416 mt over five months. (Since global copper stocks data is only updated until the end of July, the comparison here is made up to the end of July. As of August 23, the total visible inventories of the three major exchanges globally were 597,300 mt, continuing to maintain stockpiling.)
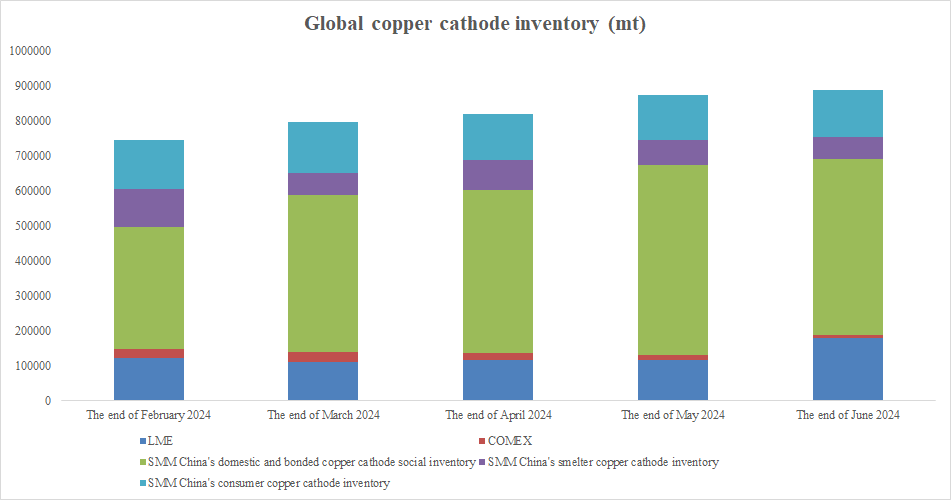
Let's look at the SMM's research on global inventory data. SMM's domestic and bonded copper cathode stocks in China declined due to effects such as exports, downstream restocking after copper prices fell, and substitution between refined and scrap copper. Additionally, as the import window opened, bonded area stocks gradually flowed into domestic trade for digestion, thus showing a decline. The in-plant inventory of Chinese smelters also declined after the slowdown in exports and the expectation of production cuts. According to SMM data, global copper cathode stocks at the end of July were 891,939 mt, an increase of 145,514 mt from 746,425 mt at the end of February. The increase was smaller than the increase in inventories at the world's three major exchanges, indicating that the destocking in China's social inventory was due to consumption and supply, not just export transfers.
In summary, the global copper cathode inventory buildup for 2024 is basically confirmed. When observing inventory changes, it is necessary to break down and analyze each indicator in detail. Currently, the destocking trend in China continues, with signs of convergence in the domestic contango structure and occasional openings of the import window. With market expectations for the September-October peak season and supply disruptions, it is expected that China's inventory will continue to decrease, and the global inventory buildup will also slow down.