The Heartbeat of the Lithium Battery Market: Insights into Lithium Hydroxide Price Fluctuations in H1 2024
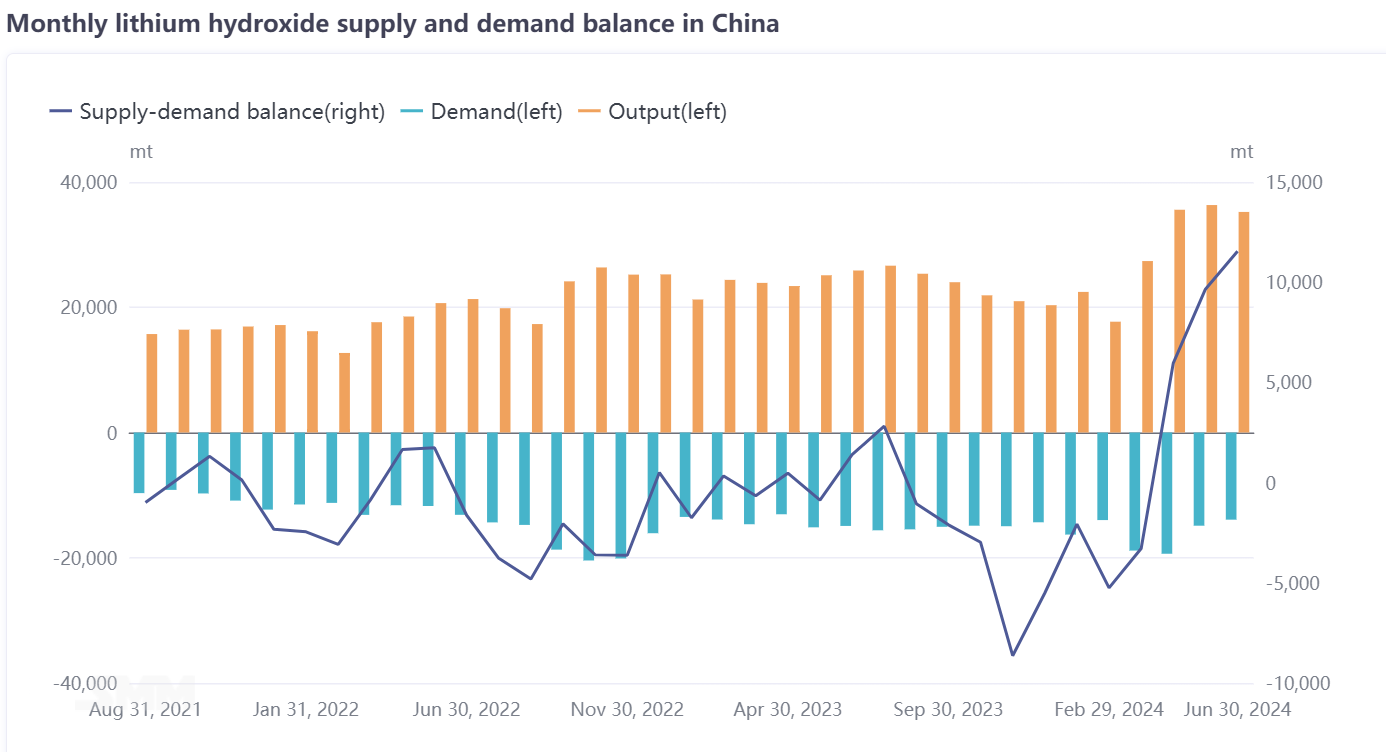
According to SMM analysis, in H1 2024, domestic lithium hydroxide total output was 174,600 mt, up 2.4% YoY. Demand side, in H1 2024, domestic lithium hydroxide total demand was 97,000 mt, up 14% YoY; net exports were 65,000 mt, up 11.5% YoY. Price-wise, in H1, the price of battery-grade lithium hydroxide rose from 84,000 yuan/mt at the beginning of the year to 100,000 yuan/mt in early May, then quickly fell back to 83,000 yuan/mt in just over a month. In H1 2024, the lithium hydroxide market experienced a series of dynamic changes that profoundly impacted the entire lithium battery industry chain.
From the supply side:
(1) Domestic Total Supply
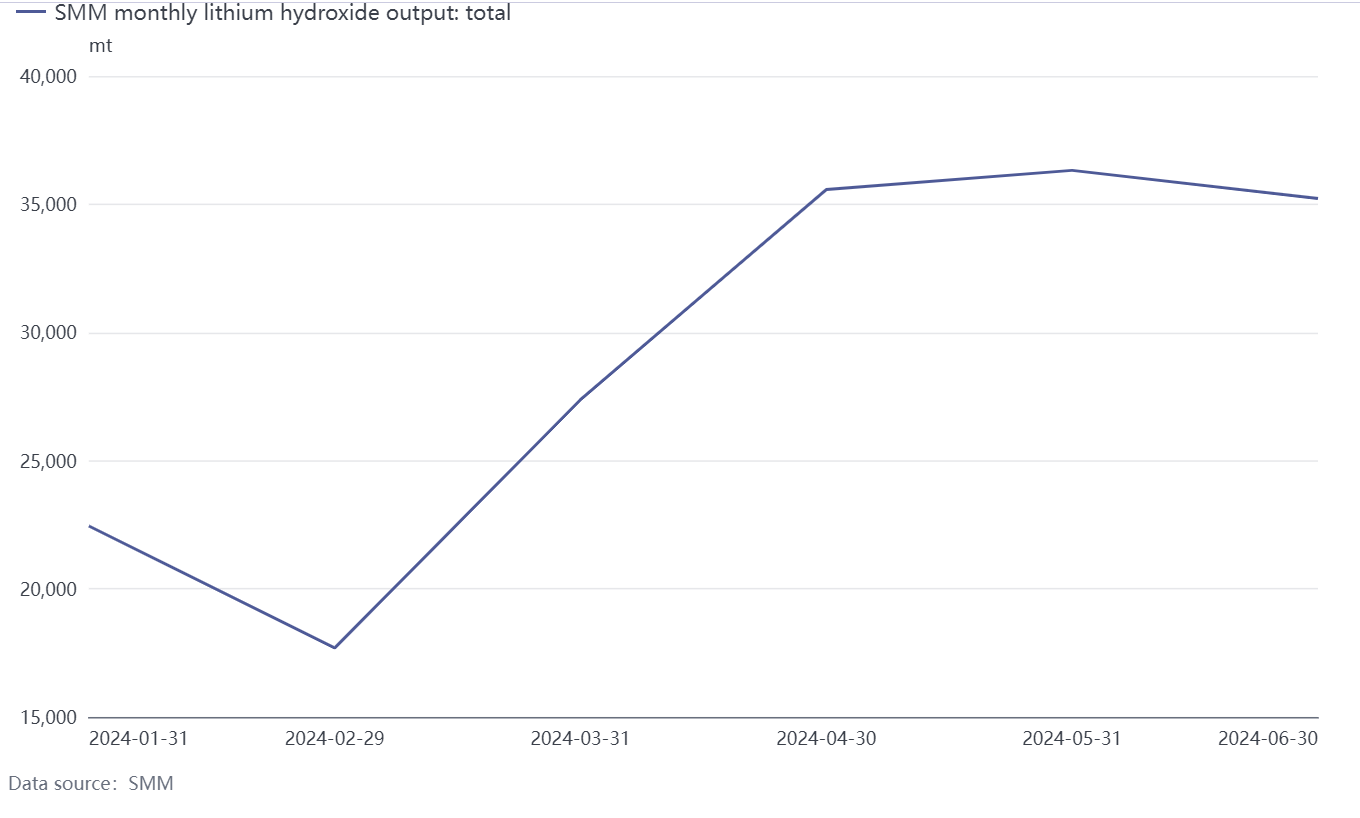
From the perspective of domestic lithium hydroxide supply, the total output of domestic lithium hydroxide in H1 2024 was 174,600 mt, up 2.4% YoY. At the beginning of the year, as lithium hydroxide prices further declined, most producers faced cost pressures and had varying degrees of production cuts and maintenance plans during the CNY, leading to a contraction in smelter scheduled production. Compared to January and February 2023, production saw a significant decline. From the end of February, smelters resumed production after the holiday, and inventory levels were at a temporary low. Additionally, the capacity of some producers that had been put into operation earlier gradually ramped up, resulting in a noticeable increase in lithium hydroxide production. From March to June, the monthly output of lithium hydroxide producers gradually increased, peaking in June. The entire market gradually entered a surplus situation.
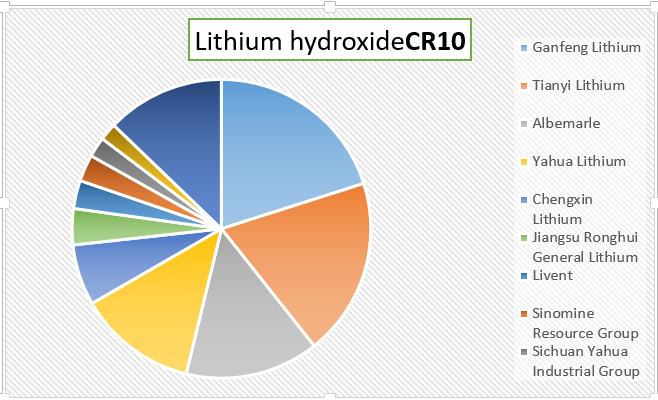
From the H1 lithium hydroxide output of the top 10 producers, the concentration of lithium hydroxide production is relatively high. The top 10 producers in H1 accounted for about 90% of the national total output. Specifically, the top five producers are Ganfeng Lithium, Tianyi Lithium, Albemarle, Yahua Lithium, and Chengxin Lithium, accounting for about 70% of the total output.
From the demand side:
Domestic total demand
In H1 2024, domestic demand for lithium hydroxide experienced an initial increase followed by a decrease. At the beginning of the year, domestic ternary cathode material plants with medium to high nickel content advanced their scheduled production orders, leading to a short-term rebound in demand for lithium hydroxide. Compared to January and February 2023, demand for lithium hydroxide in the same period of 2024 increased by 9% YoY, showing a significant increase from the previous year. In March and April, as domestic new energy vehicles were continuously launched, price cuts and competition among car manufacturers stimulated an unexpected increase in car demand, driving up orders for medium to high nickel cathode materials downstream. However, the price cuts led to an early consumption of future demand. From late April to June, the consumption of high-nickel ternary vehicles did not meet expectations, and cathode material plants increased their customer-supplied lithium hydroxide, actively executing destocking strategies to digest customer-supplied raw materials. At this time, demand for lithium hydroxide began to weaken. According to the current survey, orders for high-nickel ternary plants improved in July and August, but H2 demand for lithium hydroxide will still depend on the sales growth of medium to high nickel new energy vehicles.
From the perspective of domestic imports and exports:
On the import side, China is a major region for global lithium hydroxide refining capacity, and it can basically achieve self-sufficiency in lithium hydroxide. In 2024, China imported an average of about 500 mt of lithium hydroxide per month, a significant increase compared to the same period in 2023. However, most of this directly flowed to downstream manufacturers, and the quantity was relatively small compared to domestic supply, having almost negligible impact on the market.
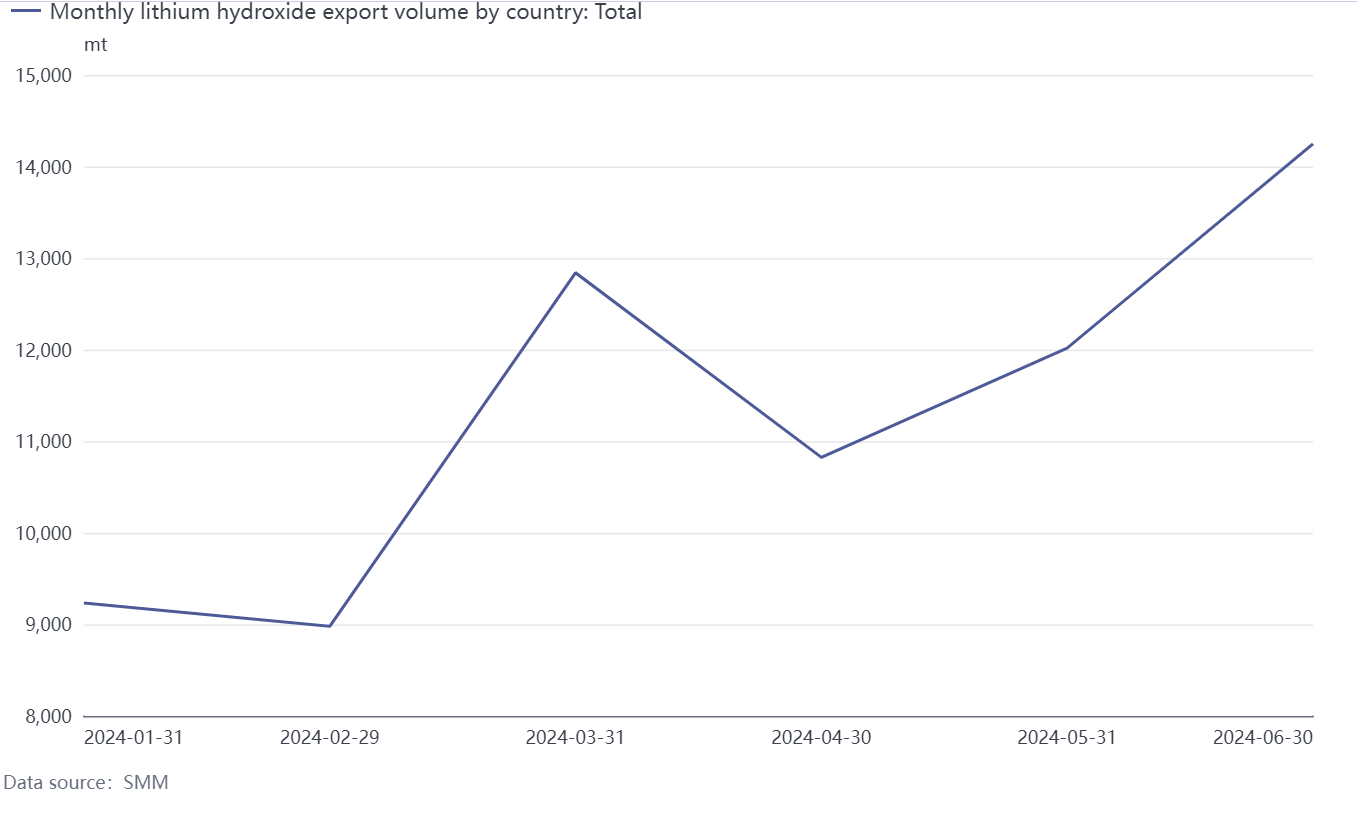
From the export demand perspective, South Korea and Japan, the first and second largest importers, accounted for over 95% of China's monthly lithium hydroxide exports. Overseas demand for lithium hydroxide in H1 was relatively stable, down about 1% MoM from H2 2023, but up about 12% YoY from H1 2023. In June, lithium hydroxide exports reached a recent peak of 14,200 mt. This was analyzed to be due to the phased stocking by overseas ternary cathode material enterprises, rather than an increase in orders for ternary materials. Moreover, with the decline in sales of mid-to-high nickel energy vehicles in Europe and the uncertainty of the US policy on new energy vehicles, the demand outlook for lithium hydroxide overseas in H2 is not clear.
From the inventory perspective:
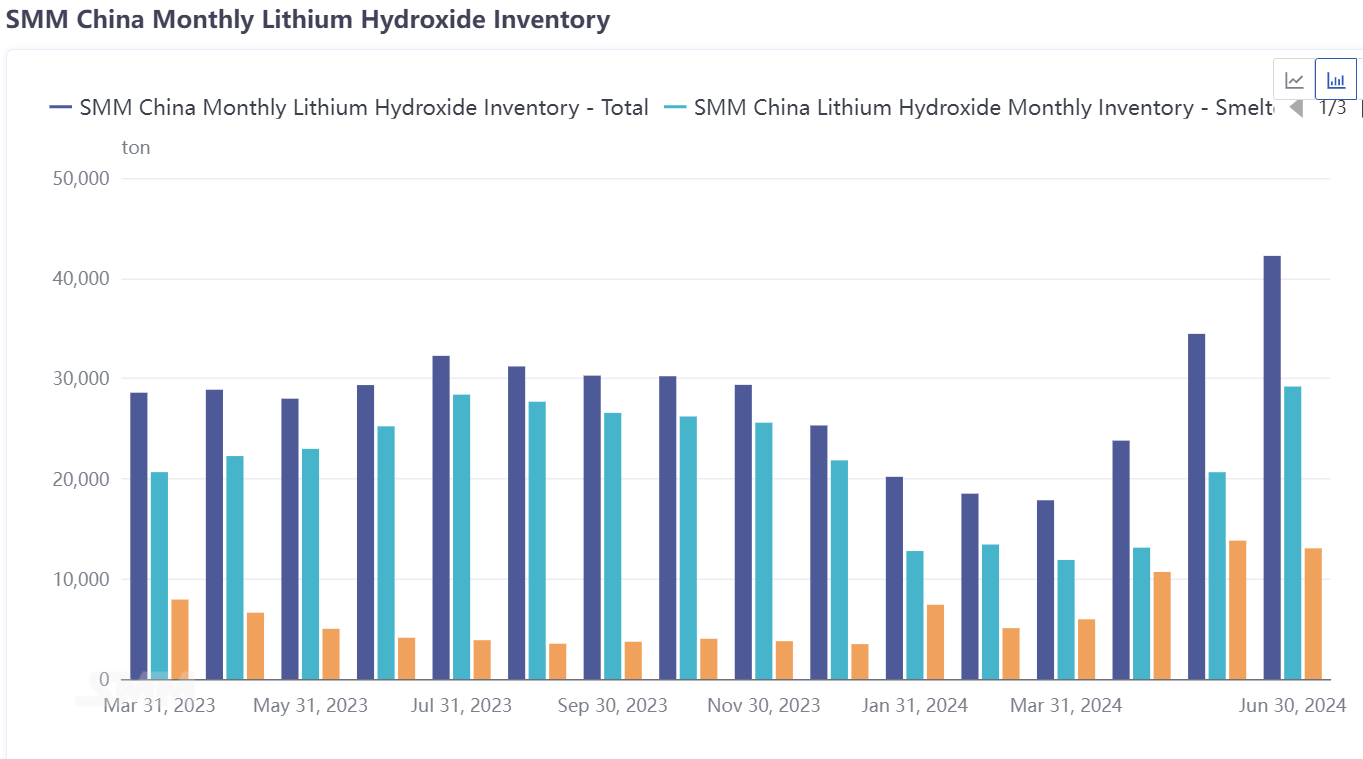
At the beginning of 2024, the lithium hydroxide market continued the destocking trend from the end of 2023. The main reasons were smelters' efforts to recoup funds through destocking and reduced production due to Chinese New Year maintenance. As smelters gradually resumed production after the holiday and new production lines ramped up capacity, upstream lithium hydroxide inventory gradually accumulated. Although some cathode material plants saw an increase in volume, the willingness to purchase lithium hydroxide externally was low due to increased customer supply and significant price fluctuations, leading to on-demand restocking. Comparing supply and demand, inventory saw a significant accumulation.
In summary, despite a brief recovery in demand and rising prices in the H1 of 2024, the lithium hydroxide market is under pressure due to several factors, including the decline in lithium carbonate prices, industry inventory accumulation, and a slowdown in downstream demand growth. From the perspective of producers, they can address the uncertain future market conditions by improving the quality and production efficiency of lithium hydroxide to reduce costs and meet market demand. Additionally, integrating the upstream and downstream industrial chains to form a stable supply and sales system can enhance market competitiveness. Lastly, closely monitoring national policies on NEVs and the new energy industry can help seize market opportunities brought by policy changes.