

SHANGHAI, Dec 10 (SMM) – China steel rebar inventories fell this week as rebar prices soared driven by strong performance of ferrous metals such as iron ore, coal and HRC, which have set record highs in 2020. The pessimistic wait-and-see stance in the overall market was reversed. Cautious bullish sentiment has begun to ferment, and trading enthusiasm has increased significantly.
Inventories of rebar across Chinese steelmakers and social warehouses stood at 6.19 million mt as of December 10, down 3.4% from a week ago and up 29.5% from a year earlier. The rate of reduction expanded 2 percentage points.
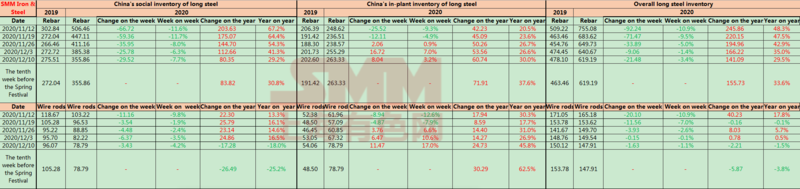
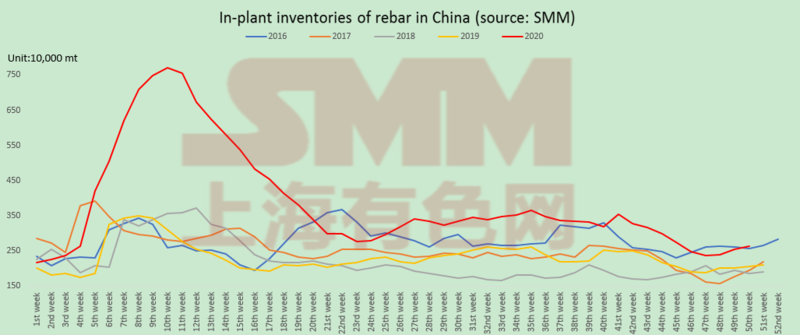
According to SMM data, inventories at Chinese steelmakers rose 80,400 mt on the week and stood at 2.63 million mt, up 30% from a year ago. From the time dimension of the lunar calendar, stocks are up 3.2% from a week ago and up 37.6% from a year earlier.
The rate of increase narrowed 3.8 percentage points. Current absolute prices of rebar are too high. In order to reduce the inventory pressure in the late winter stockpiling period, the steel mills have increased maintenance plans and the output has declined slightly. In addition, steel demand remained stable, and a small amount of speculative demand also improved under the continuous high prices of rebar. That also accounted for the decline in in-plant stocks.
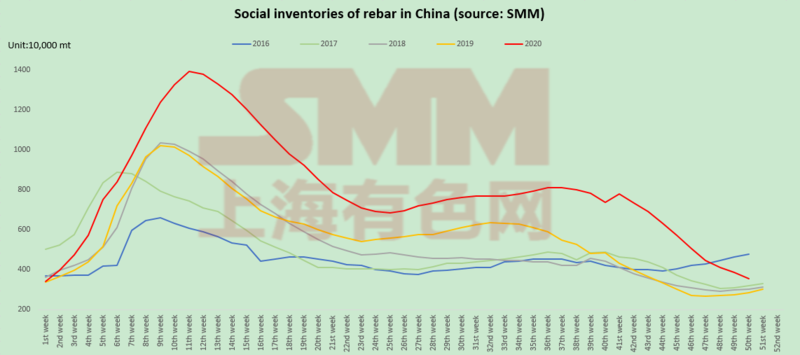
Inventories at social warehouses fell 295,200 mt on the week and stood at 3.56 million mt, down 7.7% from a week ago and 29.2% higher from a year ago.
Social stocks posted faster decline on week. The rise of rebar prices activated the overall market atmosphere, and end-users have been more willing to restock. In addition, according to an SMM survey, Hubei and Yangtze River Delta region once again ushered in a wave of "construction tide" before year-end, and steel demand improved again. Combined the rapid price increase, the merchants' fear of shipping at high prices has been aggravated, which jointly led to the decline in social stocks.
On the fundamentals, rebar is still the weakest ferrous metal. However, the demand in Beijing, Tianjin and Hebei is relatively high, while East China and South China are still in the peak season, and even new rigid demand appeared. The arrival of the turning point of inventories slows down again, and the resources in East China, Central China and Southwest China are still tight. The weakness of fundamentals is not obvious. Therefore, under the condition that the strong momentum of iron ore, HRC, coke and other ferrous metals has not decreased at all, it is expected that rebar prices will still have the driving force to follow the rise in a short pace in the near term. However, with the aggravation of the stock increase risk and the fermentation of the fear of high prices in the spot market, the callback risk after the rise is gradually increasing.



