SHANGHAI, Feb 10 (SMM) - Economic recovery was the theme across the globe in 2021, which, on the other hand, was accompanied by challenges and uncertainties. The long tail effect of the COVID-19 pandemic was increasingly clear on the back of diverse pandemic cycle in various countries, the mismatch of global supply and demand, the supply chain crisis, as well as the mutation of the COVID and the repeating pandemic. Zinc market, on the whole, was dominated by the mismatch of supply and demand when the global economy recovers slowly and the world economies held comparatively loose monetary policies.
At the beginning of 2021, the COVID-19 pandemic still haunted the global consumer market. Under this background, zinc prices moved all the way down below the breakeven point of smelters and hit a yearly low of 19,325 yuan/mt, coupled with the seasonally rising zinc ingot inventory. The zinc prices then bottomed out and showed a V-shaped trend amid rising vaccination around the globe as well as the steadily falling inventory.
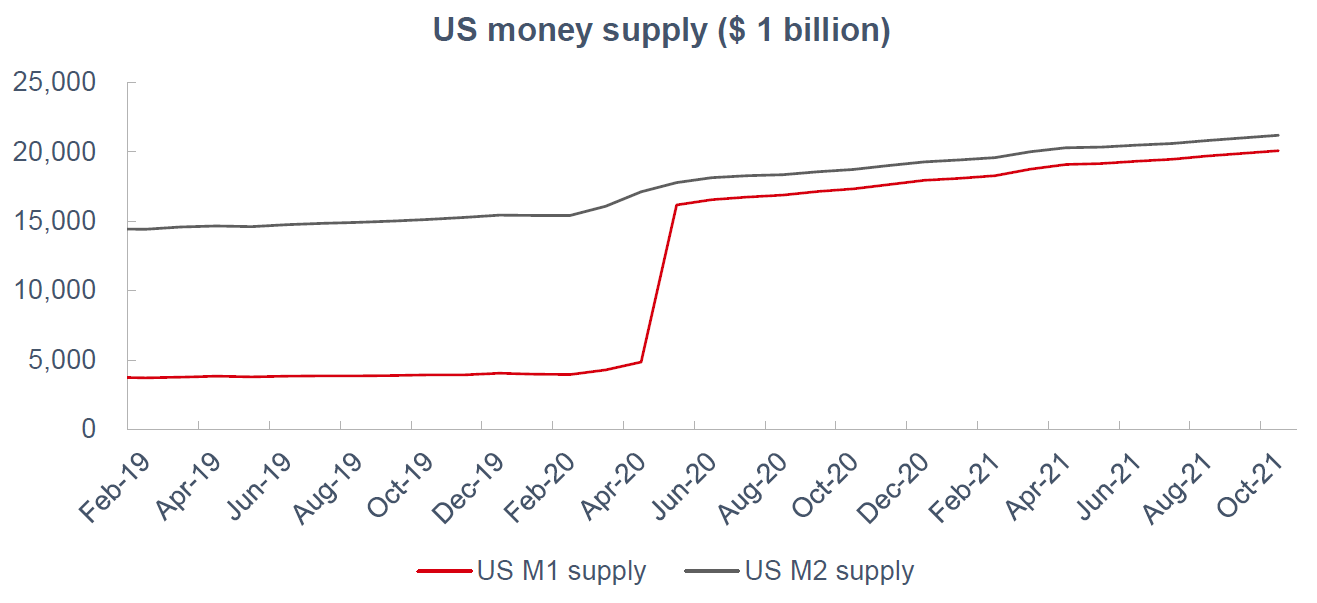
In the second quarter, the US Federal Reserve’s loose monetary policy once again sent a booster into the market in anticipation of Biden's 1.9 trillion stimulus bill, hence the market risk appetite grew. Zinc prices maintained moderate growth during this period. The power rationing policy surfaced in May under the requirement of dual control over energy consumption. The smelters in Yunnan were restricted by power cuts, and the real output of zinc ingot fell short of estimate. SHFE zinc surged and touched 23,535 yuan/mt, a high in the first half of 2021 and since the second half of 2018, on the back of low stocks. Later, the NFSRA announced to sell national reserves at regular intervals on June 16 in order to regulate the commodities prices, pulling back zinc prices for correction.
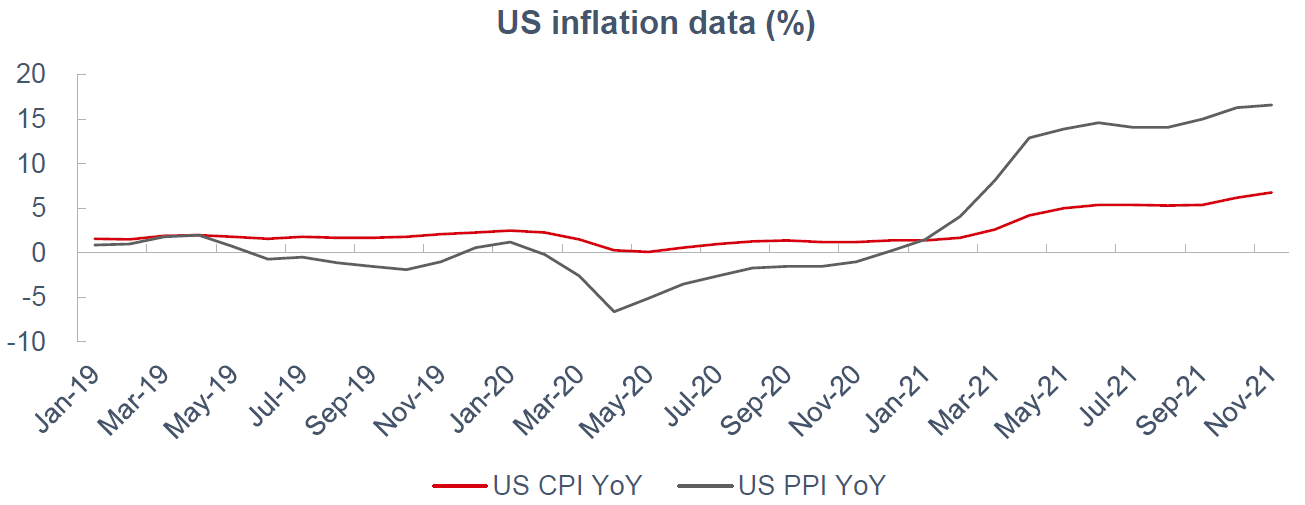
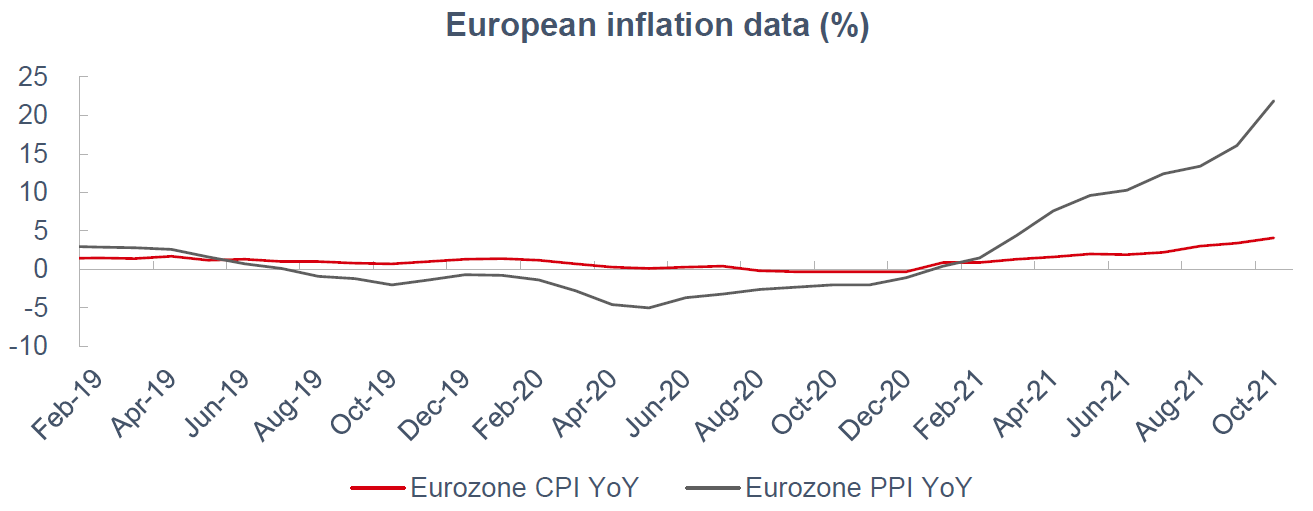
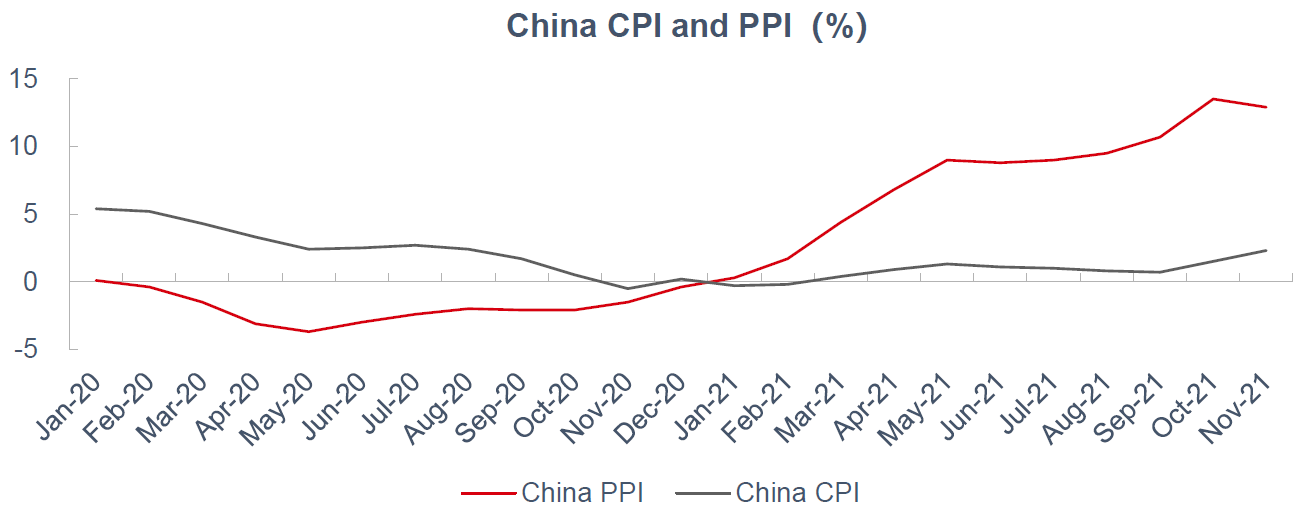
In the third quarter, the US non-farm data was quite satisfactory. However, the rise in commodity prices led by non-ferrous metals brought about by high inflation has finally been transmitted to the downstream since the third quarter across China, and the scissor difference between PPI and CPI continued to expand. The high raw material prices inhibited the downstream consumer demand.
And in the context of the steady recovery of foreign economies, China’s export market was gradually muted. Finally, some important domestic economy indicators including PMI fell into the contraction zone, and the domestic economy experienced downside risks. Globally speaking, the overseas market, which has been growing quickly, outperformed the China market, making the imbalance in global economic development.
On the other hand, after a cold winter in 2020, natural gas inventories in Europe fell to the historical low. The vulnerability of Europe's energy structure fuelled the rapid increase in natural gas prices. However, the economic recovery in the region created higher demand for natural gas in contrast to its supply insufficiency, inviting energy crisis which was still latent at this point.
In the fourth quarter, the high inflation caused by the loose monetary policies of the Federal Reserve at the beginning of the year has run through the whole year. The persistent problems concerning US employment readings, economic indicators and inflation put the Federal Reserve in a dilemma on the decision of interest rate hike, which led to the modification of the previous opinion that the inflation was transitory. Currently, it is widely believed that the inflation will extend into 2022.
Meanwhile, the European energy crisis finally broke out. Nyrstar took the lead in announcing production cuts at some of its smelting capacities in the Europe in light of high energy costs, followed by Glencore and other companies. The market sentiment became overheated and detonated a surge in zinc prices, with zinc prices touching limit up several times. Zinc prices rose by around 18% in just 6 trading days.
In China, the surging coal prices also offered strong momentum, and SHFE zinc touched a high of 27,720 yuan/mt, the highest since September, 2007. The central government quickly stepped forward and take strict measures to regulate coal prices from the macro level, which paid off well. As such, the zinc prices dropped and corrected the previous estimate amid slumping coal prices.
The Federal Reserve announced to taper its relief package for the COVID afterwards. And the zinc market returned to the logic subject to the fundamentals, and moved within a narrow range around 23,300 yuan/mt. Some zinc smelters in Europe announced to cut the production when the surging natural gas prices swallowed their profits, especially after September.
At present, the electricity prices in Europe exceeded 100 euros/MWh, and the losses of local smelters have been expanding. Zinc prices will gain support from the high electricity prices which is unlikely to be resolved in the short term.
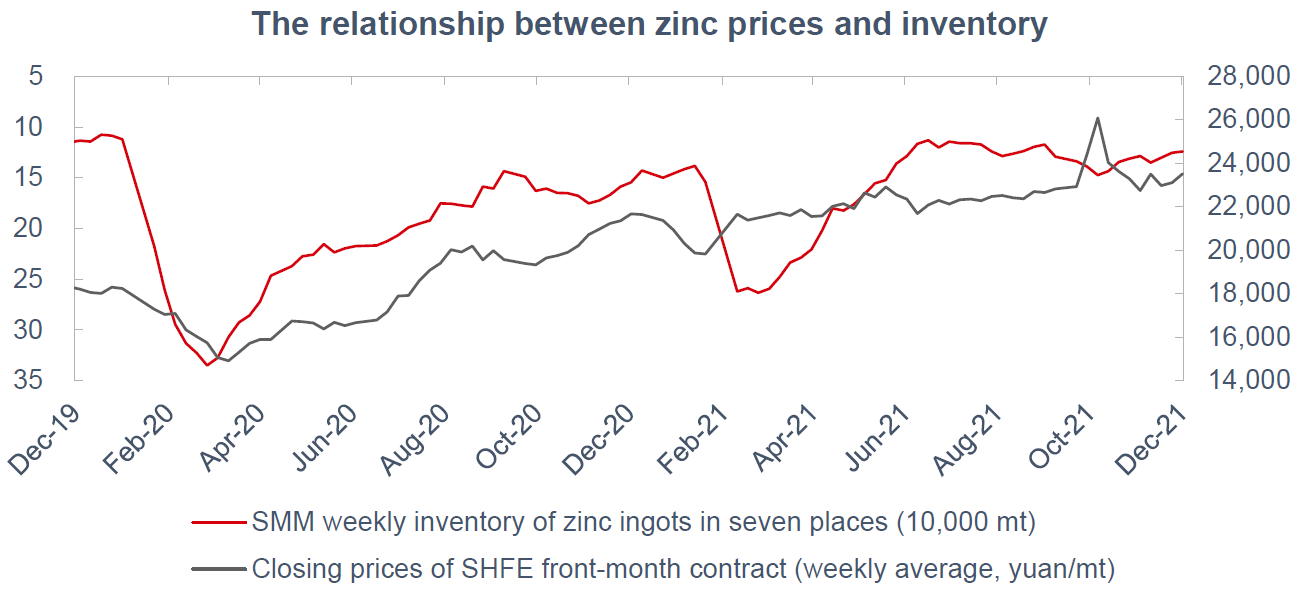
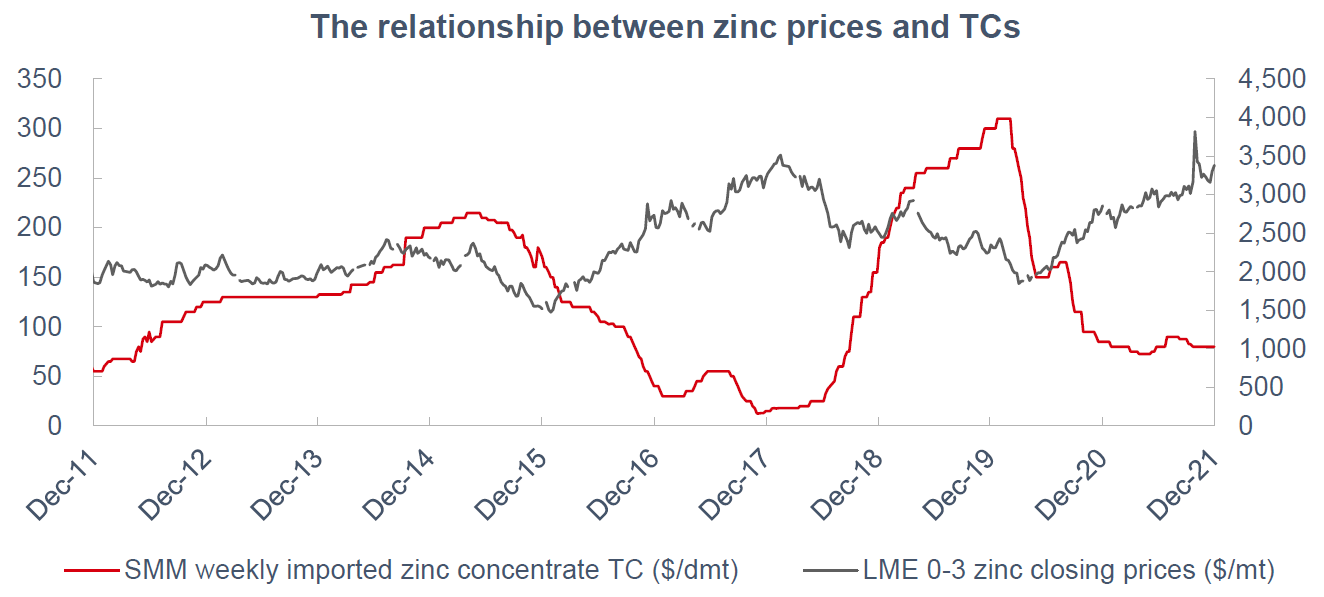
Besides, the dissent between the mining side and the smelters in terms of TCs weakened in 2021, and the ore output basically matched the demand, marking a great improvement from the previous absolute supply surplus. As such, TCs were less impacted by the mining side marginally. The main reason is that the smelters have been producing with high operating rates throughout 2021, hence were unable to increase the operating rates further even if the TCs rose. Therefore, the zinc prices were more greatly affected by the indicator of social inventories in 2021.
To access full SMM China Zinc Industry Chain Annual Report 2021-2025, please contact Michael Jiang at michaeljiang@smm.cn or T: +86-21-51666812 |M:+86-1522-1415-920.