[SMM thread] the road of accumulation is not over, and the upward road of steel price is not over.

Telah Terbit: Jul 16, 2020 17:47
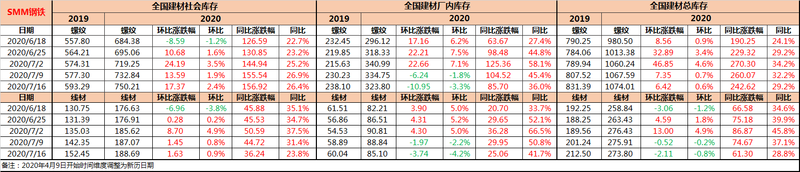
As of July 16, the country's total inventory of building materials was 10.7401 million tons, with a month-on-month ratio of + 0.6%, compared with the same period last year. Seasonal interference has not faded, central China, East China, southwest and other areas are still shrouded in overcast and rainy weather, terminal demand continues to be suppressed, so the thread inventory is still in a state of accumulation. However, after South China took the lead in "getting rid of difficulties", the strong replenishment of local demand is an important argument to prove the objective existence of the demand for quick work. The urgent demand for work is more urgent than in previous years, and the terminal just needs a good year-on-year performance, which is an important reason why the current year-on-year increase in inventory continues to narrow. (this week, the year-on-year increase of thread pool narrowed by 3%.


SMM7 March 16:

As of July 16, the country's total inventory of building materials was 10.7401 million tons, with a month-on-month ratio of + 0.6%, compared with the same period last year. Seasonal interference has not faded, central China, East China, southwest and other areas are still shrouded in overcast and rainy weather, terminal demand continues to be suppressed, so the thread inventory is still in a state of accumulation. However, after South China took the lead in "getting rid of difficulties", the strong replenishment of local demand is an important argument to prove the objective existence of the demand for quick work. The urgent demand for work is more urgent than in previous years, and the terminal just needs a good year-on-year performance, which is an important reason why the current inventory growth continues to narrow year-on-year (this week, the thread pool growth rate narrowed by 3 percentage points year-on-year).

Table 1: Overview of thread inventory
Source: SMM


Table 2: comparison of Thread inventory prices from 2018 to 2020
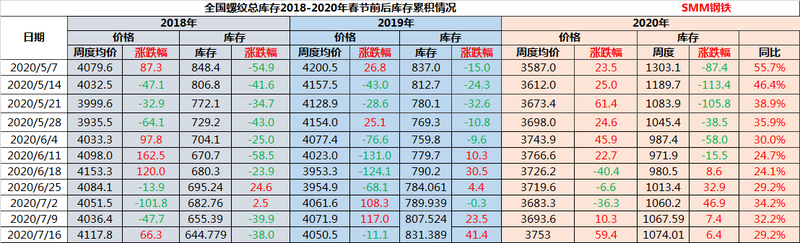
Note: due to the epidemic factors since 2020, due to the different opening times in different places, there is a certain error in the actual spot average price; the time dimension is the Gregorian calendar date.


Source: SMM

Specifically:

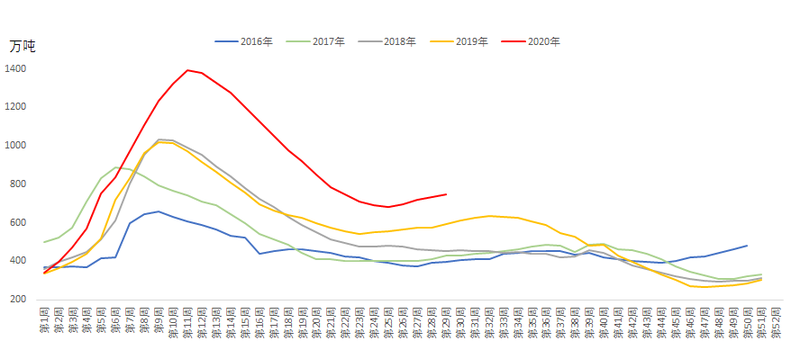
Social inventory of 7.5021 million tons, an increase of 173700 tons this week, + 2.4% month-on-month, + 26.9% year-on-year.

Under the background of a positive situation in the A-share bull market, the raw material side was led by the news side to rise first, driving the period snail to continue the strong situation in the past two weeks. The expectation of the spot market for the future is also improving, and the enthusiasm of traders to take goods has been significantly improved, accelerating the transfer of the factory warehouse to the social warehouse. While the terminal "steel needs" is "serious illness has not been cured", so the speed of accumulation has been accelerated.

Figure 1: an overview of the trend of threaded community library since 2016
Source: SMM

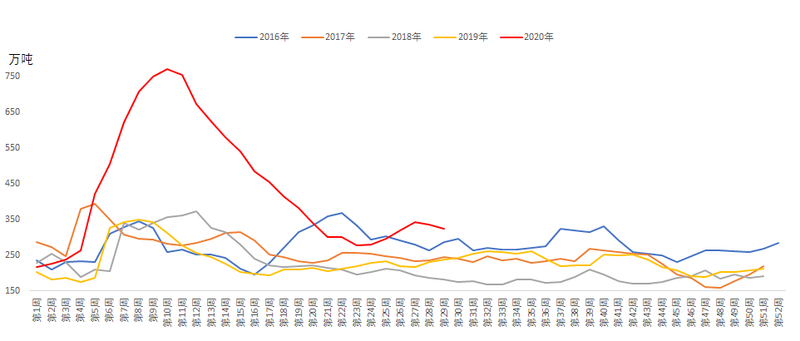
The inventory in the plant is 3.238 million tons, down 109500 tons this week,-3.3% month-on-month, + 36.0% year-on-year.

In addition to the market merchants' enthusiasm for taking goods driven by strong expectations, the decline in the output of steel mills is also an important reason for the decline in the factory warehouse. Under the dual pressure of high plant pressure and poor profitability, the overhaul and production reduction plans of steel mills have increased-according to SMM research, the planned rebar output of blast furnace steel mills in July decreased by 2% compared with the actual output in June, and the operating rate of electric furnace plants also dropped by about 11.52% compared with the same period in June.


Figure 2: an overview of the trend of thread factory warehouse from 2016 to now
Source: SMM

In the short term, the fundamentals of rebar are not unusual-the supply side is likely to maintain a small fluctuation at the current level, the demand side continues to be hit by precipitation, the road to rebar accumulation is not over, and steel prices are still in an awkward position of "neither up nor down". However, as more and more regions out of the "rainy season" haze, rush demand released as scheduled, thread fundamentals regained strong support, steel prices are expected to consolidate and continue to start.




Pernyataan Sumber Data: Kecuali informasi yang tersedia untuk publik, semua data lainnya diproses oleh SMM berdasarkan informasi publik, komunikasi pasar, dan mengandalkan model database internal SMM. Hanya untuk referensi dan tidak menjadi rekomendasi pengambilan keputusan.

Untuk pertanyaan atau informasi lebih lanjut, silakan hubungi: lemonzhao@smm.cn
Untuk informasi lebih lanjut tentang cara mengakses laporan penelitian kami, hubungi:service.en@smm.cn
Berita Terkait
Australia Tinjau Bea Antidumping Baja Galvanis dari India, Malaysia, Vietnam di Tengah Kekhawatiran Seng
11 Sep 2026 18:30
Australia Tinjau Bea Antidumping Baja Galvanis dari India, Malaysia, Vietnam di Tengah Kekhawatiran Seng
Baca Selengkapnya
Australia Tinjau Bea Antidumping Baja Galvanis dari India, Malaysia, Vietnam di Tengah Kekhawatiran Seng
Pada 9 September 2026, Australia memulai peninjauan sunset kedua atas tindakan antidumping terhadap baja lembaran galvanis dari India, Malaysia, dan Vietnam, serta secara terpisah meluncurkan peninjauan sunset atas tindakan imbalan terhadap impor dari India. Peninjauan ini mencakup periode Juli 2025–Juni 2026, dengan laporan akhir diperkirakan pada 11 Februari 2027. Karena baja galvanis merupakan sektor penggunaan akhir terbesar untuk seng, tindakan ini secara langsung memengaruhi biaya ekspor dan daya saing, yang berpotensi berdampak pada permintaan seng domestik dan rantai pasok Australia. Mempertahankan bea masuk akan memberikan perlindungan bagi kapasitas baja dan pelapisan domestik, sementara penghentian dapat meningkatkan impor berharga murah dan memengaruhi konsumsi seng regional. Hasil akhir tetap bergantung pada penetapan otoritas.
11 Sep 2026 18:30
Proyek Ekspansi JCC Hongyuan Copper Senilai 200 Juta Dolar AS Bertujuan Meningkatkan Kapasitas Menjadi 550.000 Ton pada 2027
7 Sep 2026 15:43
Proyek Ekspansi JCC Hongyuan Copper Senilai 200 Juta Dolar AS Bertujuan Meningkatkan Kapasitas Menjadi 550.000 Ton pada 2027
Baca Selengkapnya
Proyek Ekspansi JCC Hongyuan Copper Senilai 200 Juta Dolar AS Bertujuan Meningkatkan Kapasitas Menjadi 550.000 Ton pada 2027
Proyek perluasan katoda tembaga 300.000 ton/tahun milik JCC Hongyuan Copper, anak perusahaan Jiangxi Copper Corporation, memasuki tahap pengumuman publik pra-persetujuan penilaian dampak lingkungan pada 4 September, dengan total investasi sekitar 1,416 miliar yuan. Proyek ini direncanakan mulai dibangun pada September 2026 dan selesai pada Desember 2027. Setelah selesai, total kapasitas JCC Hongyuan akan melonjak dari 250.000 ton menjadi 550.000 ton.
7 Sep 2026 15:43
Yen Jepang Menguat USD/JPY Turun di Bawah 159 di Tengah Spekulasi Intervensi
3 Sep 2026 19:00
Yen Jepang Menguat USD/JPY Turun di Bawah 159 di Tengah Spekulasi Intervensi
Baca Selengkapnya
Yen Jepang Menguat USD/JPY Turun di Bawah 159 di Tengah Spekulasi Intervensi
[SMM Kilat Logam Mulia] Yen Jepang melonjak tajam selama perdagangan Rabu, dengan USD/JPY turun di bawah 159 dan ditutup melemah 0,92% di 158,69, memicu spekulasi intervensi mata uang Jepang. Indeks dolar juga turun tajam, dengan lingkungan dolar yang lebih lemah memberikan dukungan bagi logam mulia.
3 Sep 2026 19:00

