The Minister of South Africa renews the conjecture of mine-end supply at the peak of the epidemic.

Telah Terbit: Jul 10, 2020 11:06 (GMT+8)

On 9 July, the Government of South Africa released a speech by Minister Zwerimhertz (Zweli Mkhize) to brief Parliament on the latest situation of the COVID-19 pandemic of the coronavirus.

According to Mhertz's report, since the release of the latest scientific model results in May 2020, the government has synchronously updated the national COVID Epi model, used South African hospitalization data to estimate virus reproduction and adjust detection methods, and re-modeled COVID-19 in areas with different infection levels. The latest model predicts that the country is expected to reach its peak in mid-August, which is close to the previous forecast, but the expected number of infections during the peak period will be lower than previously expected. This means that in an optimistic scenario, the number of infections from May to June is also lower than previously expected. At the same time, it was indicated that it was expected that the currently planned hospital beds in the Eastern Cape and Gauteng provinces would not be sufficient to meet the demand for non-ICU beds and overflow when ICU capacity was insufficient. It is expected that there will be a shortage of beds in the next four weeks (including all currently committed public and private sector beds).
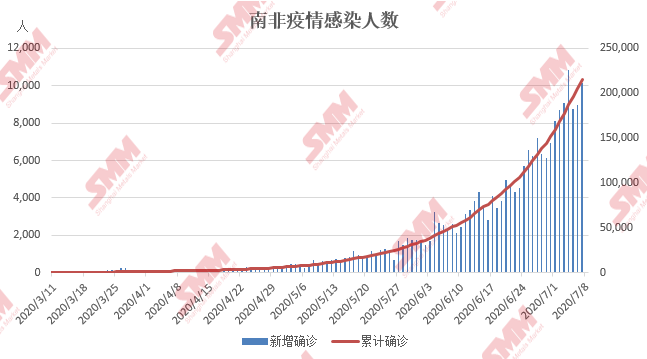
When the blockade was imposed in South Africa on March 24, the South African government predicted the outbreak period for the first time in June. Judging from the actual infection situation, the prediction was too accurate and scientific, and the number of new infections continued to break through the new high. After adjusting the national COVID Epi model in May, the outbreak peak was changed from the end of August to early September. Although the government has re-regionally raised the blockade level, it abandoned the blockade again in view of the difficulty of re-implementation and the sharp decline in exports, which is an "unbearable burden" on the South African economy.

The latest outbreak forecast released by the South African government is about half a month ahead of the second forecast. Judging from the current public statement by the government and relevant reports from South Africa, it is less likely that the government will upgrade the blockade level again in mid-August to deal with the epidemic, but it is very worrying whether the actual outbreak of infection in major ports and the shortage of beds will once again drag down the country's transport and production efficiency. According to industry estimates, the efficiency of port Elizabeth is still only 70% of what it was before the outbreak since the blockade was downgraded to phase 3 in June.


Pernyataan Sumber Data: Kecuali informasi yang tersedia untuk publik, semua data lainnya diproses oleh SMM berdasarkan informasi publik, komunikasi pasar, dan mengandalkan model database internal SMM. Hanya untuk referensi dan tidak menjadi rekomendasi pengambilan keputusan.

Untuk pertanyaan atau informasi lebih lanjut, silakan hubungi: lemonzhao@smm.cn
Untuk informasi lebih lanjut tentang cara mengakses laporan penelitian kami, hubungi:service.en@smm.cn
Berita Terkait
【Flash | Biaya Tambahan Pipa Mengandung Mo Tubacex Oktober Bervariasi】
18 jam yang lalu
【Flash | Biaya Tambahan Pipa Mengandung Mo Tubacex Oktober Bervariasi】
Baca Selengkapnya
【Flash | Biaya Tambahan Pipa Mengandung Mo Tubacex Oktober Bervariasi】
Tubacex menerbitkan biaya tambahan paduan pipa untuk bulan Oktober. Dalam euro, 316/316L hot-/cold-finished turun dari €5,07/€5,59 per kg (€5.070/€5.590 per ton) menjadi €5,05/€5,56 per kg (€5.050/€5.560 per ton). Material dengan kandungan Mo tinggi, dengan Mo di atas 2,5%, turun dari €5,26/€5,79 menjadi €5,23/€5,76 per kg. Biaya tambahan untuk 2205 dan 2507 tidak berubah, sementara 254 SMO naik dari €9,64/€10,62 menjadi €9,67/€10,65 per kg. Analisis SMM: sebagian besar grade pipa yang mengandung Mo datar atau sedikit lebih rendah, sementara 254 SMO bergerak lebih tinggi, menunjukkan transmisi biaya yang terdiferensiasi antar grade.
18 jam yang lalu
[SMM Kilasan Baja Tahan Karat] Harga skrap baja tahan karat India berbeda arah karena 304 melemah seiring nikel dan 316 yang ketat tetap kokoh
18 jam yang lalu
[SMM Kilasan Baja Tahan Karat] Harga skrap baja tahan karat India berbeda arah karena 304 melemah seiring nikel dan 316 yang ketat tetap kokoh
Baca Selengkapnya
[SMM Kilasan Baja Tahan Karat] Harga skrap baja tahan karat India berbeda arah karena 304 melemah seiring nikel dan 316 yang ketat tetap kokoh
[SMM Kilasan Baja Tahan Karat] Harga skrap baja tahan karat India berbeda arah karena 304 melemah seiring nikel dan 316 yang ketat tetap kokoh
Pasar skrap baja nirkarat India bergerak ke arah yang berbeda pada pekan yang berakhir 1 Oktober. Harga skrap 304 domestik sedikit melemah dan penawaran impor mengikuti, sementara harga 316 bertahan stabil baik di pasar domestik maupun impor. Pelemahan harga nikel LME membebani sentimen 304, dan pembeli hanya memenuhi kebutuhan mendesak karena perdagangan melambat selama periode perayaan. Ketersediaan yang ketat membatasi penurunan harga 316. Terkait pengadaan, jendela pemrosesan yang pendek setelah pelonggaran persyaratan Sertifikat Inspeksi Pra-Pengapalan (PSIC) oleh pemerintah, ditambah biaya impor tambahan, terus membatasi fleksibilitas pabrik. Beberapa pabrik sedang mengevaluasi billet, slab, dan nikel pig iron (NPI) sebagai alternatif skrap untuk mengelola biaya input. Melihat lebih jauh ke depan, proposal Uni Eropa untuk membatasi ekspor limbah logam ke India berdasarkan Regulasi Pengiriman Limbah (WSR) yang baru, jika diadopsi, akan semakin mempersempit opsi impor skrap India. Dalam jangka pendek, skrap 304 menghadapi tekanan penurunan ringan jika nikel tetap lemah, sementara 316 diperkirakan tetap kokoh selama pasokan tetap ketat. Perkembangan PSIC dan keekonomian relatif billet dan NPI akan menjadi faktor kunci yang perlu dicermati.
18 jam yang lalu
【Kilat | Metallus Menaikkan Komponen Biaya Tambahan Molibdenum Oktober untuk Baja 300M】
18 jam yang lalu
【Kilat | Metallus Menaikkan Komponen Biaya Tambahan Molibdenum Oktober untuk Baja 300M】
Baca Selengkapnya
【Kilat | Metallus Menaikkan Komponen Biaya Tambahan Molibdenum Oktober untuk Baja 300M】
Metallus menetapkan biaya tambahan bahan baku bulan Oktober untuk periode 1–30 Oktober. Komponen Mo untuk baja 300M naik 0,52% menjadi $15,176/cwt, sekitar $334,57/t baja, dari $15,098/cwt, atau $332,85/t. Total biaya tambahan yang tercantum naik 1,03% menjadi $45,054/cwt. Skrap naik menjadi $17,750/cwt, sementara biaya tambahan energi terpisah untuk batangan dan tabung turun dari $1,296/cwt, sekitar $28,57/t, menjadi $0,050/cwt, atau $1,10/t.
18 jam yang lalu

