[SMM Thread] Regional differences are prominent, and spot prices fall differently after National Day.

Telah Terbit: Oct 22, 2019 17:29
Recently, environmental production restrictions have not been significantly effective, supply does not reduce but rose slightly, making the market bearish sentiment shrouded in heavy inventory for a long time. According to SMM statistics, the current mainstream market thread spot price decline in 30-270 yuan / ton, of which most concentrated in the 100-200 yuan / ton decline range. Due to the great differences between regions, SMM has carried out a follow-up study of this phenomenon.

SMM10, 22nd:

Recently, environmental production restrictions have not been significantly effective, supply does not reduce but rose slightly, making the market bearish sentiment shrouded in heavy inventory for a long time.
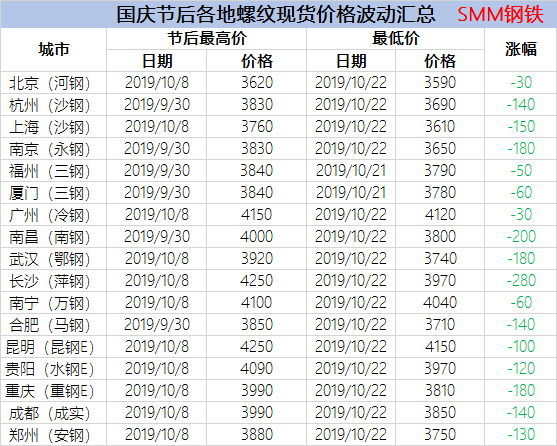
According to SMM statistics, the current mainstream market thread spot price decline in 30-270 yuan / ton, of which most concentrated in the 100-200 yuan / ton decline range. Due to the great differences between regions, SMM has carried out a follow-up study of this phenomenon.

Tons of steel fell in the area of 100-200 yuan: the mainstream area.

According to SMM research, in addition to the northeast due to the gradual cold weather, demand weakening, the current rigid demand for building materials in other regions show full toughness, good shipping condition. However, the phenomenon of large inventory pressure is more common. And at present, in addition to Beijing, Tianjin, Hebei and surrounding areas, other areas controlled by environmental protection and production restrictions in previous years (such as Jiangsu) have no policy notice, the market generally has increased expectations for supply pressure, so the operation of selling goods at low prices before the arrival of the off-season is more common.

At the same time, as pessimism still occupies the mainstream of the market, if the scope of production restriction has not been further expanded, the late spot price or weak back to the sky, continue to operate weakly.

In the range of $30 to $60 per ton of steel:

North China: Hebei, Shanxi and other Beijing-Tianjin-Hebei and surrounding areas have entered the stage of environmental protection and production restriction during the heating season, especially under the influence of pollution weather. Tangshan City, a "major town", issued two more stringent notices on the 15th and 18th of this month, and a number of traders reported that they had fewer supplies in their hands, supporting the market price to a certain extent. In addition, in Beijing, for example, inventories in September have been lower than in the same period last year. Although the recent year-on-year growth turned negative to positive, but the current local demand performance is still good, inventory pressure is not great, so the market mentality is also more rational, spot prices are more resilient.

Fujian market: steel mills have a large bargaining power for the market, with a strong willingness to raise prices, coupled with some business feedback has part of the phenomenon of relative shortage of specifications.

South China market: the demand performance is good, the Nanning market has the specification shortage situation, the spot price has the strong support. However, it is reported that the north material southward is already in the start-up, and there will be a more concentrated increment in November, when the increase in supply pressure will suppress the local spot price.

Region with a decline of more than 200 yuan per ton of steel: Hunan

Spot prices in Hunan rose rapidly in September, mainly due to on the one hand, a number of mainstream steel mills production reduction, making the market out of stock phenomenon is more common; on the other hand, the demand suppressed by torrential rain has been concentrated.

The production of mainstream steel mills resumed in October, and due to the high prices in the previous period and the small inflow of external resources, the shortage phenomenon was solved, at the same time, the demand was also stable, so the decline in spot prices after the festival was also beyond the reach of other regions.


 

Pernyataan Sumber Data: Kecuali informasi yang tersedia untuk publik, semua data lainnya diproses oleh SMM berdasarkan informasi publik, komunikasi pasar, dan mengandalkan model database internal SMM. Hanya untuk referensi dan tidak menjadi rekomendasi pengambilan keputusan.

Untuk pertanyaan atau informasi lebih lanjut, silakan hubungi: lemonzhao@smm.cn
Untuk informasi lebih lanjut tentang cara mengakses laporan penelitian kami, hubungi:service.en@smm.cn
Berita Terkait
Australia Tinjau Bea Antidumping Baja Galvanis dari India, Malaysia, Vietnam di Tengah Kekhawatiran Seng
11 Sep 2026 18:30
Australia Tinjau Bea Antidumping Baja Galvanis dari India, Malaysia, Vietnam di Tengah Kekhawatiran Seng
Baca Selengkapnya
Australia Tinjau Bea Antidumping Baja Galvanis dari India, Malaysia, Vietnam di Tengah Kekhawatiran Seng
Pada 9 September 2026, Australia memulai peninjauan sunset kedua atas tindakan antidumping terhadap baja lembaran galvanis dari India, Malaysia, dan Vietnam, serta secara terpisah meluncurkan peninjauan sunset atas tindakan imbalan terhadap impor dari India. Peninjauan ini mencakup periode Juli 2025–Juni 2026, dengan laporan akhir diperkirakan pada 11 Februari 2027. Karena baja galvanis merupakan sektor penggunaan akhir terbesar untuk seng, tindakan ini secara langsung memengaruhi biaya ekspor dan daya saing, yang berpotensi berdampak pada permintaan seng domestik dan rantai pasok Australia. Mempertahankan bea masuk akan memberikan perlindungan bagi kapasitas baja dan pelapisan domestik, sementara penghentian dapat meningkatkan impor berharga murah dan memengaruhi konsumsi seng regional. Hasil akhir tetap bergantung pada penetapan otoritas.
11 Sep 2026 18:30
Proyek Ekspansi JCC Hongyuan Copper Senilai 200 Juta Dolar AS Bertujuan Meningkatkan Kapasitas Menjadi 550.000 Ton pada 2027
7 Sep 2026 15:43
Proyek Ekspansi JCC Hongyuan Copper Senilai 200 Juta Dolar AS Bertujuan Meningkatkan Kapasitas Menjadi 550.000 Ton pada 2027
Baca Selengkapnya
Proyek Ekspansi JCC Hongyuan Copper Senilai 200 Juta Dolar AS Bertujuan Meningkatkan Kapasitas Menjadi 550.000 Ton pada 2027
Proyek perluasan katoda tembaga 300.000 ton/tahun milik JCC Hongyuan Copper, anak perusahaan Jiangxi Copper Corporation, memasuki tahap pengumuman publik pra-persetujuan penilaian dampak lingkungan pada 4 September, dengan total investasi sekitar 1,416 miliar yuan. Proyek ini direncanakan mulai dibangun pada September 2026 dan selesai pada Desember 2027. Setelah selesai, total kapasitas JCC Hongyuan akan melonjak dari 250.000 ton menjadi 550.000 ton.
7 Sep 2026 15:43
Yen Jepang Menguat USD/JPY Turun di Bawah 159 di Tengah Spekulasi Intervensi
3 Sep 2026 19:00
Yen Jepang Menguat USD/JPY Turun di Bawah 159 di Tengah Spekulasi Intervensi
Baca Selengkapnya
Yen Jepang Menguat USD/JPY Turun di Bawah 159 di Tengah Spekulasi Intervensi
[SMM Kilat Logam Mulia] Yen Jepang melonjak tajam selama perdagangan Rabu, dengan USD/JPY turun di bawah 159 dan ditutup melemah 0,92% di 158,69, memicu spekulasi intervensi mata uang Jepang. Indeks dolar juga turun tajam, dengan lingkungan dolar yang lebih lemah memberikan dukungan bagi logam mulia.
3 Sep 2026 19:00

