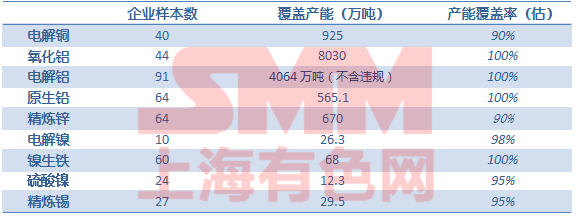
Summary of basic Metal production in China in March 2019
In March 2019, SMM China's electrolytic copper production was 751100 tons, an increase of 4.38 percent over the previous month, an increase of 5.28 percent over the same period last year, and a cumulative output of 2.2069 million tons in the first quarter, an increase of 4.17 percent.
Production growth in March was lower than expected in February, mainly because Chinalco's southeast copper industry, which went into production in the fourth quarter of last year, had not yet reached production, and in March a small number of refineries said sales were under pressure and production had slowed slightly. According to SMM research, most small and medium-sized smelters are concerned about the rapid decline in spot copper concentrate TC, but no refinery has been found to mention that it will have an impact on production. In addition, the price of sulfuric acid is better, which can slightly resist the risk caused by the decline of copper concentrate TC. The reclaimed copper smelter in operation says the supply of scrap copper is stable and production is expected to remain normal in April. However, there is widespread concern about the supply of imported scrap copper after the "six categories" shift, and production is expected to be affected starting in June.
In April, most smelters will have maintenance plans, such as Wuxin in Xinjiang, Dongying Fangyuan, Jinchuan in Guangxi, Yuguang Gold and lead, Yanggu Xiangguang, Hengbang shares, Jinlong Copper Industry, etc., which have a great impact on the overall output in April. Guangxi Nanguo Copper Industry began feeding production in mid-April, but it was difficult to produce in April. Judging from the production schedule, SMM expects China's electrolytic copper production to be 687900 tons in April, a sharp decrease of 8.41 percent from the previous month, and a decrease of 6.76 percent from the same period last year. The cumulative output from January to April was 2.8948 million tons, an cumulative increase of 1.35 percent.
Alumina:
In March (31 days), China's alumina (metallurgical grade) output was 6.019 million tons, an increase of 5.07 percent over the same period last year, with an average daily output of 194000 tons, a decrease of 7000 tons compared with the previous month, and an annualized operation capacity of 70.8642 million tons.
The monthly decline in alumina production and operating capacity in March was mainly due to ore problems and repairs, such as Chinalco Huaxing, Chinalco Shanxi, Dongfang Hope Sanmenxia and Jinzhong plants, which all reduced production due to ore shortage and high cost. In addition, for example, the maintenance of Xiaoyi / Jiao Kou Xinfa, Shanxi Fusheng and Xinfa Huayu affected some of the output, in addition, Xiangjiang Wanji also affected part of the output due to technical transformation.
China's alumina production is expected to be 6.025 million tons in April (30 days), an increase of 3.88 percent over the same period last year, with a daily average of 201000 tons, an increase of 7000 tons from the previous month. The increase in average daily output over the previous month is due to the fact that most of the production capacity for production reduction and maintenance in March has been or will resume production, and second, the capacity that has completed the transformation of ultra-low emission limits is expected to be released again. Third, for example, the Boxie Nanchuan Shuijiang alumina project and the recovery capacity created by Lu Yubo will be stable, and fourth, after the heating season, some alumina plants in Shanxi and Henan areas that have been unable to produce or stop production due to environmental problems will resume full production.
Electrolytic aluminum:
In March (31 days), the national electrolytic aluminum production capacity was 2.981 million tons, down 1.5 percent from the same period last year. By the end of March, the domestic electrolytic aluminum operation capacity was 35.97 million tons, a decrease of about 430000 tons compared with the same period last year. In the first quarter of 2019, the domestic electrolytic aluminum production reduced by more than 500000 tons, and the scale of new and resumed production capacity in the same period was affected by the low aluminum price, which was relatively slow. According to SMM, the cumulative output of electrolytic aluminum in China was 8.633 million tons in the first quarter of this year, down 1.2 per cent from the same period last year. In March 2019, the actual domestic consumption of electrolytic aluminum was 3.057 million tons, an increase of 4.9 percent over the same period last year, ending the negative growth in consumption in the first two months. After April, with the influence of factors such as cost compression and aluminum price recovery, some new production capacity in Guangxi, Yunnan and other provinces has increased slowly, and the total domestic electrolytic aluminum output is expected to be 2.9 million tons in April (30 days). The actual monthly consumption is 3.058 million tons, an increase of 2.5 percent over the same period last year, and domestic social stocks of electrolytic aluminum are expected to fall to around 1.53 million tons by the end of April.
Primary lead
In March 2019, China's primary lead production was 257700 tons, up 14.48 percent from the previous month and 5.83 percent from the same period last year. From January to March 2019, primary lead production was 756800 tons, up 7.34 per cent from a year earlier.
According to SMM research, in addition to Xinling in Henan Province to enter maintenance, other smelting enterprises due to the end of the Spring Festival, as well as the increase in the normal working day in March, the output of primary lead smelting enterprises generally increased; In addition, Hunan Yuteng, Yinxing and other maintenance recovery, the original lead production fully recovered, basically in line with the expectations of the previous report.
In addition, compared with March 2018, the production of primary lead increased significantly in March this year, mainly due to the centralized maintenance of primary lead smelting enterprises in March 2018, such as Yuguang, Wanyang, South, Jiang Copper, Hengbang, etc., with maintenance periods ranging from 20 to 45 days. In addition, for example, due to the influence of heavy pollution weather in Henan, the production of some refineries is limited.
Looking forward to April, most primary lead smelting enterprises maintain normal production, and the expected output is basically the same as that in March. During this period, Anhui Tongguan, Yunnan Chihong, Chifeng Mountain Gold, Silver and lead have entered the maintenance one after another, Henan Xinling maintenance is over, so SMM expects the production of primary lead to drop slightly to 256000 tons in April.
Refined zinc:
In March 2019, SMM China produced 452100 tons of refined zinc, up 7.55 percent from the previous month and 1.39 percent from the same period last year. The SMM survey sample has a production capacity of 6.085 million tons.
In March, when the Spring Festival holiday returned, the processing fee for zinc concentrate was still slightly increased, and the profits of refineries increased further, stimulating the enthusiasm of production. In March, the production days of refineries also increased compared with February. Due to the increase of production days, some enterprises recorded a significant increase in output and contributed more increments in March. At the same time, some enterprises in western Hunan resumed production after the festival, and the output also increased. Although some enterprises small-scale maintenance, but the impact on the whole is not great, the output increased significantly compared with the previous month.
In April, although the new capacity of Zhuzhou smelting was further released slightly, and the output of zinc and germanium in Sihuan increased at the end of maintenance, Chihong zinc germanium and silver nonferrous metal entered the maintenance state, offsetting the increase in output. According to the April refinery production schedule, domestic refined zinc production is expected to fall 1900 tons to 450200 tons in April from March, an increase of 1.26 per cent from a year earlier and a decrease of 0.41 per cent from the previous month.
Electrolytic nickel:
In March 2019, the national natural monthly output of electrolytic nickel was 12800 tons, an increase of 4.77 per cent over the same period last year. In March, the national electrolytic nickel production increased by 6.03% over February. The production of electrolytic nickel was normal in March, and the increase of production was mainly due to the increase of natural days. According to a preliminary investigation by SMM, electrolytic nickel production continued to be stable in April, with production falling by about 2 per cent from March to 12600 tons, affected by the reduction in natural days.
Nickel pig iron:
In March, the national nickel pig iron increased by 13.20 per cent to 45800 nickel tons, an increase of 20.39 per cent from the same period last year. In terms of taste, the output of high nickel pig iron increased by 8.60 per cent to 40400 nickel tons in March compared with February, on the one hand, due to the increase in natural days, on the other hand, due to the increase in the new output of large-scale nickel pig iron plants in Shandong Province. Low nickel pig iron production rose 64.1 per cent to 5500 nickel tons in March from a month earlier, mainly due to the resumption of low nickel pig iron production at two stainless steel plants in the south, in addition to the increase in natural days.
In April, national nickel pig iron production is expected to increase by 3.01 per cent to 47200 nickel tons compared with the previous month, of which high nickel pig iron production increased by 1.56 per cent to 41000 nickel tons, as large nickel pig iron plants in Shandong continue to release. The production of low nickel pig iron increased by 13.71 per cent to 6200 nickel tons compared with the March ring, mainly due to the continued release of production from the two stainless steel plants in the south.
Nickel sulfate:
In March, China produced 10967 tons of nickel sulfate and 49900 tons in kind. Production rose 13.68% in March from a month earlier, mainly due to the increase in production days in March and the resumption of normal production at some nickel sulfate plants closed during the Spring Festival this month, while a nickel sulfate plant in Guangdong resumed production in March. The new policy on subsidies for new energy vehicles was issued in March and formally implemented at the end of June. In order to obtain the corresponding subsidies during this transitional period, the automobile enterprises actively "rush to install", and the demand transmitted upward to nickel sulfate is maintained at a high level, and the nickel sulfate market is tightly balanced. The national nickel sulfate production increased slightly in April, with a month-on-month increase of 1.20%. The output of Guangdong nickel sulfate plant continued to be released, but the decrease in April output of Gansu plant offset part of the increase, and the production of other nickel sulfate plants changed little.
Refined tin:
The output of refined tin in March was 12067 tons, an increase of 26.2 per cent over February. In March, most of the smelters affected by Spring Festival factors resumed production normally, so the total output rebounded significantly. Huaxi Guilai smelter is still shut down in March and is expected to resume production in April. In addition, due to equipment maintenance and other reasons, a small number of smelters in Yunnan and Jiangxi are also in a state of shutdown, which has an impact on some of the output. Due to the resumption of production in Huaxi in April, the output of tin ingots is expected to reach about 12800 tons in April.
Production of metal products in March 2019
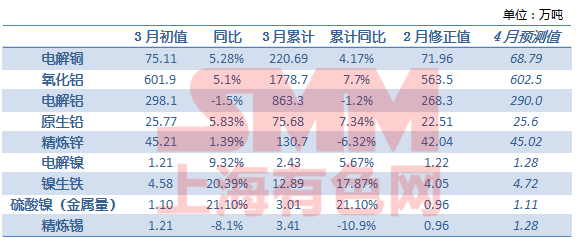
Description:
1. The value with * is the modified value, and the value of italics is the predicted value.
2. The output of nickel pig iron refers to the data after the physical quantity is converted into metal.
Research methodology: