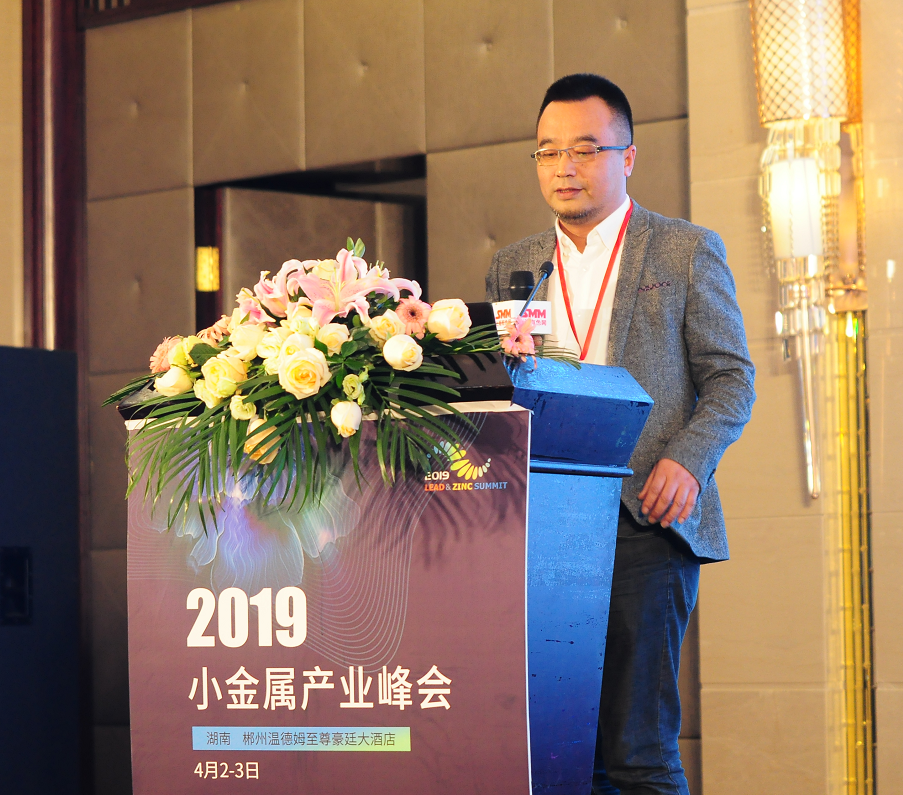
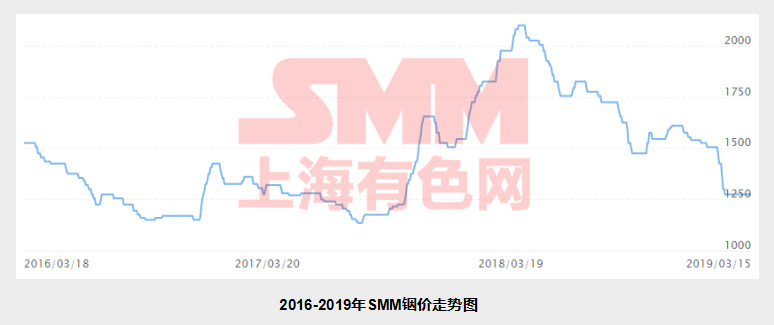
SMM4, March 3: since April 9, 2018, the price of indium has ended the sharp rise since August 7, 2018. as of March 29, 2019, SMM reported the price of refined indium at 1275 yuan / kg, a decrease of nearly 40%. What kind of negative factors lead to the roller coaster price of indium? At the "2019 SMM small Metal Industry Summit" hosted by SMM from April 2 to 3, 2019, Zhang Wen, vice president of Guangdong leading thin material Co., Ltd., made a comprehensive interpretation from the changes of global indium supply pattern and consumer demand. The future development of indium industry is also reviewed.
Production and supply of Indium
The content of indium in the earth's crust is 1 × 10 ~ 5%, and it is relatively dispersed, and no rich ore has been found so far. Global reserves of indium are estimated to be only 50,000 tons, of which 50 per cent are exploitable. Since no independent indium ore has been found, indium is produced by purifying waste zinc and tin with a recovery rate of about 50% to 60%. In this way, only 1.5-16000 tons of indium can be obtained. The countries rich in indium resources are China, Peru, the United States, Canada and Russia. The indium reserves in these countries account for 80.6% of the global indium reserves.
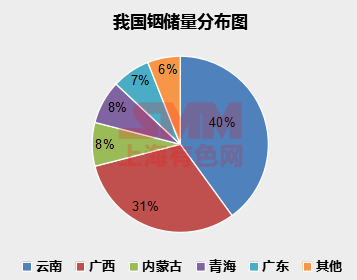
The reserves of indium resources in China rank first in the world. Indium in China is mainly associated with lead-zinc deposits and copper deposits. The reserves are 13014 tons, distributed in 15 provinces and regions. It is mainly concentrated in Yunnan (40% of the total indium reserves in China), Guangxi (31.4%), Inner Mongolia (8.2%), Qinghai (7.8%) and Guangdong (7%).
Output and demand of Indium
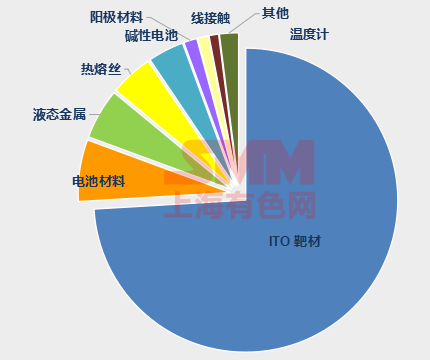
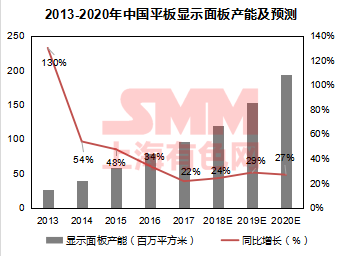
In the future, the demand for indium will mainly come from several aspects: the rapid growth of ITO production. ITO target production accounts for more than 80% of the global indium consumption, which has an important impact on the market status of indium. At present, due to the rapid growth of flat panel display demand, especially the rapid growth of flat panel display demand in China, it is expected that the demand for ITO will increase rapidly in the future. Development and application in new fields, such as computer chip, copper indium gallium selenium thin film solar cell and so on. Countries have strengthened their reserves of indium.
Consumption and demand of Indium
Consumption and demand of Indium-ITO Target:
From the downstream demand, 80% of indium is used in ITO target production. ITO film is deposited on all kinds of substrate materials as conductive electrode by magnetron sputtering, which is widely used in LCD, OLED, PDP, touch screen and other flat panel display devices. With the rapid growth of tablet computers and smart phone terminals, there is a strong demand for liquid crystal panels of different sizes, which drives the rapid expansion of ITO target demand, and finally stimulates the increase of indium demand. Benefiting from the development of downstream industries such as LCD televisions, smartphones and tablets, the global demand for ITO targets has grown steadily, exceeding 2000 tons in 2015, 1.7 times that of 2010, and is expected to exceed 3000 tons in 2020. At present, the global ITO target market is concentrated in Japan, South Korea, mainland China and other Asian countries, China accounts for more than 35% of the total global demand.
Consumption and demand of Indium-thin Film Solar Energy:
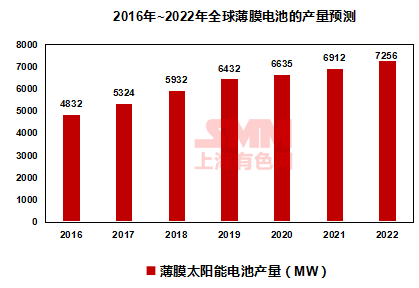
Copper indium gallium selenium CIGS battery has the advantages of stable performance, strong radiation resistance and low cost. It has a broad market prospect in the application of photovoltaic glass, ground power station and space microsatellite power supply. Global production of thin-film solar cells will continue to grow by 11.42% in 18 years, and domestic production will continue to grow by more than 10% in 18-20 because of its small base, according to the solar photovoltaic network. China is the largest consumer market for solar thin film targets.
Consumption and demand of Indium-LED
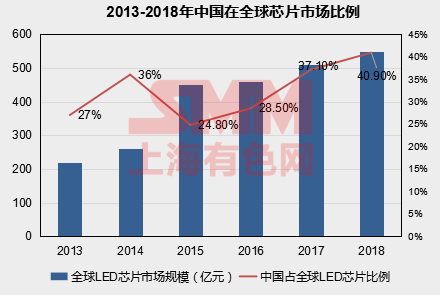
Indium is an important functional material in the field of LED, such as trimethyl indium, indium phosphide, low density ITO material and so on. The global LED lighting market continued to grow rapidly in 2016. From the downstream point of view, the general lighting market, which is the main direction of LED applications, has a global penetration rate of 36% in 2017. (Digitimes), expects permeability to exceed 40% in 2018, with a global market size of US $42 billion. The market is expected to grow rapidly by more than 10%.
Consumption and demand of Indium-Communication Field
Gallium arsenide and indium phosphide are the most important and widely used materials in the second generation of compound semiconductors after silicon single crystal. There is a huge application space in the field of microelectronics and optoelectronics, which is mainly used to make high-speed, high-frequency, high-power and other microelectronic devices and circuits. With the development of IT industry, the market space is expanding.
There are two main applications of InP as substrate materials: optoelectronic devices, including light sources (LED, LD) and detectors (PD, APD), which are mainly used in optical fiber communication systems. Electronic devices include high-speed and high-frequency microwave devices (MISFET, HEMT, HBT) and optoelectronic integrated circuits (OEIC). With the development of optical fiber communication, aerospace, national defense military, environmental protection and other industries and the support of the state to these industries, the demand for indium phosphide in the domestic market will continue to increase. 4G 5G: 3G will be phased out and 4G penetration will increase further, which is expected to reach 74.5% in 2019. The commercial use of 5G can be expected in the next few years, which requires higher communication materials for advanced communication equipment, and brings broad prospects for the future development of high frequency communication materials industry.
Development Prospect of Indium Industry
In the future supply situation, from the absolute level of indium price at present, it returns to a lower level, which is close to the average production cost of enterprises using secondary materials. Moreover, with the strengthening of environmental protection, whether the use of primary ore zinc smelting or the use of secondary materials zinc smelting, environmental protection costs are rising, the relevant enterprises to enter the threshold to improve, the future competition of production enterprises to further intensify. On the other hand, the domestic indium consumption will gradually increase with the development of domestic target manufacturing. However, the historical inventory of indium is too high and needs to be adjusted and digested slowly by the market.
In the future, with the further development of China's flat panel display industry and the localization of materials, ITO targets and flat panel displays will be gradually transferred to China. China has become the main supplier and consumer of indium. From a global point of view, indium consumption continues to increase year by year, the main contribution is still in the ITO field, and the global target production is still growing at an annual rate of 3% to 5%.
With the impact of Chinese manufacturers on the upstream of household appliances, China is growing into the world's largest liquid crystal panel production base. In addition, with the arrival of 5G, the future consumption of indium compounds will also increase year by year, coupled with the continuous development of photovoltaic technology and the inevitable requirements of the environment for clean energy, the future photovoltaic field is likely to become the fastest growing field of consumption.
Summary of the future development trend of indium industry: the development of flat panel display, LED, copper indium gallium selenium thin film solar energy, semiconductors and other emerging industries will stimulate the rapid increase of indium demand. It is expected that the demand for indium is expected to maintain a growth rate of 10% to 15% in the next five years. However, the industry is facing the pressure of de-inventory, and there are some uncertainties in the price of indium in the future.
Scan QR code, apply to join SMM metal exchange group, please indicate company + name + main business