SHANGHAI, Feb 10 (SMM) - This is a roundup of China's metals weekly inventory as of February 10.
Aluminium Ingot and Billet Inventories Diverge
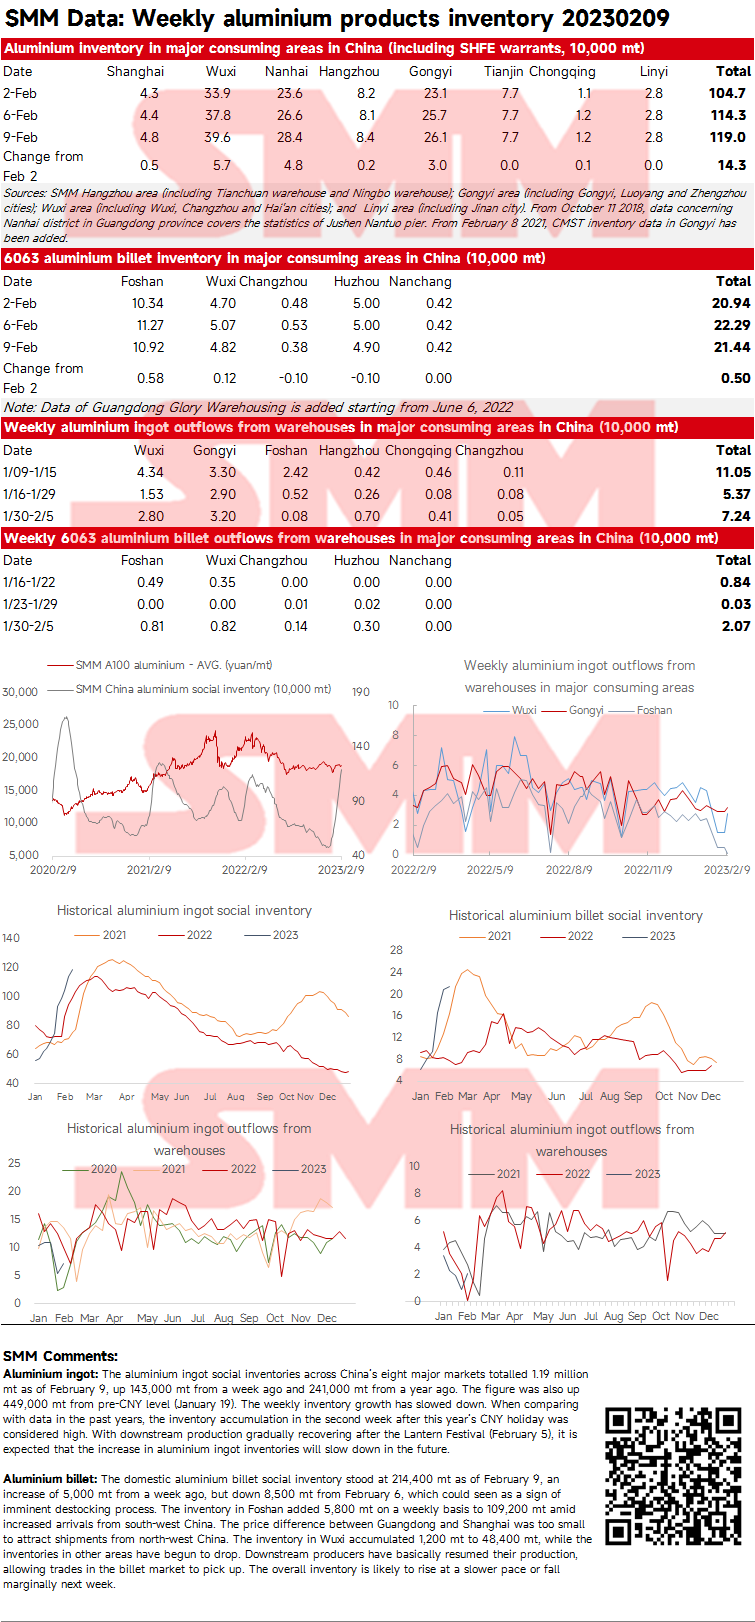
Aluminium ingot: The aluminium ingot social inventories across China’s eight major markets totalled 1.19 million mt as of February 9, up 143,000 mt from a week ago and 241,000 mt from a year ago. The figure was also up 449,000 mt from pre-CNY level (January 19). The weekly inventory growth has slowed down. When comparing with data in the past years, the inventory accumulation in the second week after this year’s CNY holiday was considered high. With downstream production gradually recovering after the Lantern Festival (February 5), it is expected that the increase in aluminium
ingot inventories will slow down in the future.
Aluminium billet: The domestic aluminium billet social inventory stood at 214,400 mt as of February 9, an increase of 5,000 mt from a week ago, but down 8,500 mt from February 6, which could seen as a sign of imminent destocking process. The inventory in Foshan added 5,800 mt on a weekly basis to 109,200 mt amid increased arrivals from south-west China. The price difference between Guangdong and Shanghai was too small to attract shipments from north-west China. The inventory in Wuxi accumulated 1,200 mt to 48,400 mt, while the inventories in other areas have begun to drop. Downstream producers have basically resumed their production, allowing trades in the billet market to pick up. The overall inventory is likely to rise at a slower pace or fall marginally next week.
Copper Inventory in Major Chinese Markets Dipped 1,500 mt This Week
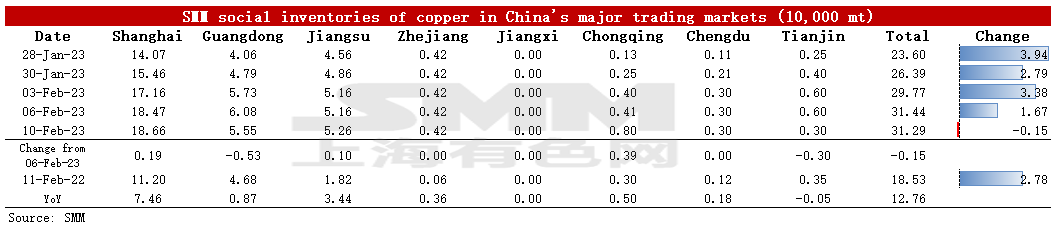
As of Friday February 10, copper stocks in mainstream markets decreased by 1,500 mt from Monday to 312,900 mt, while grew by 15,200 mt from a week earlier. The inventories increased 116,300 mt from pre-CNY holidays levels and were slightly higher than 113,100 mt in the same period last year. Since the end of December, the domestic inventory has accumulated for seven consecutive weeks, but the weekly accumulation rate has begun to decline this week. The market can keep an eye on whether the inflection point will come next week.
The inventory changes were mixed across China with the total inventory 127,600 mt higher than the 185,300 mt in the same period last year. The inventory was 74,600 mt higher than the same period last year in Shanghai, 8,700 mt higher in Guangdong, and 34,400 mt higher in Jiangsu. The inventory in Zhejiang exceeded the same period last year by 3,600 mt, and that in Chongqing was 5,000 mt more. Chengdu saw a 1,800 mt increase in inventory from the same period last year.
The inventory in Shanghai increased by 1,900 mt to 186,600 mt compared with Monday, and the inventory in Jiangsu increased by 1,000 mt to 52,600 mt compared with Monday. The inventory in east China continued to grow due to slow downstream recovery and the continued inflows of cargoes from north China. Inventory in Guangdong fell by 5,300 mt to 55,500 mt.
As far as we know, a large producer has been producing at capacity after Chinese New Year holidays while many downstream producers resumed production this week. This spurred the consumption in Guangdong, as reflected in the recent rapid growth in average daily shipments there. The decline in inventories in Tianjin was mainly due to the resumption of production by local downstream companies starting this week as well as the active transfer of cargoes from smelters in north China to east China. Overall, the market in south China was hectic while that in north China was lacklustre.
Shipments from smelters are expected to increase as the delivery of the SHFE front-month copper contract nears. But due to scarce arriving shipments of seaborne copper, SMM believes that total arrivals next week will increase only slightly. Downstream consumption, however, will increase driven by production resumption at more companies. On the whole, both supply and consumption will be picking up next week, and the inventory is likely to fall.
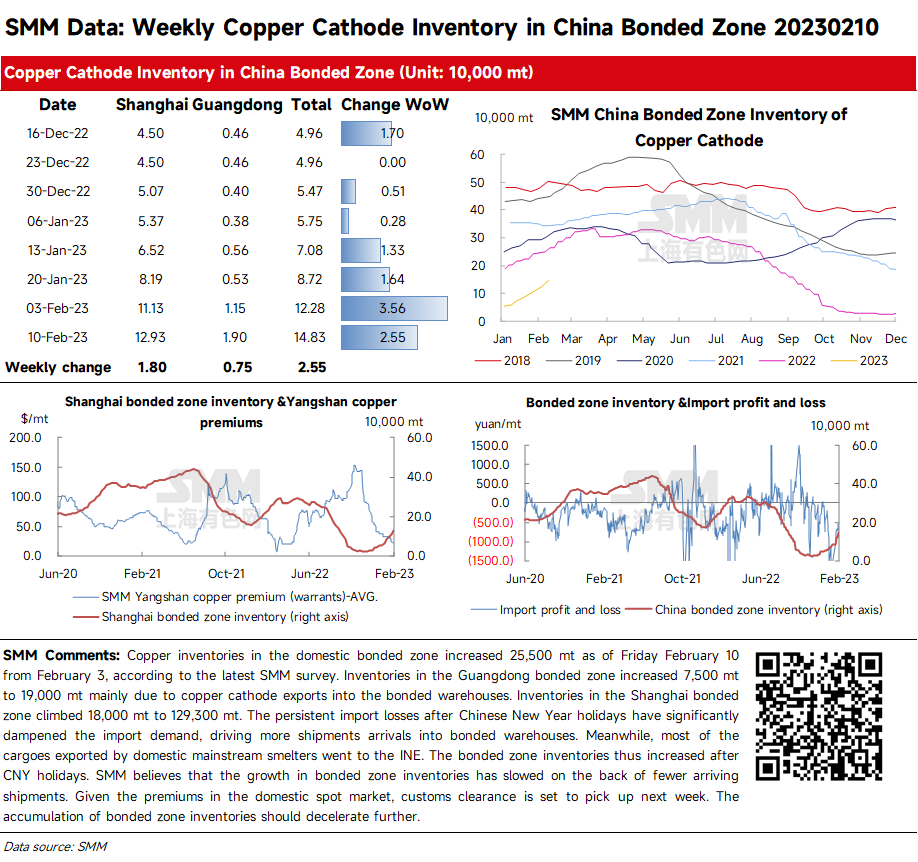
Copper Inventory in China Bonded Zone Grew 25,500 mt This Week
Copper inventories in the domestic bonded zone increased 25,500 mt as of Friday February 10 from February 3, according to the latest SMM survey. Inventories in the Guangdong bonded zone increased 7,500 mt to 19,000 mt mainly due to copper cathode exports into the bonded warehouses. Inventories in the Shanghai bonded zone climbed 18,000 mt to 129,300 mt.
The persistent import losses after Chinese New Year holidays have significantly dampened the import demand, driving more shipments arrivals into bonded warehouses. Meanwhile, most of the cargoes exported by domestic mainstream smelters went to the INE. The bonded zone inventories thus increased after CNY holidays.
SMM believes that the growth in bonded zone inventories has slowed on the back of fewer arriving shipments. Given the premiums in the domestic spot market, customs clearance is set to pick up next week. The accumulation of bonded zone inventories should decelerate further.
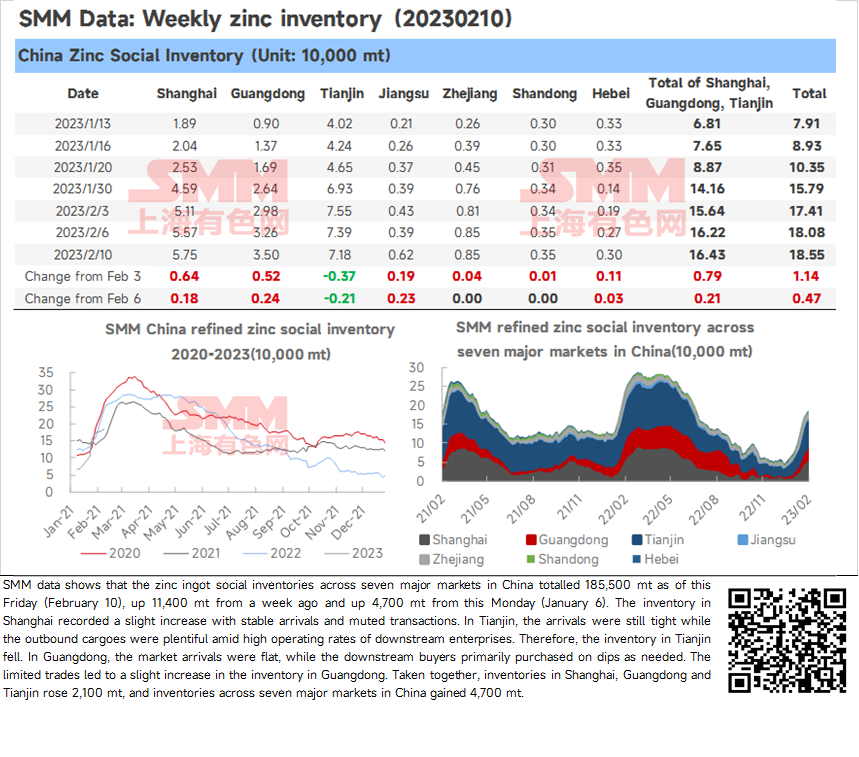
Zinc Ingot Social Inventory Gains 4,700 mt from this Monday
SMM data shows that the zinc ingot social inventories across seven major markets in China totalled 185,500 mt as of this Friday (February 10), up 11,400 mt from a week ago and up 4,700 mt from this Monday (January 6).
The inventory in Shanghai recorded a slight increase with stable arrivals and muted transactions. In Tianjin, the arrivals were still tight while the outbound cargoes were plentiful amid high operating rates of downstream enterprises. Therefore, the inventory in Tianjin fell. In Guangdong, the market arrivals were flat, while the downstream buyers primarily purchased on dips as needed. The limited trades led to a slight increase in the inventory in Guangdong.
Taken together, inventories in Shanghai, Guangdong and Tianjin rose 2,100 mt, and inventories across seven major markets in China gained 4,700 mt.
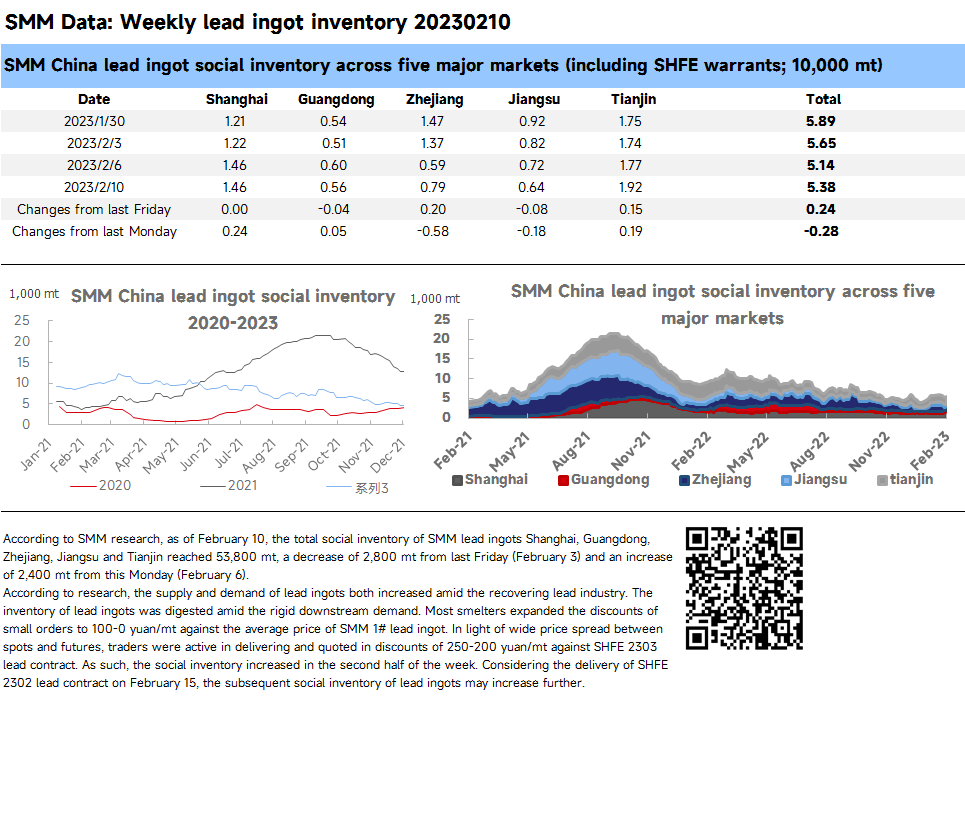
Subsequent Social Inventory of Lead Ingots may Increase Further amid Delivery of SHFE 2302 Lead Contract
According to SMM research, as of February 10, the total social inventory of SMM lead ingots Shanghai, Guangdong, Zhejiang, Jiangsu and Tianjin reached 53,800 mt, a decrease of 2,800 mt from last Friday (February 3) and an increase of 2,400 mt from this Monday (February 6).
According to research, the supply and demand of lead ingots both increased amid the recovering lead industry. The inventory of lead ingots was digested amid the rigid downstream demand. Most smelters expanded the discounts of small orders to 100-0 yuan/mt against the average price of SMM 1# lead ingot. In light of wide price spread between spots and futures, traders were active in delivering and quoted in discounts of 250-200 yuan/mt against SHFE 2303 lead contract. As such, the social inventory increased in the second half of the week. Considering the delivery of SHFE 2302 lead contract on February 15, the subsequent social inventory of lead ingots may increase further.
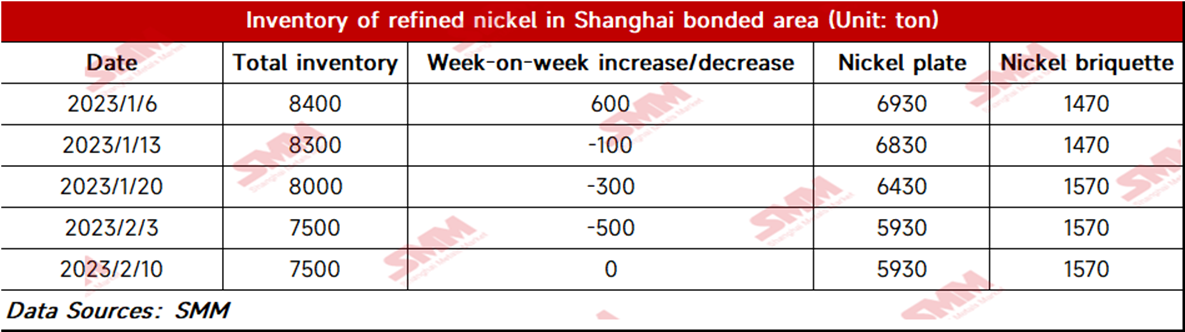
Spot Pure Nickel Imports Gain Profits amid the Rise in SHFE/LME Nickel Price Ratio
As of February 10, bonded zone inventory of nickel stood flat WoW at 7,500 mt. The inventory of nickel briquettes was 1,570 mt, and that of nickel plates was 5,930 mt. Spot imports gained profits this week with the rise in the SHFE/LME nickel price ratio. Some traders who lock in the price ratio have not yet cleared customs. According to SMM research, some nickel briquettes and nickel plates will arrive at ports next week.
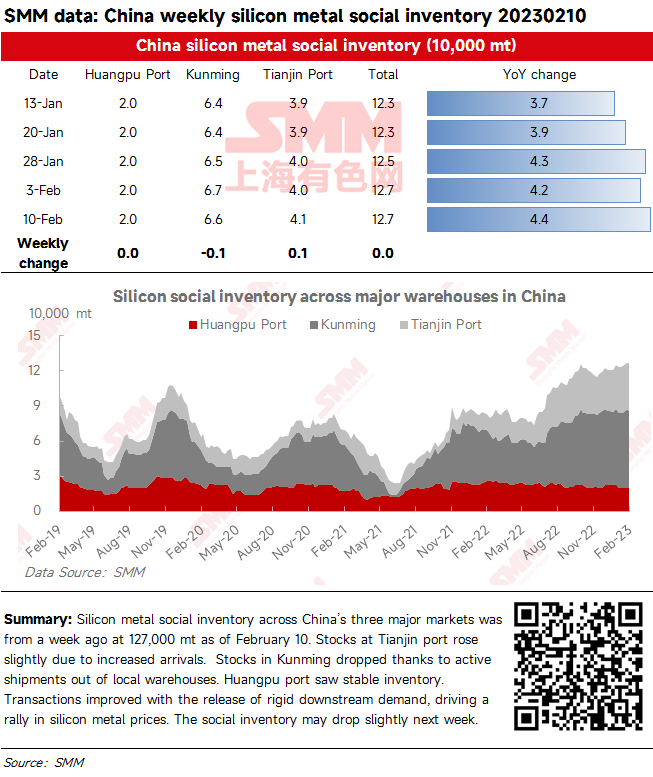
Silicon Metal Social Inventories Held Stable as Increase in One Region Was Offset by Decline in Another Region
Silicon metal social inventory across China’s three major markets was from a week ago at 127,000 mt as of February 10. Stocks at Tianjin port rose slightly due to increased arrivals. Stocks in Kunming dropped thanks to active shipments out of local warehouses. Huangpu port saw stable inventory. Transactions improved with the release of rigid downstream demand, driving a rally in silicon metal prices. The social inventory may drop slightly next week.
Nickel Ore Inventories at Chinese Ports Fall 267,000 wmt WoW
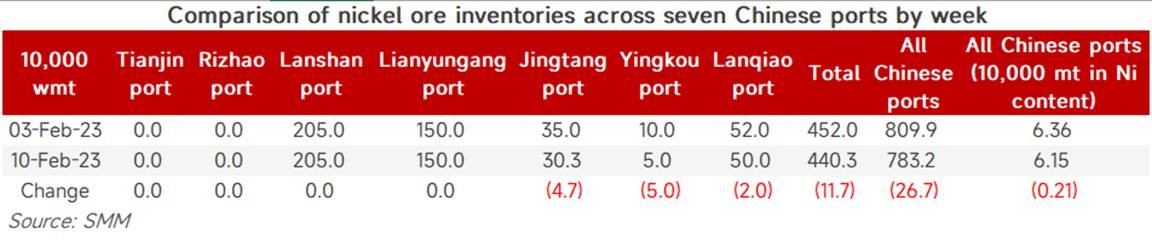
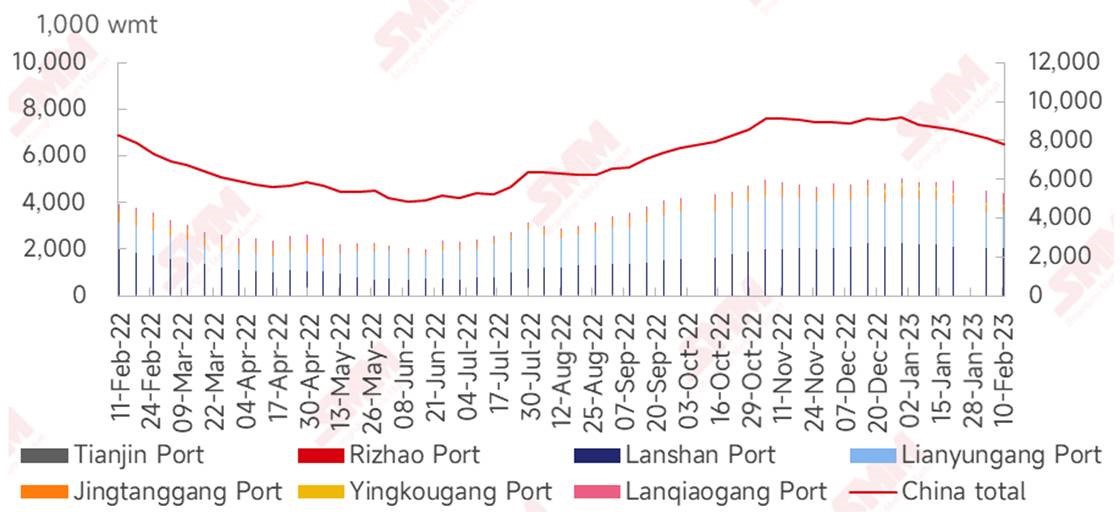
As of February 10, the nickel ore inventory at Chinese ports dipped 267,000 wmt from a week earlier to 7.83 million wmt. The total Ni content dropped 2,000 mt to about 62,000 mt. The port inventory of nickel ore across seven major Chinese ports stood at 4.4 million wmt, 117,000 wmt lower than the previous week. SMM believes that the output of high-grade NPI will grow MoM in February, thus the consumption of nickel ore will increase. Ore shipments from the Philippines were limited during the rainy season in the country. It is expected that the port inventory of laterite nickel ore will maintain a downward trend.