SHANGHAI, Sep 2 (SMM) - This is a roundup of China's metals weekly inventory as of September 2.
SMM Aluminium Ingot and Billet Social Inventory as of September 1
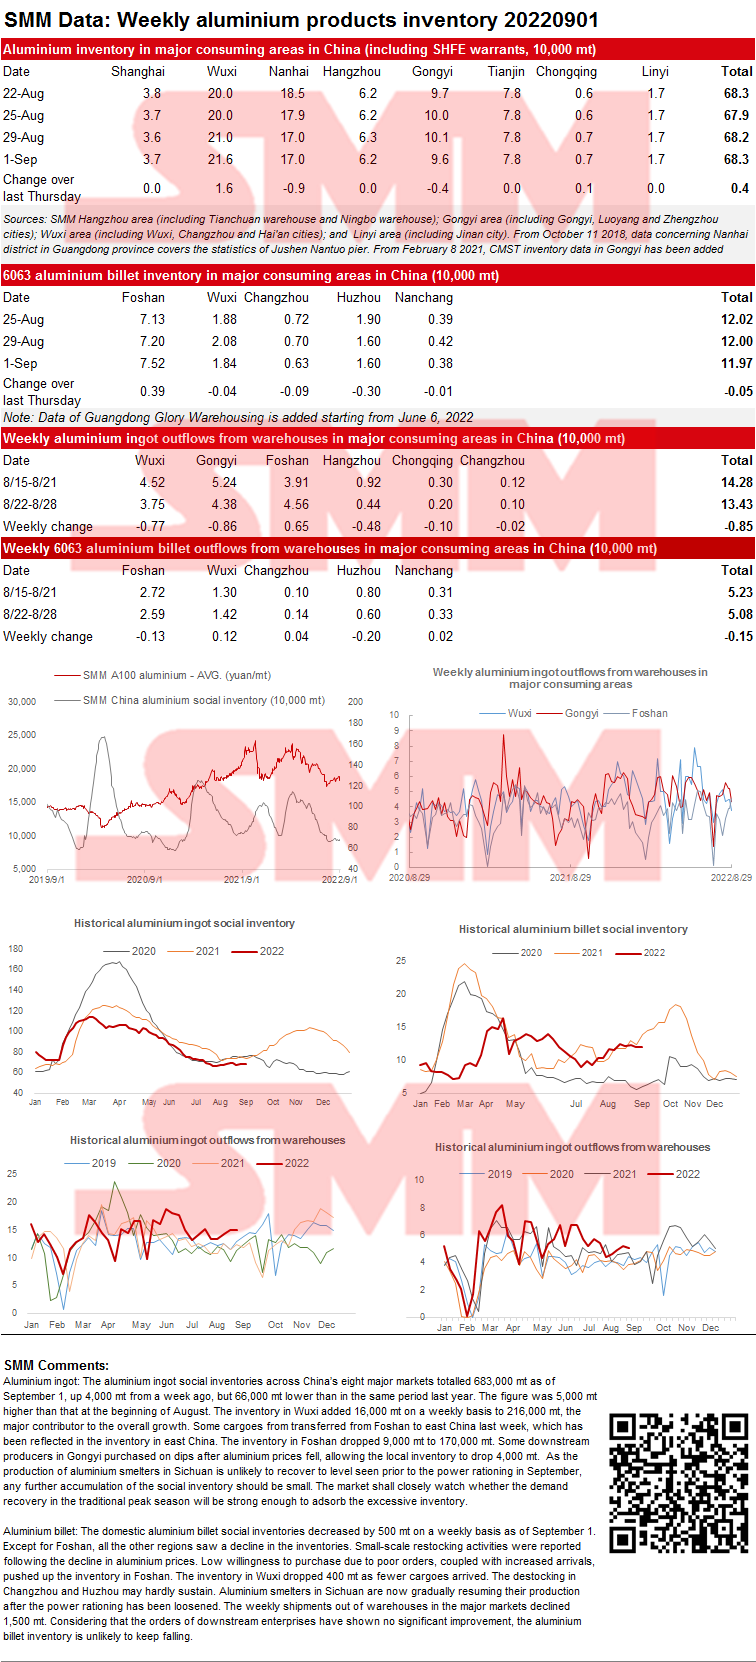
Aluminium ingot: The aluminium ingot social inventories across China’s eight major markets totalled 683,000 mt as of September 1, up 4,000 mt from a week ago, but 66,000 mt lower than in the same period last year. The figure was 5,000 mt higher than that at the beginning of August. The inventory in Wuxi added 16,000 mt on a weekly basis to 216,000 mt, the major contributor to the overall growth. Some cargoes from transferred from Foshan to east China last week, which has been reflected in the inventory in east China. The inventory in Foshan dropped 9,000 mt to 170,000 mt. Some downstream producers in Gongyi purchased on dips after aluminium prices fell, allowing the local inventory to drop 4,000 mt. As the production of aluminium smelters in Sichuan is unlikely to recover to level seen prior to the power rationing in September, any further accumulation of the social inventory should be small. The market shall closely watch whether the demand recovery in the traditional peak season will be strong enough to adsorb the excessive inventory.
Aluminium billet: The domestic aluminium billet social inventories decreased by 500 mt on a weekly basis as of September 1. Except for Foshan, all the other regions saw a decline in the inventories. Small-scale restocking activities were reported following the decline in aluminium prices. Low willingness to purchase due to poor orders, coupled with increased arrivals, pushed up the inventory in Foshan. The inventory in Wuxi dropped 400 mt as fewer cargoes arrived. The destocking in Changzhou and Huzhou may hardly sustain. Aluminium smelters in Sichuan are now gradually resuming their production after the power rationing has been loosened. The weekly shipments out of warehouses in the major markets declined 1,500 mt. Considering that the orders of downstream enterprises have shown no significant improvement, the aluminium billet inventory is unlikely to keep falling.
Social Inventory of Lead Ingot Further Increase as Supply Increased More Than Demand after Power Rationing Ended
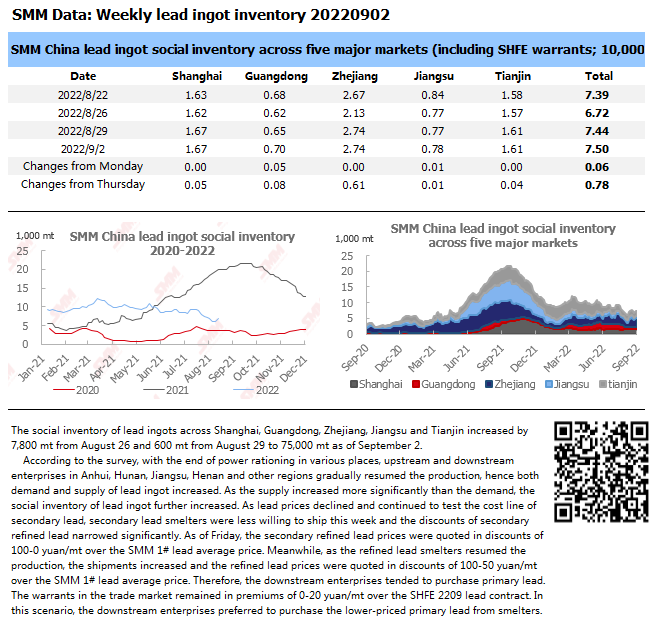
The social inventory of lead ingots across Shanghai, Guangdong, Zhejiang, Jiangsu and Tianjin increased by 7,800 mt from August 26 and 600 mt from August 29 to 75,000 mt as of September 2.
According to the survey, with the end of power rationing in various places, upstream and downstream enterprises in Anhui, Hunan, Jiangsu, Henan and other regions gradually resumed the production, hence both demand and supply of lead ingot increased. As the supply increased more significantly than the demand, the social inventory of lead ingot further increased. As lead prices declined and continued to test the cost line of secondary lead, secondary lead smelters were less willing to ship this week and the discounts of secondary refined lead narrowed significantly. As of Friday, the secondary refined lead prices were quoted in discounts of 100-0 yuan/mt over the SMM 1# lead average price. Meanwhile, as the refined lead smelters resumed the production, the shipments increased and the refined lead prices were quoted in discounts of 100-50 yuan/mt over the SMM 1# lead average price. Therefore, the downstream enterprises tended to purchase primary lead. The warrants in the trade market remained in premiums of 0-20 yuan/mt over the SHFE 2209 lead contract. In this scenario, the downstream enterprises preferred to purchase the lower-priced primary lead from smelters.
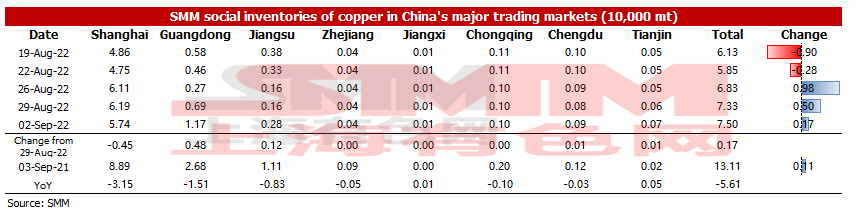
Copper Inventory across Major Chinese Markets Added 1,700 mt from Monday
As of Friday September 2, SMM copper inventory across major Chinese markets stood at 75,000 mt, up 1,700 mt from Monday and 6,700 mt from last Friday. Compared with Monday's data, copper inventory in most regions across China increased except that in Shanghai. The total inventory fell 56,100 mt compared with the same period last year when the data was 131,100 mt. Among them, the inventory in Shanghai dropped 31,500 mt, and that in Guangdong dipped 15,100 mt.
In detail, the inventory in Shanghai dipped 4,500 mt to 57,400 mt because the arrival of imported copper decreased from mid-week, and that in Guangdong increased 4,800 mt to 11,700 mt as arrivals of both imported and domestic copper rose significantly. Inventories in Jiangsu, Chongqing and Tianjin all grew slightly due to increased arrivals of domestic copper.
Looking forward, it is expected that the arrival of domestic copper will remain stable, while the arrival of imported copper is uncertain and needs to be closely monitored. It is expected that the consumption of copper cathode will improve next week as copper prices have continued to decline and the spread between the copper cathode and copper scrap has also narrowed significantly, hence the inventory next week may fall again.
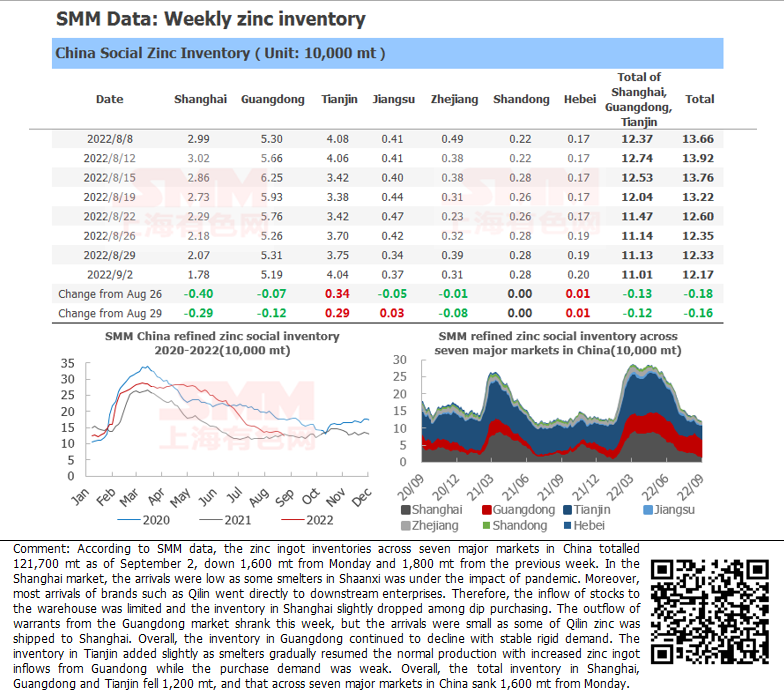
Zinc ingot social inventory across seven major markets in China down 1,600 mt from Monday
According to SMM data, the zinc ingot inventories across seven major markets in China totalled 121,700 mt as of September 2, down 1,600 mt from Monday and 1,800 mt from the previous week. In the Shanghai market, the arrivals were low as some smelters in Shaanxi was under the impact of pandemic. Moreover, most arrivals of brands such as Qilin went directly to downstream enterprises. Therefore, the inflow of stocks to the warehouse was limited and the inventory in Shanghai slightly dropped among dip purchasing. The outflow of warrants from the Guangdong market shrank this week, but the arrivals were small as some of Qilin zinc was shipped to Shanghai. Overall, the inventory in Guangdong continued to decline with stable rigid demand. The inventory in Tianjin added slightly as smelters gradually resumed the normal production with increased zinc ingot inflows from Guandong while the purchase demand was weak. Overall, the total inventory in Shanghai, Guangdong and Tianjin fell 1,200 mt, and that across seven major markets in China sank 1,600 mt from Monday.
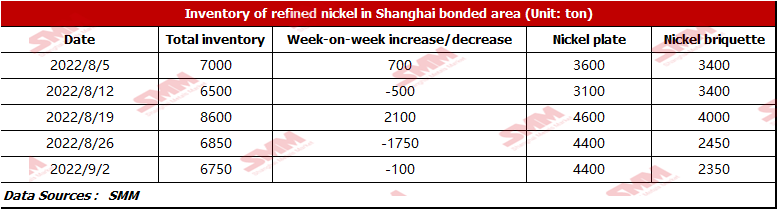
Bonded Zone Inventory of Nickel Briquette Dipped 100 mt WoW, while that of Nickel Plate Stayed Unchanged
According to SMM research, the bonded zone inventory stood at 6,750 mt this week. The inventory of nickel briquette was 2,350 mt, down 100 mt WoW, and that of nickel plate was 4,400 mt, flat from the previous week. The slight decline in bonded zone inventory this week was caused by the import losses of pure nickel amid the weakening of SHFE nickel prices.
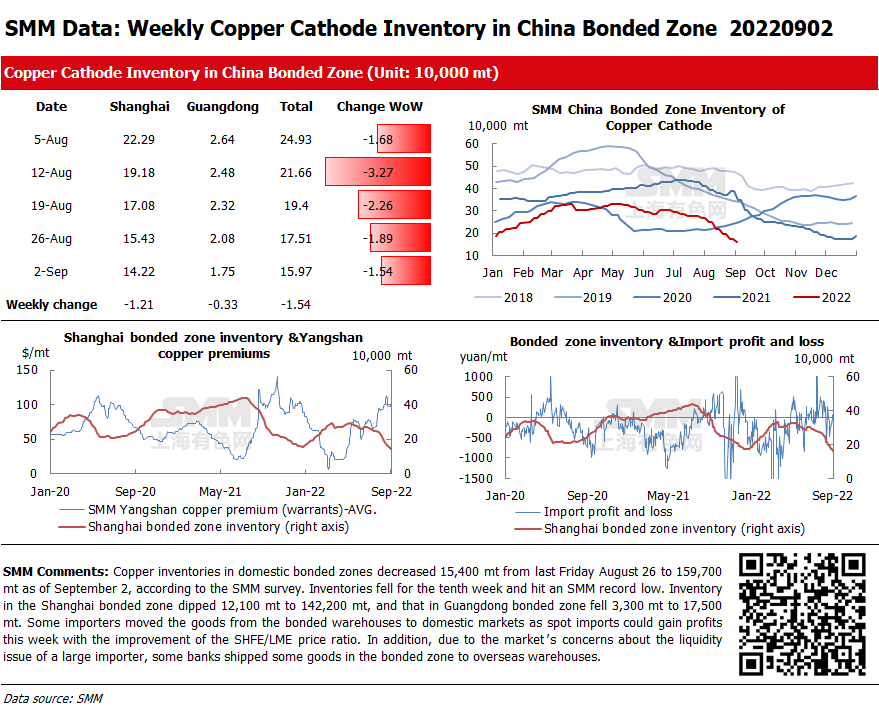
Copper Inventories in Domestic Bonded Zones Dipped 15,400 mt from August 26
Copper inventories in domestic bonded zones decreased 15,400 mt from last Friday August 26 to 159,700 mt as of September 2, according to the SMM survey. Inventories fell for the tenth week and hit an SMM record low. Inventory in the Shanghai bonded zone dipped 12,100 mt to 142,200 mt, and that in Guangdong bonded zone fell 3,300 mt to 17,500 mt. Some importers moved the goods from the bonded warehouses to domestic markets as spot imports could gain profits this week with the improvement of the SHFE/LME price ratio. In addition, due to the market’s concerns about the liquidity issue of a large importer, some banks shipped some goods in the bonded zone to overseas warehouses.
Nickel Ore Inventories at Chinese Ports up 300,000 wmt WoW
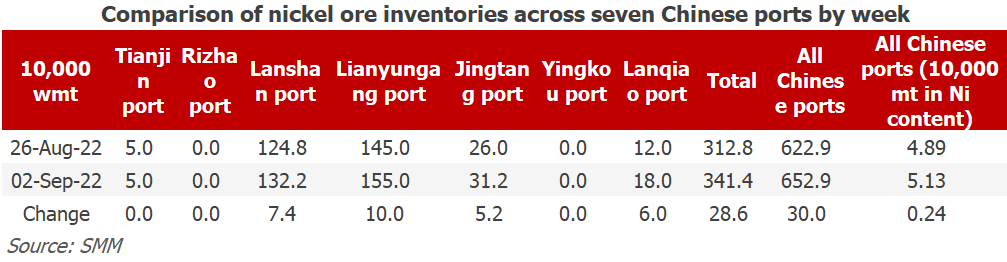
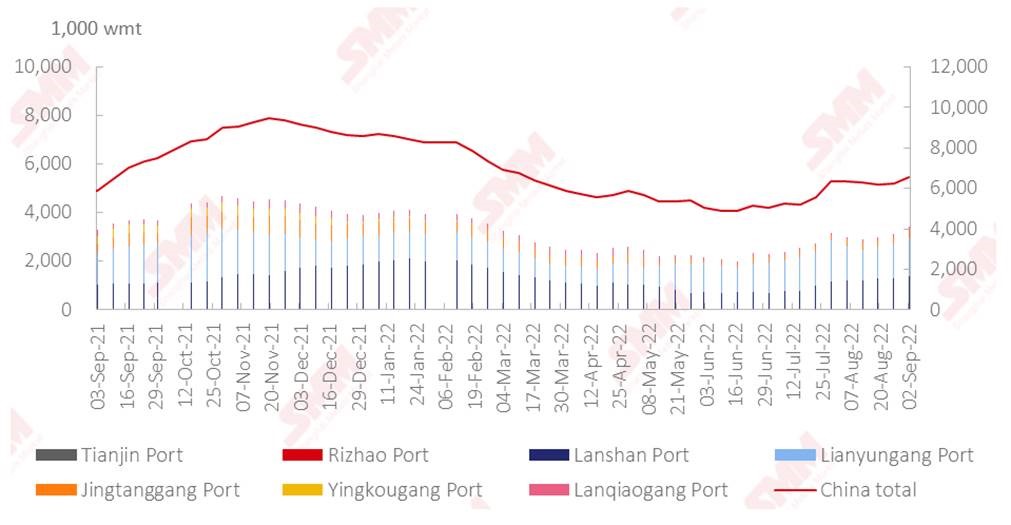
As of September 2, port inventories of nickel ore in China added 300,000 wmt to 6.53 million wmt compared with last week. The total Ni content stood at 51,300 mt. Port inventory of nickel ore across seven major Chinese ports stood at 3.41 million wmt, 286,000 wmt higher than last week. At present, the supply and demand of nickel ore still remain weak. Mines held their prices firm, and the transactions were sluggish. And stainless steel and NPI markets were slack, and their output was still low, slowing down the consumption of ore. NPI prices bear huge pressure from the oversupply, and the plants are less willing to restock even though the rainy season is coming. It is expected that the rise of port inventory of nickel ore will be limited.