China Steel Rebar Inventory Down 36,100 mt on Week

Publié: Aug 13, 2021 13:13
Inventories of rebar across Chinese steelmakers and social warehouses stood at 11.48 million mt as of August 12, down 36,100 mt or 0.31% from a week ago. Stocks are up 325,300 mt or 2.94% from a year earlier.

SHANGHAI, Aug 13 (SMM) - The rebar output increased slightly by 0.97% week on week, and apparent demand of rebar rebounded significantly by 9.37% on the week.

Inventories of rebar across Chinese steelmakers and social warehouses stood at 11.48 million mt as of August 12, down 36,100 mt or 0.31% from a week ago. Stocks are up 325,300 mt or 2.94% from a year earlier.

Despite the higher output, the increase in the in-plant rebar stocks narrowed significantly this week, indicating that the in-plant inventories were being transferred to social warehouses more rapidly.

Inventories at Chinese steelmakers rose 42,700 mt or 1.23% on the week and stood at 3.51 million mt. Stocks are up 37,900 mt or 1.09% from a year earlier.
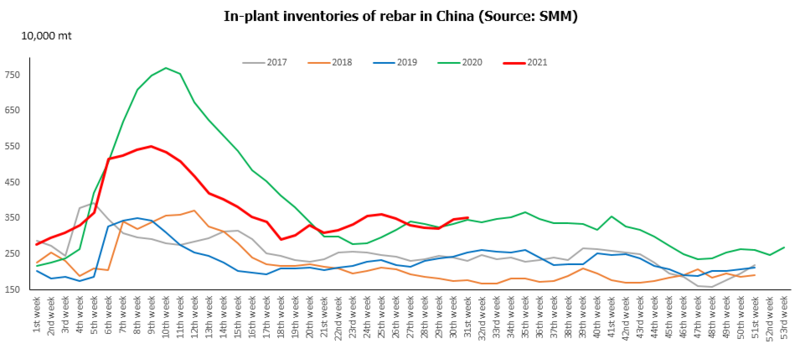
Futures and spot prices both rebounded this week boosted by the funds, and the end demand grew slightly. Speculative demand was also tense. Social inventories of rebar fell more rapidly as daily transactions picked up.

Inventories at social warehouses declined 78,800 mt or 0.98% on the week and stood at 7.97 million mt, up 287,000 mt or 3.74% from a year ago.
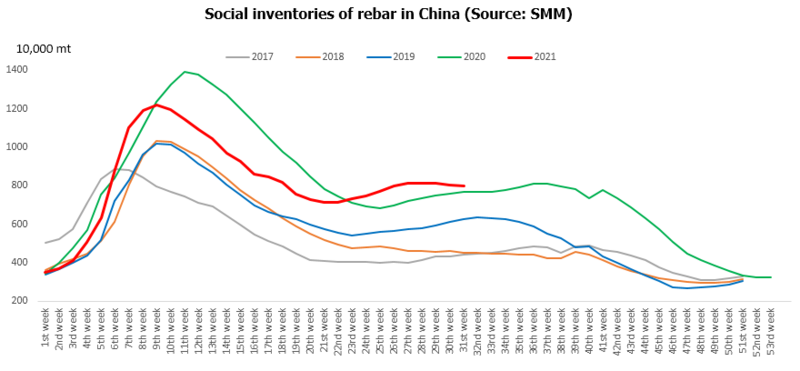
Supply and demand were still declining in the short term. Although the crude still capacities were under the production cut policy, the decrease in supply was narrowing. Fewer plants were reducing production against high profits and the approaching peak season. Crude steel output is likely to fluctuate or rebound.

The price trend will be dominated by the demand expectations. Steel prices rebounded and stabilised this week, showing that the end demand rebounded, and the purchase by end users increased. Most speculators were wait and see, but some had entered the market. The restocking demand of middlemen and downstream users for the peak season started to grow in mid-August. If the midstream and downstream demand continues to grow, steel prices may fluctuate higher. However, the increase in the steel output may be interfered by the pandemic, typhoons, and the heavy rainfall in the middle and lower reaches of the Yangtze River.  

In the long term, the consumption may not stand high in the peak season, but the prices may not see a sharp drop. Steel prices are likely to remain volatile at high levels and rise higher in October and November. On the supply side, the production cut policy for crude steel may be fully implemented in H2 2021. Considering the profits and supply, the overall decrease in the production may be slighter than market expectations. However, the supply is still expected to be tight. The most serious production restriction is expected to be implemented in the heating season in Q4 2021.

On the demand side, real estate demand will fall in the second half of the year, but the decline will be relatively mild. The sales in the real estate market performed strongly in H1 2021. The sales increase was narrowing, but under the high turnover of housing enterprises, construction will soon be started on the centralised supplied land. Moreover, the investment in real estates is unlikely to fall sharply, so the steel demand by real estate market will decline moderately, showing a certain degree of resilience. As for the infrastructure construction, the special bond issuance of local governments may be accelerated in H2 2021, based on the instructions to reasonably control the investment and local bond issuance progress from the CPC Political Bureau meeting. Therefore, although the growth rate of construction steel demand in the second half of the year will slow down, it will still maintain a certain degree of resilience and will not stall and decline. In addition, the demand may peak in October and November, during which the supply might be tight due to the production restriction.  

The supply may rebound in the short term, and steel prices will continue to fluctuate at high levels amid recovered demand. The market needs to beware of the sharp surge and fall in the short term.


Déclaration sur la source des données : À l'exception des informations publiques, toutes les autres données sont traitées par SMM sur la base d'informations publiques, d'échanges avec le marché et en s'appuyant sur le modèle de base de données interne de SMM. Ils sont fournis à titre indicatif uniquement et ne constituent pas des recommandations décisionnelles.

Pour toute demande d'information ou pour en savoir plus, veuillez contacter : lemonzhao@smm.cn
Pour plus d'informations sur l'accès à nos rapports de recherche, veuillez contacter :service.en@smm.cn
Actualités Connexes
L'Australie réexamine les droits antidumping sur l'acier galvanisé en provenance d'Inde, de Malaisie et du Vietnam dans un contexte de préoccupations liées au zinc
11 Sep 2026 18:30
L'Australie réexamine les droits antidumping sur l'acier galvanisé en provenance d'Inde, de Malaisie et du Vietnam dans un contexte de préoccupations liées au zinc
Lire la suite
L'Australie réexamine les droits antidumping sur l'acier galvanisé en provenance d'Inde, de Malaisie et du Vietnam dans un contexte de préoccupations liées au zinc
Le 9 septembre 2026, l'Australie a lancé son deuxième réexamen au titre du crépuscule des mesures antidumping visant les tôles d'acier galvanisé originaires d'Inde, de Malaisie et du Vietnam, et a ouvert séparément un réexamen au titre du crépuscule des mesures compensatoires sur les importations en provenance d'Inde. Le réexamen couvre la période juillet 2025-juin 2026, le rapport final étant attendu pour le 11 février 2027. L'acier galvanisé étant le principal secteur d'utilisation finale du zinc, ces mesures affectent directement les coûts d'exportation et la compétitivité, avec un impact potentiel sur la demande intérieure de zinc et la chaîne d'approvisionnement en Australie. Le maintien des droits offrirait une certaine protection aux capacités nationales de production d'acier et de revêtement, tandis que leur suppression pourrait accroître les importations à bas prix et affecter la consommation régionale de zinc. L'issue finale reste soumise à la décision des autorités.
11 Sep 2026 18:30
Le projet d'expansion de 200 millions de dollars de JCC Hongyuan Copper vise à porter la capacité à 550 000 tonnes d'ici 2027
7 Sep 2026 15:43
Le projet d'expansion de 200 millions de dollars de JCC Hongyuan Copper vise à porter la capacité à 550 000 tonnes d'ici 2027
Lire la suite
Le projet d'expansion de 200 millions de dollars de JCC Hongyuan Copper vise à porter la capacité à 550 000 tonnes d'ici 2027
Le projet d'expansion de 300 000 tonnes par an de cathodes de cuivre de JCC Hongyuan Copper, filiale de Jiangxi Copper Corporation, est entré le 4 septembre dans la phase de consultation publique préalable à l'approbation de son étude d'impact environnemental, avec un investissement total d'environ 1,416 milliard de yuans. Le projet devrait démarrer en septembre 2026 et s'achever en décembre 2027. Une fois terminé, la capacité totale de JCC Hongyuan passera de 250 000 à 550 000 tonnes.
7 Sep 2026 15:43
Le yen japonais s'apprécie, l'USD/JPY passe sous 159 dans un contexte de spéculation sur une intervention
3 Sep 2026 19:00
Le yen japonais s'apprécie, l'USD/JPY passe sous 159 dans un contexte de spéculation sur une intervention
Lire la suite
Le yen japonais s'apprécie, l'USD/JPY passe sous 159 dans un contexte de spéculation sur une intervention
[SMM Express Métaux Précieux] Le yen japonais a fortement grimpé lors de la séance de mercredi, l'USD/JPY passant sous 159 et clôturant en baisse de 0,92 % à 158,69, alimentant les spéculations sur une intervention monétaire japonaise. L'indice du dollar a également fortement reculé, un environnement de dollar plus faible soutenant les métaux précieux.
3 Sep 2026 19:00
China Steel Rebar Inventory Down 36,100 mt on Week - Shanghai Metals Market (SMM)

