[SMM thread] the road of accumulation is not over, and the upward road of steel price is not over.

Publié: Jul 16, 2020 17:47
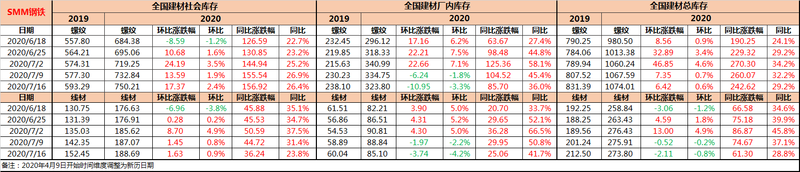
As of July 16, the country's total inventory of building materials was 10.7401 million tons, with a month-on-month ratio of + 0.6%, compared with the same period last year. Seasonal interference has not faded, central China, East China, southwest and other areas are still shrouded in overcast and rainy weather, terminal demand continues to be suppressed, so the thread inventory is still in a state of accumulation. However, after South China took the lead in "getting rid of difficulties", the strong replenishment of local demand is an important argument to prove the objective existence of the demand for quick work. The urgent demand for work is more urgent than in previous years, and the terminal just needs a good year-on-year performance, which is an important reason why the current year-on-year increase in inventory continues to narrow. (this week, the year-on-year increase of thread pool narrowed by 3%.


SMM7 March 16:

As of July 16, the country's total inventory of building materials was 10.7401 million tons, with a month-on-month ratio of + 0.6%, compared with the same period last year. Seasonal interference has not faded, central China, East China, southwest and other areas are still shrouded in overcast and rainy weather, terminal demand continues to be suppressed, so the thread inventory is still in a state of accumulation. However, after South China took the lead in "getting rid of difficulties", the strong replenishment of local demand is an important argument to prove the objective existence of the demand for quick work. The urgent demand for work is more urgent than in previous years, and the terminal just needs a good year-on-year performance, which is an important reason why the current inventory growth continues to narrow year-on-year (this week, the thread pool growth rate narrowed by 3 percentage points year-on-year).

Table 1: Overview of thread inventory
Source: SMM


Table 2: comparison of Thread inventory prices from 2018 to 2020
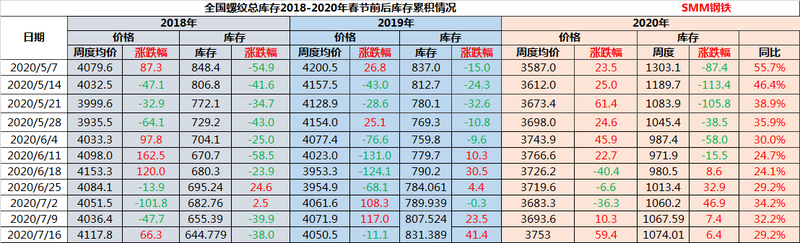
Note: due to the epidemic factors since 2020, due to the different opening times in different places, there is a certain error in the actual spot average price; the time dimension is the Gregorian calendar date.


Source: SMM

Specifically:

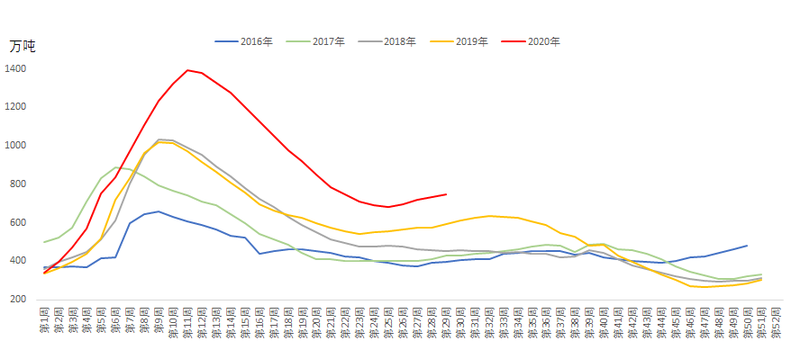
Social inventory of 7.5021 million tons, an increase of 173700 tons this week, + 2.4% month-on-month, + 26.9% year-on-year.

Under the background of a positive situation in the A-share bull market, the raw material side was led by the news side to rise first, driving the period snail to continue the strong situation in the past two weeks. The expectation of the spot market for the future is also improving, and the enthusiasm of traders to take goods has been significantly improved, accelerating the transfer of the factory warehouse to the social warehouse. While the terminal "steel needs" is "serious illness has not been cured", so the speed of accumulation has been accelerated.

Figure 1: an overview of the trend of threaded community library since 2016
Source: SMM

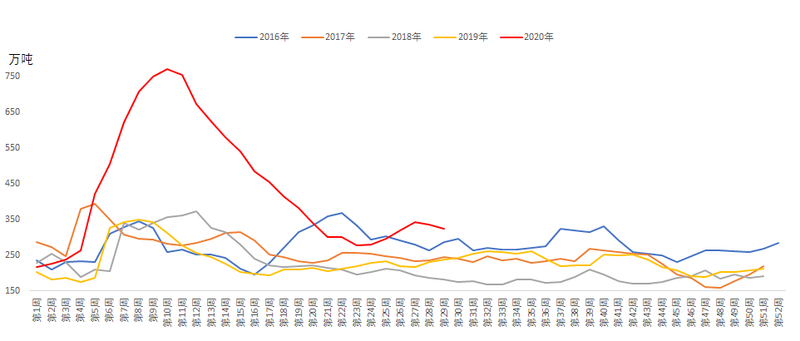
The inventory in the plant is 3.238 million tons, down 109500 tons this week,-3.3% month-on-month, + 36.0% year-on-year.

In addition to the market merchants' enthusiasm for taking goods driven by strong expectations, the decline in the output of steel mills is also an important reason for the decline in the factory warehouse. Under the dual pressure of high plant pressure and poor profitability, the overhaul and production reduction plans of steel mills have increased-according to SMM research, the planned rebar output of blast furnace steel mills in July decreased by 2% compared with the actual output in June, and the operating rate of electric furnace plants also dropped by about 11.52% compared with the same period in June.


Figure 2: an overview of the trend of thread factory warehouse from 2016 to now
Source: SMM

In the short term, the fundamentals of rebar are not unusual-the supply side is likely to maintain a small fluctuation at the current level, the demand side continues to be hit by precipitation, the road to rebar accumulation is not over, and steel prices are still in an awkward position of "neither up nor down". However, as more and more regions out of the "rainy season" haze, rush demand released as scheduled, thread fundamentals regained strong support, steel prices are expected to consolidate and continue to start.




Déclaration sur la source des données : À l'exception des informations publiques, toutes les autres données sont traitées par SMM sur la base d'informations publiques, d'échanges avec le marché et en s'appuyant sur le modèle de base de données interne de SMM. Ils sont fournis à titre indicatif uniquement et ne constituent pas des recommandations décisionnelles.

Pour toute demande d'information ou pour en savoir plus, veuillez contacter : lemonzhao@smm.cn
Pour plus d'informations sur l'accès à nos rapports de recherche, veuillez contacter :service.en@smm.cn
Actualités Connexes
L'Australie réexamine les droits antidumping sur l'acier galvanisé en provenance d'Inde, de Malaisie et du Vietnam dans un contexte de préoccupations liées au zinc
11 Sep 2026 18:30
L'Australie réexamine les droits antidumping sur l'acier galvanisé en provenance d'Inde, de Malaisie et du Vietnam dans un contexte de préoccupations liées au zinc
Lire la suite
L'Australie réexamine les droits antidumping sur l'acier galvanisé en provenance d'Inde, de Malaisie et du Vietnam dans un contexte de préoccupations liées au zinc
Le 9 septembre 2026, l'Australie a lancé son deuxième réexamen au titre du crépuscule des mesures antidumping visant les tôles d'acier galvanisé originaires d'Inde, de Malaisie et du Vietnam, et a ouvert séparément un réexamen au titre du crépuscule des mesures compensatoires sur les importations en provenance d'Inde. Le réexamen couvre la période juillet 2025-juin 2026, le rapport final étant attendu pour le 11 février 2027. L'acier galvanisé étant le principal secteur d'utilisation finale du zinc, ces mesures affectent directement les coûts d'exportation et la compétitivité, avec un impact potentiel sur la demande intérieure de zinc et la chaîne d'approvisionnement en Australie. Le maintien des droits offrirait une certaine protection aux capacités nationales de production d'acier et de revêtement, tandis que leur suppression pourrait accroître les importations à bas prix et affecter la consommation régionale de zinc. L'issue finale reste soumise à la décision des autorités.
11 Sep 2026 18:30
Le projet d'expansion de 200 millions de dollars de JCC Hongyuan Copper vise à porter la capacité à 550 000 tonnes d'ici 2027
7 Sep 2026 15:43
Le projet d'expansion de 200 millions de dollars de JCC Hongyuan Copper vise à porter la capacité à 550 000 tonnes d'ici 2027
Lire la suite
Le projet d'expansion de 200 millions de dollars de JCC Hongyuan Copper vise à porter la capacité à 550 000 tonnes d'ici 2027
Le projet d'expansion de 300 000 tonnes par an de cathodes de cuivre de JCC Hongyuan Copper, filiale de Jiangxi Copper Corporation, est entré le 4 septembre dans la phase de consultation publique préalable à l'approbation de son étude d'impact environnemental, avec un investissement total d'environ 1,416 milliard de yuans. Le projet devrait démarrer en septembre 2026 et s'achever en décembre 2027. Une fois terminé, la capacité totale de JCC Hongyuan passera de 250 000 à 550 000 tonnes.
7 Sep 2026 15:43
Le yen japonais s'apprécie, l'USD/JPY passe sous 159 dans un contexte de spéculation sur une intervention
3 Sep 2026 19:00
Le yen japonais s'apprécie, l'USD/JPY passe sous 159 dans un contexte de spéculation sur une intervention
Lire la suite
Le yen japonais s'apprécie, l'USD/JPY passe sous 159 dans un contexte de spéculation sur une intervention
[SMM Express Métaux Précieux] Le yen japonais a fortement grimpé lors de la séance de mercredi, l'USD/JPY passant sous 159 et clôturant en baisse de 0,92 % à 158,69, alimentant les spéculations sur une intervention monétaire japonaise. L'indice du dollar a également fortement reculé, un environnement de dollar plus faible soutenant les métaux précieux.
3 Sep 2026 19:00
[SMM thread] the road of accumulation is not over, and the upward road of steel price is not over. - Shanghai Metals Market (SMM)

