[SMM hot volume] spot price correction of hot rolls is about to seize the opportunity to get on the bus.

Publié: May 19, 2020 18:54

SMM Steel May 19, this week's mainstream market resources are expected to arrive at 96000 tons, 22000 tons less than last week.

Table 1: comparison of arrival in mainstream markets

Source: SMM Steel

Shipments continued to decline this week, mainly affected by the price difference between the north and the south and strong terminal demand in the north. According to SMM statistics, recently, the price of Lecong is only 60mur80 yuan / ton higher than that of Tangshan, while the price in Shanghai is 20 yuan / ton lower than that of Tangshan, the price difference between the north and the south has not yet been opened, and the resources in the north do not have the conditions to go south, so that the volume of goods from Shanghai and Lecong from the market continues to be on the low side. At the same time, the terminal demand in the north is strong, and most steel mills have increased the amount of terminal direct supply, resulting in a reduction in circulation resources in northern markets such as Tianjin.

Shanghai market: since the end of March, the arrival volume has remained low, the overall supply is tight, and with the recovery of demand, regional inventory is gradually reduced, coupled with a larger part of the resources in the market, the market negotiable resources are relatively limited, so traders are more willing to sell and push up the price, and the spot price rises accordingly.

In addition, it was expected that the delivery resources of Hengrun and Shagang and Angang would greatly suppress the market, but at present, Hengrun's resources are not entirely invested in the East China market, and some of them flow to the north and other regions. In addition, with regard to the delivery resources of Shagang and Angang, the early stage has been reflected in the price, and the subsequent impact on the market price is very limited, so it is expected that under the support of the continued lack of delivery and strong demand, the overall price still shows an upward trend. However, due to the recent pull up too fast, terminal procurement wait-and-see impact, short-term spot prices will be slightly adjusted.

Figure 1: comparison of arrival volume and spot price in Shanghai market

Source: SMM Steel

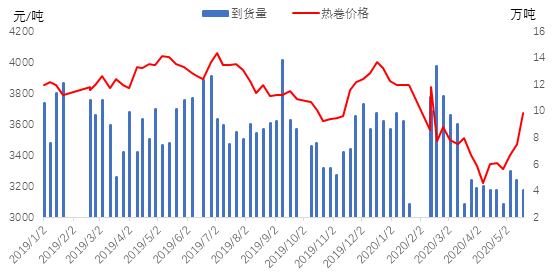
Lecong market: similarly, as can be seen from the chart below, since the end of March, the arrival volume of the market has been on the low side, coupled with the decline in the production of hot coils at Wangang, and the relative reduction of resources sent to Lecong, so the overall market supply continues to be tight. At the same time, the terminal demand has warmed up, the purchase volume has increased, and the regional inventory has gradually declined. Under the influence of the superimposed price difference between the north and the south, it is difficult for traders to get the goods, so their willingness to sell price increases gradually, and the spot price rises accordingly.

In addition, the risk point for South China now is that there is already a small profit space for selling volumes, and some traders with high inventories and tight funds may choose to sell some goods at low prices, somewhat suppressing spot prices in the market. But at present, it is understood that the total amount of this part is not expected to be large, the number of goods sold by superimposed traders is less, and the shipment at low prices is also more cautious, so there is only a small correction in the short term. The follow-up is expected to show an upward trend under the support of less arrival, until the price difference between the north and the south opens and the amount of resources arriving increases.

Figure 2: comparison between the volume of goods from the market and the spot price
 

Source: SMM Steel

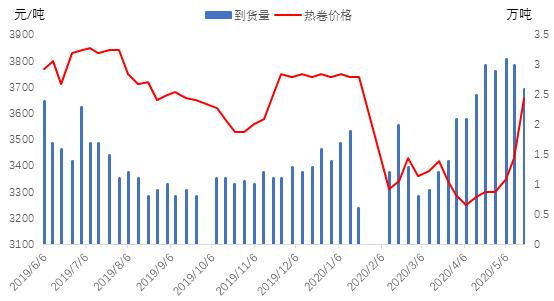
Tianjin market: the volume of goods in this market is still on the high side compared with the normal level. At the same time, according to SMM, the follow-up steel mills such as Baotou Steel and Shougang will gradually reach the market, at which time the pressure on the supply side of the market will further increase, and the spot price will be suppressed accordingly. As a result, the view of the market's anaemic late rally remains the same.

Figure 3: comparison of arrival volume and spot price in Tianjin market
Source: SMM Steel

 

Déclaration sur la source des données : À l'exception des informations publiques, toutes les autres données sont traitées par SMM sur la base d'informations publiques, d'échanges avec le marché et en s'appuyant sur le modèle de base de données interne de SMM. Ils sont fournis à titre indicatif uniquement et ne constituent pas des recommandations décisionnelles.

Pour toute demande d'information ou pour en savoir plus, veuillez contacter : lemonzhao@smm.cn
Pour plus d'informations sur l'accès à nos rapports de recherche, veuillez contacter :service.en@smm.cn
Actualités Connexes
L'Australie réexamine les droits antidumping sur l'acier galvanisé en provenance d'Inde, de Malaisie et du Vietnam dans un contexte de préoccupations liées au zinc
11 Sep 2026 18:30
L'Australie réexamine les droits antidumping sur l'acier galvanisé en provenance d'Inde, de Malaisie et du Vietnam dans un contexte de préoccupations liées au zinc
Lire la suite
L'Australie réexamine les droits antidumping sur l'acier galvanisé en provenance d'Inde, de Malaisie et du Vietnam dans un contexte de préoccupations liées au zinc
Le 9 septembre 2026, l'Australie a lancé son deuxième réexamen au titre du crépuscule des mesures antidumping visant les tôles d'acier galvanisé originaires d'Inde, de Malaisie et du Vietnam, et a ouvert séparément un réexamen au titre du crépuscule des mesures compensatoires sur les importations en provenance d'Inde. Le réexamen couvre la période juillet 2025-juin 2026, le rapport final étant attendu pour le 11 février 2027. L'acier galvanisé étant le principal secteur d'utilisation finale du zinc, ces mesures affectent directement les coûts d'exportation et la compétitivité, avec un impact potentiel sur la demande intérieure de zinc et la chaîne d'approvisionnement en Australie. Le maintien des droits offrirait une certaine protection aux capacités nationales de production d'acier et de revêtement, tandis que leur suppression pourrait accroître les importations à bas prix et affecter la consommation régionale de zinc. L'issue finale reste soumise à la décision des autorités.
11 Sep 2026 18:30
Le projet d'expansion de 200 millions de dollars de JCC Hongyuan Copper vise à porter la capacité à 550 000 tonnes d'ici 2027
7 Sep 2026 15:43
Le projet d'expansion de 200 millions de dollars de JCC Hongyuan Copper vise à porter la capacité à 550 000 tonnes d'ici 2027
Lire la suite
Le projet d'expansion de 200 millions de dollars de JCC Hongyuan Copper vise à porter la capacité à 550 000 tonnes d'ici 2027
Le projet d'expansion de 300 000 tonnes par an de cathodes de cuivre de JCC Hongyuan Copper, filiale de Jiangxi Copper Corporation, est entré le 4 septembre dans la phase de consultation publique préalable à l'approbation de son étude d'impact environnemental, avec un investissement total d'environ 1,416 milliard de yuans. Le projet devrait démarrer en septembre 2026 et s'achever en décembre 2027. Une fois terminé, la capacité totale de JCC Hongyuan passera de 250 000 à 550 000 tonnes.
7 Sep 2026 15:43
Le yen japonais s'apprécie, l'USD/JPY passe sous 159 dans un contexte de spéculation sur une intervention
3 Sep 2026 19:00
Le yen japonais s'apprécie, l'USD/JPY passe sous 159 dans un contexte de spéculation sur une intervention
Lire la suite
Le yen japonais s'apprécie, l'USD/JPY passe sous 159 dans un contexte de spéculation sur une intervention
[SMM Express Métaux Précieux] Le yen japonais a fortement grimpé lors de la séance de mercredi, l'USD/JPY passant sous 159 et clôturant en baisse de 0,92 % à 158,69, alimentant les spéculations sur une intervention monétaire japonaise. L'indice du dollar a également fortement reculé, un environnement de dollar plus faible soutenant les métaux précieux.
3 Sep 2026 19:00
[SMM hot volume] spot price correction of hot rolls is about to seize the opportunity to get on the bus. - Shanghai Metals Market (SMM)


