China's Prebaked Anode Production Slightly Declined in December 2024, Overall Demand Remained Stable [SMM Analysis]

Publicado: Jan 05, 2025 18:57 (GMT+8)
[SMM Analysis: China's Prebaked Anode Production Slightly Declined in December 2024, Overall Demand Remains Stable] In December, due to environmental protection-related controls, prebaked anode production in multiple regions experienced a slight decline. However, with the gradual release of capacity from new projects in north-west China and the resumption of production after maintenance by certain enterprises, the overall supply reduction was relatively small. On the demand side, the operating capacity of domestic aluminum smelters showed both increases and decreases, with overall production slightly rising. In January, aluminum enterprises are expected to maintain stable operating capacity, and prebaked anode demand is expected to remain relatively stable. Meanwhile, the unexpected price increase of prebaked anodes in January 2025 improved the industry's profitability. Additionally, some aluminum enterprises have recently been signing prebaked anode procurement contracts for 2025, indicating active demand. In summary, SMM expects prebaked anode enterprises to maintain high operating rates to meet market demand.

SMM, January 5:

According to SMM survey estimates, China's prebaked anode production in December 2024 was 1.9382 million mt, up 4.81% YoY and down 0.17% MoM. Among this, supporting prebaked anode production was 866,500 mt, and commercial prebaked anode production was 1.0717 million mt. The cumulative prebaked anode production in China for 2024 reached 23.6092 million mt, up 7.56% YoY.
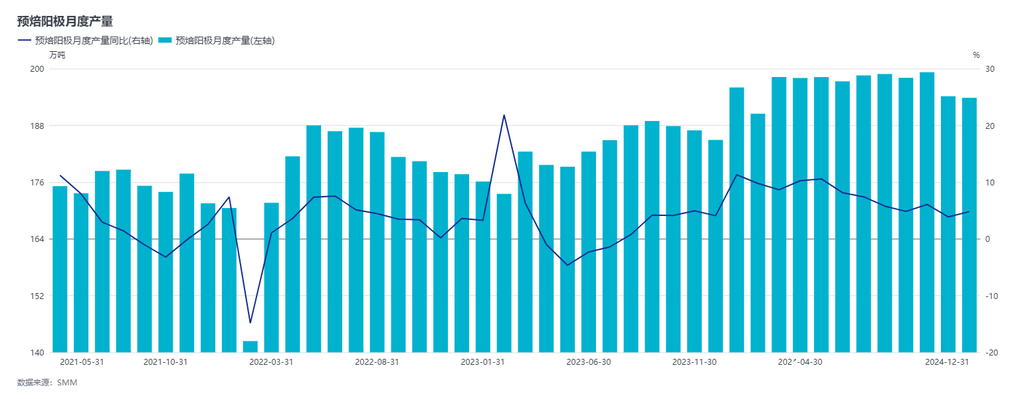
 

In December 2024, the operating conditions of domestic prebaked anode enterprises slightly declined. In some areas of Henan, Hebei, and Shandong, production was slightly reduced due to emergency controls for heavy pollution weather, with both calcination and baking processes affected to varying degrees. Additionally, some enterprises resumed operations after maintenance. SMM estimates that the industry's operating rate in December was 77.44%, down 0.13 percentage points MoM.

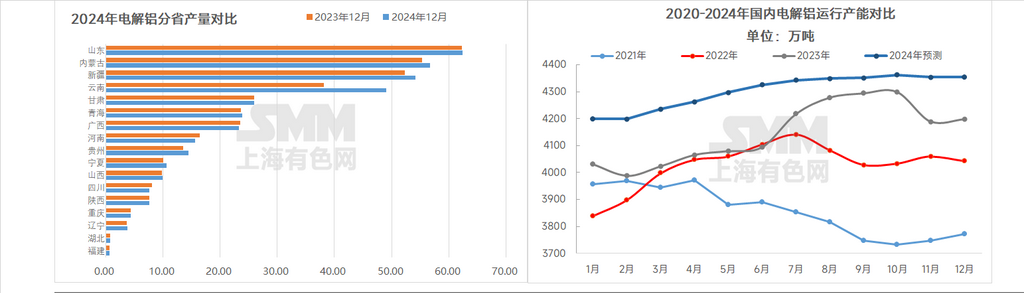
Domestic demand: By the end of December, SMM statistics showed that China's aluminum existing capacity was approximately 45.71 million mt, with operating capacity around 43.53 million mt. The industry's operating rate increased by 2.49 percentage points YoY to 95.38%. Currently, the operating capacity of domestic aluminum smelters shows both increases and decreases. The increases mainly came from the ramp-up of a new project at an aluminum smelter in Xinjiang, while the decreases were primarily due to production cuts at multiple aluminum smelters in Sichuan caused by losses and at a specific smelter in Guangxi due to technological transformation. Additionally, a capacity replacement project at an aluminum smelter in Inner Mongolia is proceeding as planned and is expected to be completed within the year, while a quota replacement project in Ningxia has been completed. Entering January 2025, domestic aluminum operating capacity remains stable. The negative impact of earlier production cuts on output has become evident. SMM has learned that no additional enterprises currently plan to cut production. By the end of December, the annualized operating capacity of domestic aluminum smelters remained steady at 43.53 million mt/year.
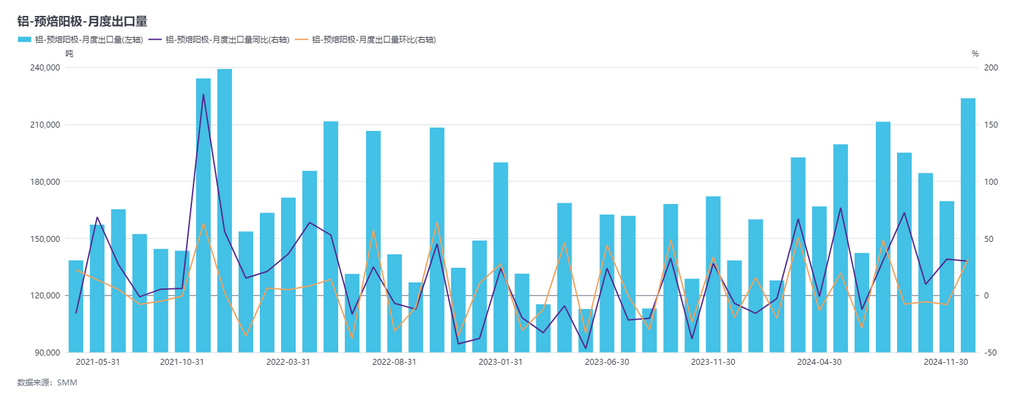
Overseas demand: China's prebaked anode exports in 2024 saw significant growth, with November's export volume hitting a yearly high. With the favorable performance of the domestic raw material market, export prices in December also increased. According to SMM estimates, the total export volume of prebaked anodes in 2024 is expected to exceed 2 million mt, significantly higher than the export level in 2023.
 

Brief analysis: In December, due to environmental protection-related controls, prebaked anode production in several regions experienced a slight decline. However, with the gradual release of capacity from new projects in north-west China and the resumption of production after maintenance by some enterprises, the overall supply reduction was relatively small. On the demand side, the operating capacity of domestic aluminum smelters shows both increases and decreases, with overall production slightly rising. It is expected that in January, aluminum enterprises will maintain stable operating capacity, and prebaked anode demand will remain relatively stable. Meanwhile, the unexpected price increase of prebaked anodes in January 2025 has improved the industry's profitability. Additionally, some aluminum enterprises are currently signing prebaked anode procurement contracts for 2025, indicating active demand. In summary, SMM expects prebaked anode enterprises to maintain high operating rates to meet market demand.


Declaración de Fuente de Datos: Excepto la información disponible públicamente, todos los demás datos son procesados por SMM basándose en información pública, comunicación de mercado y confiando en el modelo de base de datos interna de SMM. Son solo para referencia y no constituyen recomendaciones para la toma de decisiones.

Para cualquier consulta o para obtener más información, por favor contacte: lemonzhao@smm.cn
Para más información sobre cómo acceder a nuestros informes de investigación, contacte con:service.en@smm.cn
Noticias relacionadas
[SMM Noticias breves] South32 revisó la oferta de prima CIF MJP del cuarto trimestre de 2026 a 265 USD/tm
02 Oct 2026 10:52 (GMT+8)
[SMM Noticias breves] South32 revisó la oferta de prima CIF MJP del cuarto trimestre de 2026 a 265 USD/tm
Leer más
[SMM Noticias breves] South32 revisó la oferta de prima CIF MJP del cuarto trimestre de 2026 a 265 USD/tm
[SMM Noticias breves] South32 revisó la oferta de prima CIF MJP del cuarto trimestre de 2026 a 265 USD/tm
Fuentes del mercado informan: South32 revisó la oferta de prima CIF MJP para el cuarto trimestre de 2026 a 265 USD/tm, por debajo de los 325 USD/tm. Vigencia: 5 de octubre de 2026.
02 Oct 2026 10:52 (GMT+8)
India ADC 12 se mantiene firme mientras el aluminio en la LME cae; la escasa oferta de chatarra limita la caída
01 Oct 2026 17:48 (GMT+8)
India ADC 12 se mantiene firme mientras el aluminio en la LME cae; la escasa oferta de chatarra limita la caída
Leer más
India ADC 12 se mantiene firme mientras el aluminio en la LME cae; la escasa oferta de chatarra limita la caída
Los precios del ADC 12 en India se mantuvieron relativamente estables a pesar de una caída del 1,2 % en los precios del aluminio a 3 meses en la LME entre el 24 y el 30 de septiembre.
01 Oct 2026 17:48 (GMT+8)
Rio Tinto asegura las operaciones de la fundición de Bell Bay hasta finales de 2031
01 Oct 2026 17:09 (GMT+8)
Rio Tinto asegura las operaciones de la fundición de Bell Bay hasta finales de 2031
Leer más
Rio Tinto asegura las operaciones de la fundición de Bell Bay hasta finales de 2031
Rio Tinto anunció el 1 de octubre que había alcanzado acuerdos con el Gobierno de Tasmania, el Gobierno de la Mancomunidad de Australia e Hydro Tasmania para extender el suministro eléctrico a la fundición de aluminio de Bell Bay hasta finales de 2031. Los dos gobiernos también aportarán un paquete de apoyo combinado de 200 millones de dólares australianos a lo largo de cinco años, contribuyendo 100 millones cada uno. No se divulgaron los términos comerciales del acuerdo energético. Bell Bay produce alrededor de 190.000 toneladas de aluminio primario al año, mientras que su contrato eléctrico vigente debía expirar a finales de 2026. El acuerdo elimina la incertidumbre operativa inmediata de la fundición. Bell Bay es la tercera gran fundición de aluminio australiana en recibir apoyo respaldado por el Gobierno en 2026, tras Boyne y Tomago, lo que pone de relieve la presión continua de los elevados costes eléctricos y la competencia internacional.
01 Oct 2026 17:09 (GMT+8)

