Why Did Zinc Concentrate TCs Surge in January During the Regular Winter Mine Shutdown Season? [SMM Analysis]

Publicado: Jan 04, 2025 15:36 (GMT+8)
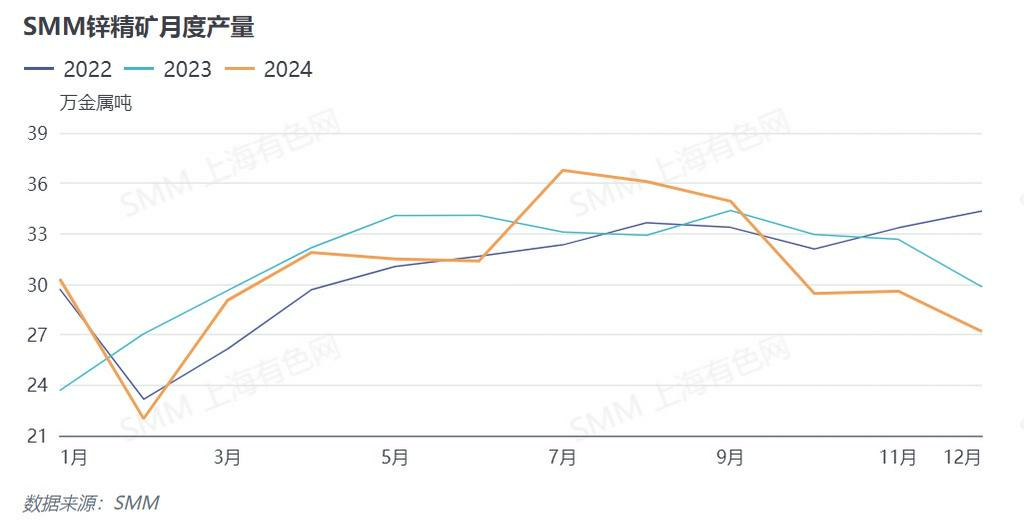
[SMM Analysis: Why Did January Zinc Concentrate TCs Surge During the Regular Winter Mine Shutdown Season?] This year, the overall supply-demand imbalance in zinc ore has caused domestic and imported zinc concentrate TCs to plummet to historical lows, highlighting extreme market conditions. From a production perspective, SMM data shows that zinc concentrate production from January to October decreased by 0.22% YoY. Although the Huoshaoyun mine commenced production this year, the overall production release has been limited. Coupled with a significant decline in raw ore grades in certain regions, it is expected that the overall zinc ore production this year may not see significant growth. So, what about next year...

SMM, January 4:

       As of January 3, SMM data showed that the weekly zinc concentrate TCs for domestic ore reached 1,950 yuan/mt, up 450 yuan/mt from November. Meanwhile, the TCs for imported zinc ore rebounded to nearly -$20/dmt. However, according to SMM's communication, December coincided with the traditional seasonal peak of production halts at some northern mines by year-end. Despite the decline in domestic zinc ore production, why did the TCs still rise significantly?
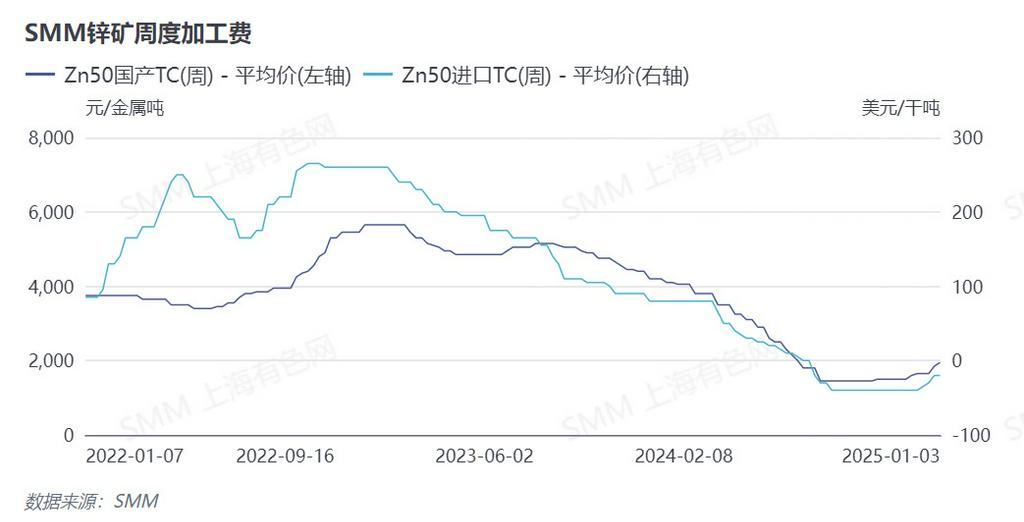
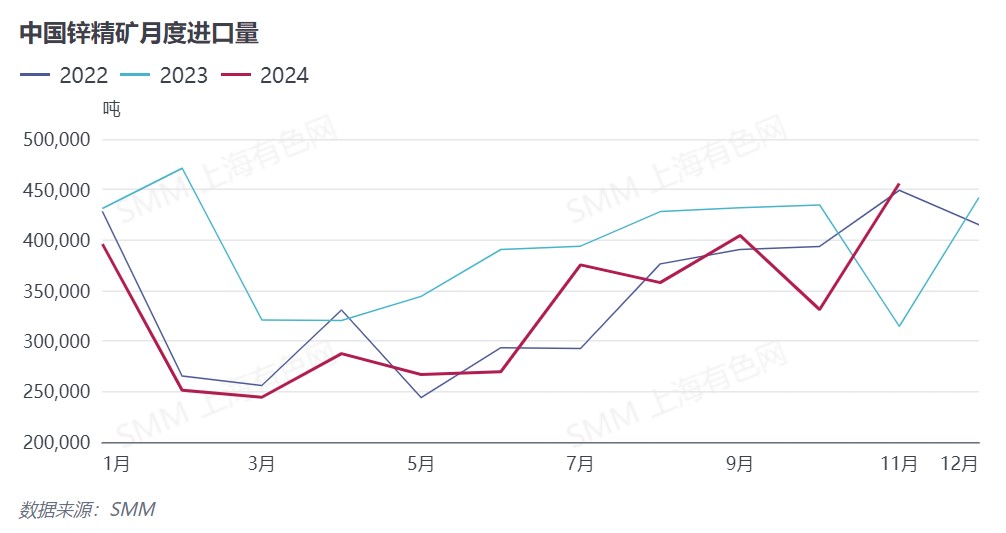
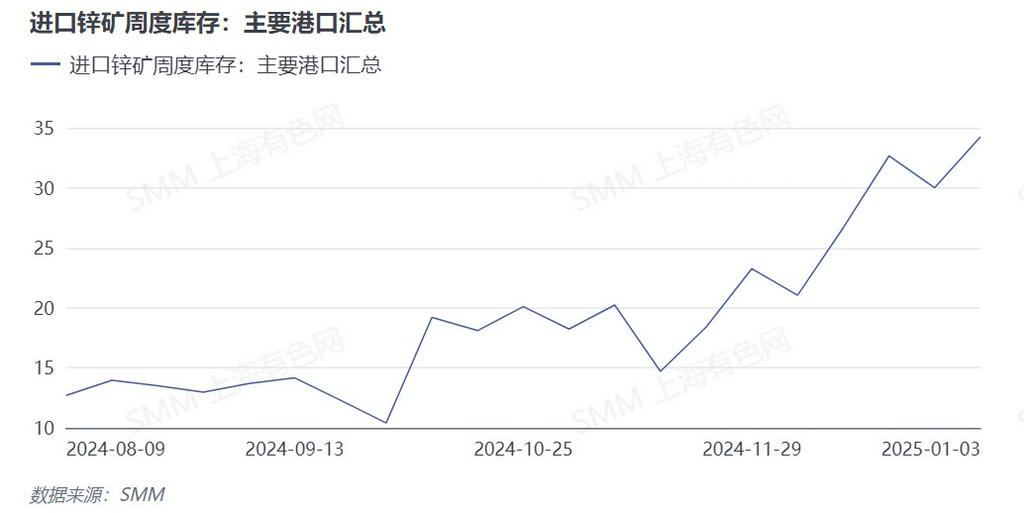
       From the supply perspective, due to the regular production halts during the winter season, domestic zinc ore production declined consecutively in November and December, leading to a significant reduction in domestic ore supply. However, since H2, China's zinc concentrate imports have increased significantly and remained at high levels in Q4, continuously supplementing the domestic market supply. Against this backdrop, inventories at major domestic zinc ore ports have also continued to grow, exceeding 300,000 mt in January.
 

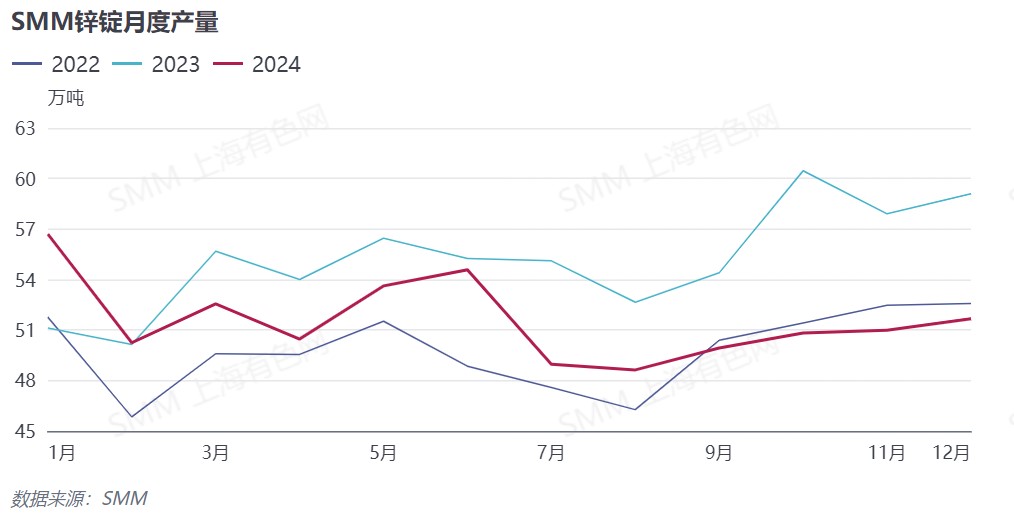
       From the demand perspective, SMM data indicated that smelter production in Q4 was approximately 500,000 mt. Although it improved compared to Q3, it remained at a low level overall, with limited growth in demand for zinc concentrate raw materials. Additionally, according to SMM's communication, the raw material inventory of domestic smelters rebounded to around 27 days in December, reaching the typical level for the same period in previous years, significantly alleviating raw material pressure compared to before.
       Therefore, as the raw material pressure on smelters eased, coupled with the sustained high zinc prices in Q4, smelters were able to negotiate with mines to increase zinc concentrate TCs, resulting in a significant rise in domestic zinc concentrate TCs in January. Alongside the increase in domestic TCs, smelters showed low purchase willingness for imported zinc ore TCs, which also led to a noticeable rebound in imported zinc ore TCs.


》View the SMM Metal Industry Chain Database
 

Declaración de Fuente de Datos: Excepto la información disponible públicamente, todos los demás datos son procesados por SMM basándose en información pública, comunicación de mercado y confiando en el modelo de base de datos interna de SMM. Son solo para referencia y no constituyen recomendaciones para la toma de decisiones.

Para cualquier consulta o para obtener más información, por favor contacte: lemonzhao@smm.cn
Para más información sobre cómo acceder a nuestros informes de investigación, contacte con:service.en@smm.cn
Noticias relacionadas
LME arrastra al zinc de la SHFE a la baja [Comentario matutino sobre el zinc de SMM]
hace 1 hora
LME arrastra al zinc de la SHFE a la baja [Comentario matutino sobre el zinc de SMM]
Leer más
LME arrastra al zinc de la SHFE a la baja [Comentario matutino sobre el zinc de SMM]
[SMM Comentario matutino sobre el zinc] Durante la noche, el contrato de zinc SHFE más negociado 2612 abrió en 25.800 yuanes/t, subió hasta un máximo de 25.920 yuanes/t al inicio de la sesión, luego bajó gradualmente hasta un mínimo de 25.365 yuanes/t y finalmente cerró a la baja en 25.455 yuanes/t, con una caída de 345 yuanes/t, o 1,34%. El volumen de negociación disminuyó a 98.569 lotes, y el interés abierto se redujo en 294 lotes hasta 100.000 lotes.
hace 1 hora
El sentimiento macro es bajista y el centro del zinc en el LME se desplaza a la baja [Resumen de la reunión matutina de SMM]
hace 1 hora
El sentimiento macro es bajista y el centro del zinc en el LME se desplaza a la baja [Resumen de la reunión matutina de SMM]
Leer más
El sentimiento macro es bajista y el centro del zinc en el LME se desplaza a la baja [Resumen de la reunión matutina de SMM]
[SMM Reunión Matutina Resumen: Sentimiento macro bajista, el centro del zinc LME se desplaza a la baja] Durante la noche, el zinc LME abrió en 3.804 $/t. En las primeras operaciones, el zinc LME subió gradualmente, alcanzando un máximo de 3.873,5 $/t, luego se desplomó bruscamente cerca del final de la sesión, cayendo a un mínimo de 3.773,5 $/t, y finalmente cerró a la baja en 3.780,5 $/t, con una caída de 21 $/t, un descenso del 0,55 %. El volumen de negociación disminuyó a 13.211 lotes, y el interés abierto se redujo en 203 lotes hasta 270.000 lotes.
hace 1 hora
Mercuria espera verle en la Conferencia y Exposición Industrial de Plomo y Zinc SMM LZE 2027 (22.ª edición)
hace 17 horas
Mercuria espera verle en la Conferencia y Exposición Industrial de Plomo y Zinc SMM LZE 2027 (22.ª edición)
Leer más
Mercuria espera verle en la Conferencia y Exposición Industrial de Plomo y Zinc SMM LZE 2027 (22.ª edición)
hace 17 horas