[SMM Analysis] Significant Growth and Structural Changes: A Comprehensive Review of Anode Materials in 2024H1

Publicado: Jul 25, 2024 10:30 (GMT+8)
Fuente: SMM
Half of 2024 has passed. During this period, despite the persistent low prices and overcapacity in the anode materials market, the early surge in downstream demand has invigorated the anode market in H1.

Half of 2024 has passed. During this period, despite the persistent low prices and overcapacity in the anode materials market, the early surge in downstream demand has invigorated the anode market in H1. For companies, the past six months have been complex. In the same market environment, different expectations and strategies led to varied choices and outcomes. In my view, "significant growth and structural changes" best describe the anode market in H1.

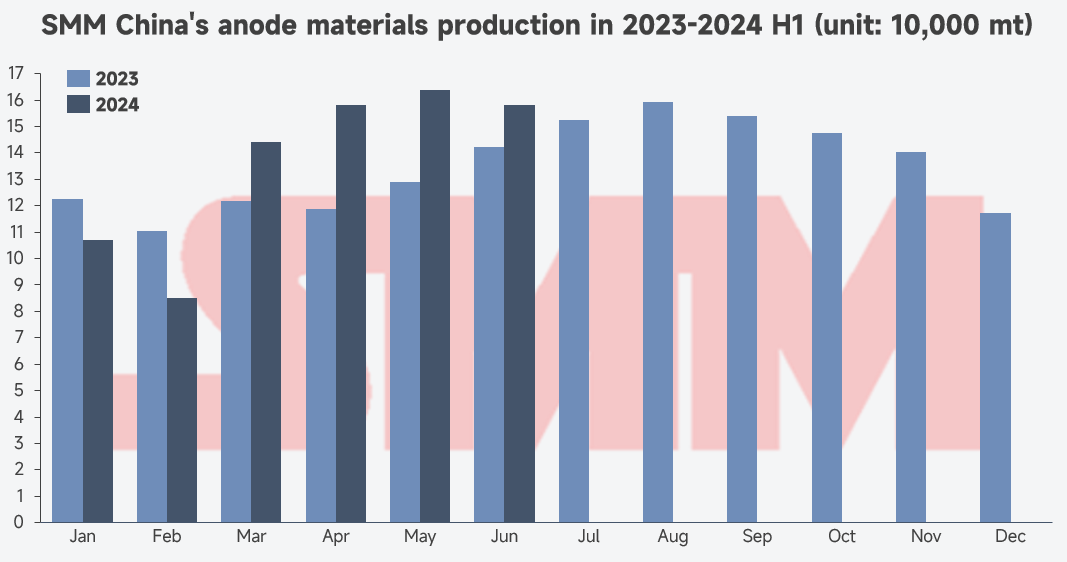
According to SMM, in 2024H1, China's graphite anode materials production reached 816,400 mt, up 9.6% YoY.
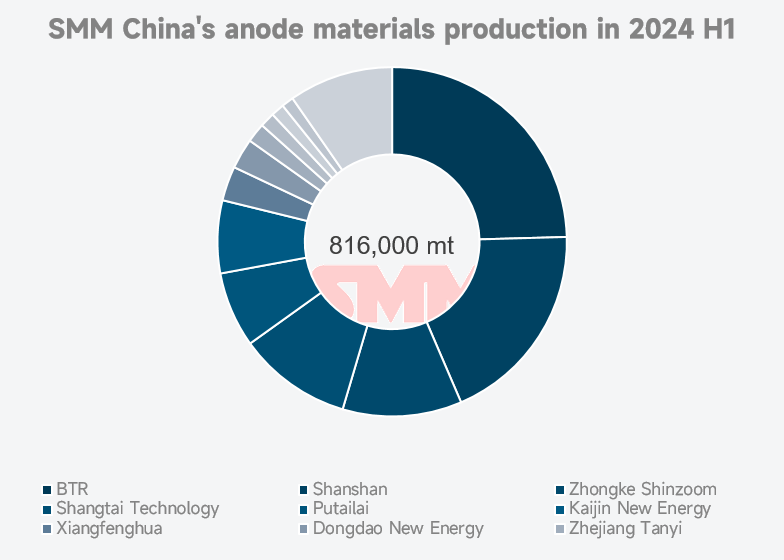
In 2024H1, BTR maintained its leading position in the anode materials industry, with a total share of about 25%. Due to varying predictions on the duration of the anode market downturn and differences in companies' finances, inventory, and market focus, the strategic routes chosen by leading companies diverged significantly, altering the industry's "three major" structure.
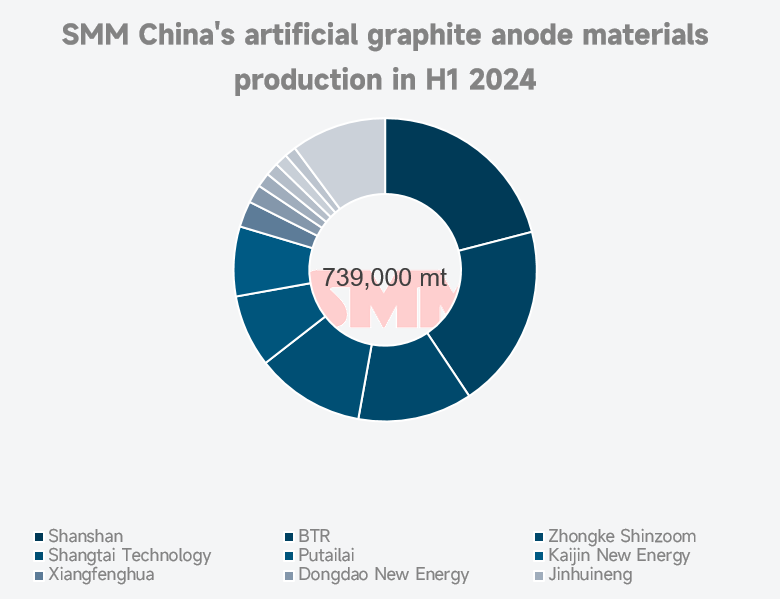
In 2024H1, with the continued weakness in raw material and graphitization costs, artificial graphite anodes still had a clear cost and price advantage. Meanwhile, as natural graphite exports were strictly controlled by the graphite bill, overall demand weakened. Additionally, the production and sales growth of silicon-based and hard carbon anode products was lower than expected, further increasing the market share of domestic artificial graphite anodes. According to SMM, in 2024H1, China's artificial graphite anode production was 739,000 mt, accounting for about 91%, up 11% YoY. Shanshan continued to dominate the artificial graphite materials industry, with a total share of about 21%.

End-users' performance requirements for anode materials also contributed to the increased share of artificial graphite anodes. NEV sales saw significant growth in H1, and power battery cells demanded higher performance in fast charging. Leading companies, leveraging their technical advantages, captured the fast-charging anode materials market. Shanshan and BTR maintained top positions, while Zhongke Shinzoom and Shangtai Technology also saw an increase in their shares. Energy storage sector, as the market heated up, the iteration of 314Ah batteries also raised higher specifications for energy storage anode materials. New entrants like Sunrise New Energy seized the development opportunities in the energy storage market, actively responded to new product demands from customers, and significantly increased their shipments and industry share.
In 2024H1, industry concentration continued to rise, with CR6 reaching 78%. In the current context of limited cost and price reduction room for anodes, downstream customers are more focused on "quality" and "stable supply" rather than "low prices." For battery cell manufacturers, anode companies that can timely respond to customer needs and ensure quality and quantity in supply are more worthy of selection than those offering merely low prices. For anode companies, this is not only the "confidence" to maintain product quality and scale amid the market downturn but also raises higher requirements for controlling production processes.
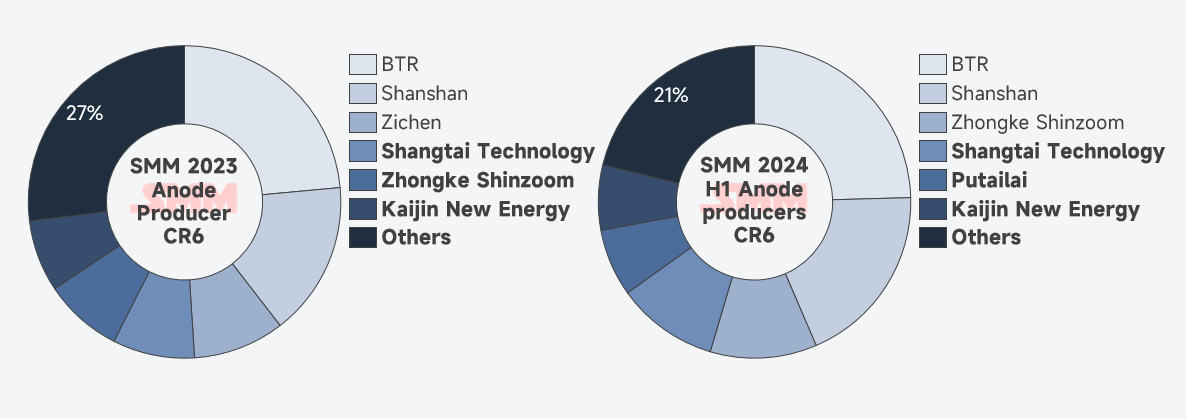
Looking back, although there was significant growth in 2024H1, the anode industry still faces persistent issues, and it cannot be considered a "spring bloom." The demand highlight may even fade in Q3 as downstream enthusiasm cools. However, the industry downturn is not entirely without benefits for companies: optimizing and upgrading product structures, managing inventory and finances, and improving the upstream and downstream chains are perpetual challenges that become even more crucial now. While industry and supply chain prosperity are essential for company growth, when the "wind" weakens, only strong "internal improvement" can ensure higher and more stable standing.

Declaración de Fuente de Datos: Excepto la información disponible públicamente, todos los demás datos son procesados por SMM basándose en información pública, comunicación de mercado y confiando en el modelo de base de datos interna de SMM. Son solo para referencia y no constituyen recomendaciones para la toma de decisiones.

Para cualquier consulta o para obtener más información, por favor contacte: lemonzhao@smm.cn
Para más información sobre cómo acceder a nuestros informes de investigación, contacte con:service.en@smm.cn
Noticias relacionadas
[SMM Noticias] El regulador brasileño ordena una suspensión parcial en la mina de Sigma Lithium por “riesgo inminente”
hace 2 horas
[SMM Noticias] El regulador brasileño ordena una suspensión parcial en la mina de Sigma Lithium por “riesgo inminente”
Leer más
[SMM Noticias] El regulador brasileño ordena una suspensión parcial en la mina de Sigma Lithium por “riesgo inminente”
[SMM Noticias] El regulador brasileño ordena una suspensión parcial en la mina de Sigma Lithium por “riesgo inminente”
El 2 de octubre, Sigma Lithium suspendió todas las actividades mineras e industriales en su operación Grota do Cirilo en Brasil, su único activo productivo, a la espera del fallo de un tribunal federal de apelaciones sobre una medida cautelar relativa a sus licencias ambientales. La Agencia Nacional de Minería de Brasil (ANM) había ordenado detener la minería en la ladera este del pozo norte. La producción de concentrado del sitio está detenida durante la suspensión, y las ventas de finos de litio continúan. Sigma retrasó su guía de producción a 12 meses de 240.000 toneladas en tres meses y mantiene su objetivo para el año fiscal 2027 de 330.000 toneladas de concentrado.
hace 2 horas
[SMM Noticias] Lithium Argentina describe un plan de expansión por fases para Cauchari-Olaroz
hace 2 horas
[SMM Noticias] Lithium Argentina describe un plan de expansión por fases para Cauchari-Olaroz
Leer más
[SMM Noticias] Lithium Argentina describe un plan de expansión por fases para Cauchari-Olaroz
[SMM Noticias] Lithium Argentina describe un plan de expansión por fases para Cauchari-Olaroz
Lithium Argentina confirmó una expansión de Fase 2 en el proyecto de salar Cauchari-Olaroz en Argentina, añadiendo 45.000 t/a de capacidad de carbonato de litio y elevando la capacidad total a 85.000 t/a. De esta, se espera que un módulo inicial de 10.000 t/a que utiliza extracción directa de litio por adsorción entre en funcionamiento en 2028. Esto estima un VAN después de impuestos de 3.100 millones de dólares y una TIR del 28,5% a un precio del carbonato de litio de 18.000 dólares/t, con costos operativos de 5.006 dólares/t. La inversión total para la Fase 2 es de 1.000 millones de dólares. El proyecto sigue sujeto a aprobaciones regulatorias, y la ingeniería de detalle para el módulo inicial está prevista para finales de este año. El suministro adicional está programado a partir de 2028.
hace 2 horas
[SMM News] Patagonia Lithium completa prueba de bombeo de 72 horas en Cilon
hace 2 horas
[SMM News] Patagonia Lithium completa prueba de bombeo de 72 horas en Cilon
Leer más
[SMM News] Patagonia Lithium completa prueba de bombeo de 72 horas en Cilon
[SMM News] Patagonia Lithium completa prueba de bombeo de 72 horas en Cilon
Patagonia Lithium completó una prueba de bombeo de 72 horas en el pozo ocho de su concesión Cilon, con un caudal de 2.043 litros/hora y 146.800 litros extraídos. La concentración de litio alcanzó 232 ppm a 250 m de profundidad. Se bombearon unos 34 kg de litio, equivalentes a 180 kg de carbonato de litio equivalente (LCE). En la prueba de recuperación de 24 horas, el nivel del agua volvió de 52,4 m al nivel estático de 3,64 m. La empresa identificó una zona acuífera de interés entre 226 m y 324 m de profundidad y está actualizando su estimación de recursos minerales, a la que seguirá un informe de alcance. El proyecto se encuentra en etapa de exploración y no se ha anunciado un cronograma de producción.
hace 2 horas