Since January, overseas nickel mining companies have frequently faced production shutdowns, with information showing that the shutdowns are mainly located in Australia. According to SMM data, the total amount of imported overseas nickel ore in China increased first and then decreased in 2023, with a decrease of about 67% for three consecutive months starting from October; Among them, the Philippines is the main importer of nickel ore in China. In December, China's import volume has decreased by about 75% compared to the high point of the year, while Indonesia and Australia have a relatively small proportion of nickel ore imports. Therefore, the shutdown of some Australian nickel mining companies has a relatively small impact on China's nickel ore supply.
According to China Customs data, in December 2023, China imported 1.9406 million tons of nickel ore (mixed wet and dry according to customs data), a decrease of 49.8% month on month and 29.6% year-on-year. The import volume of nickel ore has decreased both month on month and year on year, which is basically in line with SMM's expectations. The main reason is that Surigao, a major mining area in the Philippines, has entered the rainy season in December, and the domestic iron plant's raw material reserves have been basically completed, resulting in a decrease in import volume for the month. In addition, during December, the sustained low price of nickel iron led to strong reluctance to sell in smelters, resulting in a decline in domestic production of high-grade NPI against the backdrop of weak demand and accumulated inventory. This further suppressed demand for raw materials.
Entering January, the Surrey Highlands region in the Philippines continues the rainy season, and SMM predicts that China's imported nickel ore volume will show a downward trend in January.
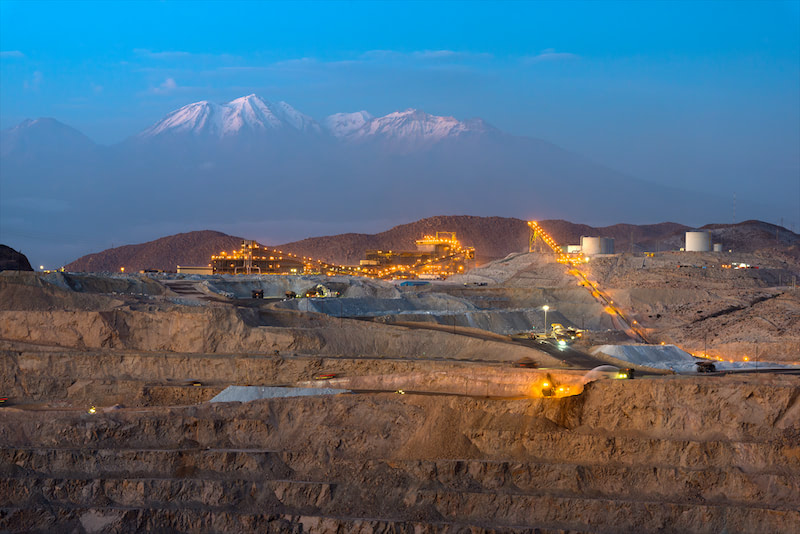
Overview of Shutdown of Nickel Mining Companies
On January 30th, Australian battery metal producer IGO Ltd announced that due to low prices, the Cosmos nickel project in Western Australia will be shut down for maintenance, while reducing annual lithium production estimates.
On January 22nd, BHP Group announced that it will conduct inspections and maintenance on some facilities at its Kambalda nickel mine in western Australia. Previously, Wyloo Metals, which supplies ore to the beneficiation plant, announced that it will suspend mining operations due to low nickel prices.
On January 21st, Wyloo Metals Pty Ltd., a private nickel producer owned by billionaire Andrew Forrest, will close its mine in Western Australia due to a significant drop in the price of this critical transition metal. The company stated that the mines near Kambalda will undergo maintenance and upkeep starting from May 31st. A Wyloo spokesperson added that the company has notified BHP Group that it will not be able to fulfill a nickel purchase agreement that will expire at the end of 2025. The company only acquired these mines six months ago. Wyloo has assets in Canada and Australia, and last year signed a joint venture agreement with IGO Ltd. to produce battery materials at a factory near Perth. Wyloo stated in a statement that despite the closure of these mines, the company is currently researching the development of its own nickel beneficiation plant in the Kambalda region.
On January 15th, First Quantum Minerals, a Canadian mining company, announced that it will reduce its operations at nickel mines in Australia and suspend mining operations at the Shoemaker Levy mine.
In early January, ASX: PAN closed its Savannah nickel mine located in the Kimberley region of Western Australia. The decision announced last week will lay off 140 job positions.
Nickel Ore Spot Price
Since mid to late October 2023, the average spot price of 1.5% (CIF) laterite nickel ore in the Philippines has continued to weaken, falling by about 36.92% in the past three months. On January 30th, it was reported that the price was 41 US dollars per wet ton, which remained unchanged from the previous day. Currently, the arrival ore prices from the Philippines to China have temporarily stabilized. According to SMM research, due to the rainy season in the Surrey Highlands region of the Philippines, the export volume of nickel ore to China significantly decreased in December, and spot transactions also decreased.
In terms of Indonesian nickel mines, the approval of RKAB for nickel mines in 2024 has been hindered, and currently about 6 mining companies have received quotas. Although the quantity has increased compared to January 15-19, the increment is limited.
On the demand side, the inventory of raw materials at large nickel iron smelters in Indonesia is currently about 2 months, so the current willingness to purchase nickel ore is not strong. Last week, the premium for nickel ore was maintained at 3-6 US dollars, and further attention needs to be paid to the distribution of nickel ore quotas.
This article is written excutively by SMM analysts and please do not hesitate to contact me at fancyli@smm.cn if you have any question or inquiry.