
Key Takeaway From LME Week: China’s Overseas Investment Is Key To Commodity Super Cycle, RMB Will Play A Key Role

Publicado: Oct 11, 2023 11:08 (GMT+8)
Fuente: SMM
SHANGHAI, Oct 11 (SMM) – The ongoing 2023 SMM LME LONDON EVENT, being held at ST. Pancras Renaissance Hotel London, Euston Rd., London NW1 2AR, has brought together major industry players and commodity experts to share their valuable insights and unique perspectives on new energy and base metals outlook.

SHANGHAI, Oct 11 (SMM) – The ongoing 2023 SMM LME LONDON EVENT, being held at ST. Pancras Renaissance Hotel London, Euston Rd., London NW1 2AR, has brought together major industry players and commodity experts to share their valuable insights and unique perspectives on new energy and base metals outlook.

At the "SMMLMELONDONEVENT" held during LMEWEEK, Song Gao, co-CEO and research director of PRC Macro, expressed his views on "The New Order of Emerging Markets: Geopolitics, RMB Impact, Supply Chain Decoupling and Economic Restructuring."
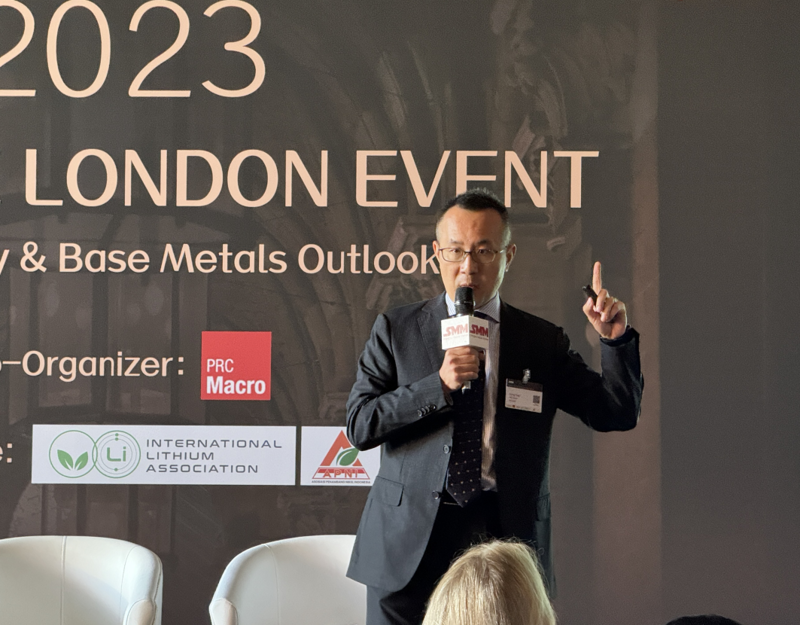
He said that China’s overseas investment is the key to the commodity super cycle, and China’s overseas investment has just begun! Catching up with larger economies is good for metals demand.

The proportion of China's cumulative overseas direct investment (ODI) in nominal GDP is less than half of the average level of major economies. We predict that China's ODI will reach $18 trillion by 2045, increasing from approximately $180 billion currently to $1.3 trillion in 2045.

Ease the pain of deleveraging and manufacturing replenishment

Reducing the pain of deleveraging means:

1) Conventional debt conversion, interest rate cuts and debt relief; 2) Unconventional asset purchases, bank recapitalization and fiscal capital injection.

We expect manufacturing replenishment driven by housing completions, energy transition and ODI to begin in the fourth quarter.

Historically, cyclical shifts in manufacturing restocking have been consistent with rebounds in A-share prices, the yuan, and commodity and energy prices.

Energy and manufacturing upgrade

Energy transition: Energy is the new asset

The composition of China's exports reflects a shift toward high value-added, energy-intensive products.

The energy transition supports strong growth in infrastructure such as power grids and power generation.

Policy support for shantytown renovations and real estate completions supported demand for durable goods. It expects copper to have room for a 10%-15% increase.

Geopolitical de-risking and "going south"

China's official direct investment, financed by state-owned banks, rebounded sharply, partially offsetting the impact of lower exports and lower foreign direct investment risks due to the global manufacturing downturn and shrinking external demand.

China's ODI is mainly concentrated in ASEAN and BRICS countries, rather than developed markets.

Benefits of global urbanization and industrialization

Domestic and foreign factors driving China's ODI support metal demand through industrialization and urbanization in recipient countries. For example, China ODI funds the growth of steel demand in China.

Demand from the domestic energy transition and ODI offset weaker-than-expected performance of domestic real estate.

We expect China to increase its ODI efforts, focusing on manufacturing, infrastructure and mining. China's ODI will accelerate urbanization and industrialization in the global south.

The new role of RMB and the new world order

Lower RMB interest rates and de-dollarization of policies have provided support for China's ODI. Japan's experience shows that if a currency can fund carry trades, sustained ODI flows will follow. In the past, China's ODI was based on the US dollar and was greatly affected by external factors.

Currently, the RMB plays a new role in the "dual circulation".

The New World Order: The Energy-Defence-Infrastructure Axis

Southern rail and infrastructure connections

The Trans-Asian Railway network connects ASEAN.

Recipient of RMB-financed infrastructure and excess manufacturing capacity.

Capacity migration provides a new way for China to enter the DM market.

Local urbanization and industrialization drive demand for resources and increase purchasing power.

China’s manufacturing capabilities reduce the costs of the local energy transition.

Multilateral and bilateral treaties, trade areas.

Northern Energy Transport Network

Financing infrastructure and affordable, stable Russian energy supplies in RMB.

RMB finances high-value asset manufacturing projects.

High-quality and low-cost energy has subsidized China's manufacturing upgrade and energy transformation, increasing the added value and competitiveness of exports.

Higher value-added manufacturing promotes productivity growth.

This is protected by multilateral trade and investment treaties.

China drives another commodities supercycle

China ODI, RMB and Commodities Super Cycle

China will drive metals demand through urbanization and industrialization in recipient countries (ASEAN and the Belt and Road Initiative). This means that by 2040, demand for steel will reach 200 million mt, copper demand will reach 12 million mt, and aluminum demand will reach 38 million mt. Demand in the next 17 years will increase by 11%, 46%, and 55% respectively.
LME Week: Which Metal Has The Most Upside Potential For 2024? Majority (Including Citibank) Bets On Copper


Key Takeaway From LME Week: China’s Sustained And Rapid ODI Growth Will Add 11% To Demand For Steel, 46% More Demand For Copper And 55% More Demand For Aluminum


Key Takeaway From LME Week: China Fights Back By Upgrading Alumina And Primary Aluminium Trade With Russia


Declaración de Fuente de Datos: Excepto la información disponible públicamente, todos los demás datos son procesados por SMM basándose en información pública, comunicación de mercado y confiando en el modelo de base de datos interna de SMM. Son solo para referencia y no constituyen recomendaciones para la toma de decisiones.

Para cualquier consulta o para obtener más información, por favor contacte: lemonzhao@smm.cn
Para más información sobre cómo acceder a nuestros informes de investigación, contacte con:service.en@smm.cn
Noticias relacionadas
La demanda mundial de metales para la transición energética aumenta, el cobre enfrenta desafíos de suministro y el litio experimenta un alivio a corto plazo
hace 2 horas
La demanda mundial de metales para la transición energética aumenta, el cobre enfrenta desafíos de suministro y el litio experimenta un alivio a corto plazo
Leer más
La demanda mundial de metales para la transición energética aumenta, el cobre enfrenta desafíos de suministro y el litio experimenta un alivio a corto plazo
A medida que se expanden los vehículos eléctricos, las energías renovables, el almacenamiento de energía en baterías y la red eléctrica, se espera que la demanda mundial de metales para la transición energética siga creciendo. Sin embargo, los riesgos de suministro varían según el producto: algunos mercados podrían enfrentar escasez, mientras que otros podrían registrar un exceso de oferta. El informe Transition Metals Outlook 2026 publicado por la institución destaca estas tendencias divergentes: el cobre enfrenta el mayor desafío de suministro a largo plazo, mientras que la demanda de litio podría triplicarse para 2050. Dicho esto, se espera que la entrada en funcionamiento de nueva capacidad minera alivie la escasez de litio en el corto plazo y ejerza presión sobre los precios a medida que se expande la oferta.
hace 2 horas
Teck Resources enfrenta una posible huelga en su mina de cobre de Columbia Británica tras el aviso del sindicato
hace 2 horas
Teck Resources enfrenta una posible huelga en su mina de cobre de Columbia Británica tras el aviso del sindicato
Leer más
Teck Resources enfrenta una posible huelga en su mina de cobre de Columbia Británica tras el aviso del sindicato
La minera canadiense Teck Resources anunció en un comunicado de prensa el 21 de octubre que recibió un aviso de huelga del sindicato United Steelworkers Local 7619 en sus operaciones de Highland Valley Copper, en Columbia Británica. Teck Resources señaló que el aviso significa que el sindicato podría iniciar una huelga a partir de las 8:00 a. m., hora del Pacífico, del 24 de octubre (23:00, hora de Pekín, del 24 de octubre). La empresa agregó que cuenta con planes de contingencia para garantizar una producción segura y la gestión ambiental durante cualquier acción laboral. El convenio colectivo en Highland Valley Copper expiró el 30 de septiembre.
hace 2 horas
【Flash | Southern Copper evalúa expansión de 680 millones de dólares en Cuajone con meta anual de 1.400 toneladas de molibdeno】
hace 8 horas
【Flash | Southern Copper evalúa expansión de 680 millones de dólares en Cuajone con meta anual de 1.400 toneladas de molibdeno】
Leer más
【Flash | Southern Copper evalúa expansión de 680 millones de dólares en Cuajone con meta anual de 1.400 toneladas de molibdeno】
Southern Copper está evaluando una expansión de 680 millones de dólares en su operación Cuajone en Perú. La propuesta aumentaría la capacidad de molienda en un 33%, de 90.000 a 120.000 toneladas por día. Las estimaciones actuales prevén una producción anual promedio de 55.000 toneladas de cobre y 1.400 toneladas de molibdeno. La empresa también está estudiando si la capacidad podría alcanzar eventualmente las 150.000 toneladas por día. El proyecto sigue en evaluación, sin que se haya revelado una decisión final de inversión ni un calendario de producción; por lo tanto, su producción proyectada de molibdeno aún no puede considerarse como nueva oferta comprometida.
hace 8 horas

