

Abstract
On 10 July 2023, the European Council passed a new regulation intended to bolster the management of batteries and waste batteries ("Batteries Regulation"). This law mandates that batteries, including those used in electric vehicles (EVs), must be accompanied by a "battery passport". This document will record information on the batteries' manufacturing history, chemical composition, technical specifications, and carbon footprint.
The regulation opens up new avenues for European EV companies, strengthening their competitive edge. While it does make the market competition more challenging and intense for Chinese EV companies, it will also increase market demand and uncover fresh business opportunities. It can assist Chinese EV companies in their future overseas expansion, the development of industrial ecosystems, and innovative modelling.
- What is the "Battery Regulation"?
On 10th July 2023, the European Council passed a new regulation designed to strengthen the management of batteries and waste batteries. The regulation will oversee the entire lifecycle of a battery from production to recycling and reuse, ensuring its safety, sustainability, and competitiveness.

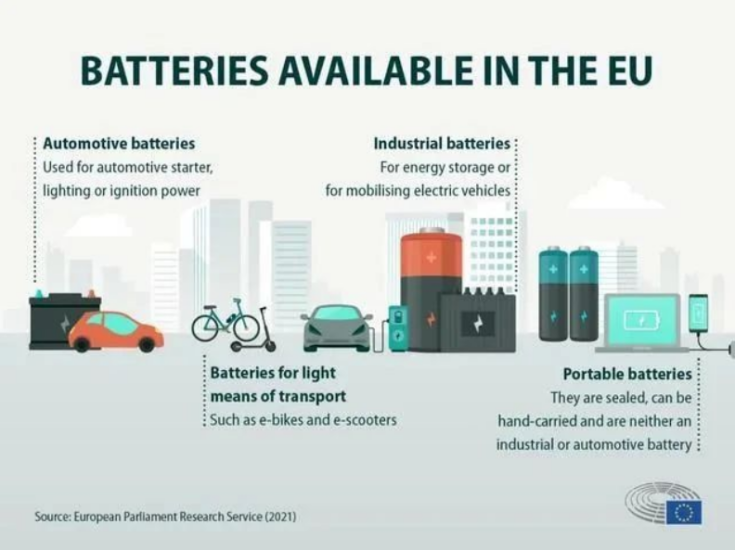

The new rule states that batteries for light means of transport (LMT), industrial batteries with a capacity above 2kWh, and EV batteries must have a digital "Battery Passport." This document records the battery's manufacturing history, chemical composition, technical specifications, and carbon footprint. The rule also instructs that by 2026, power batteries and industrial batteries must hold a battery passport to be sold in the European Economic Area.
Furthermore, the regulation establishes end-of-life requirements, including collection targets and obligations, and targets for the recovery of materials. For example, it sets a target for lithium recovery from waste batteries of 50% by the end of 2027 and 80% by the end of 2031.
Starting 1st January 2027, technical documents should accompany industrial batteries, EV batteries and automotive batteries. Batteries containing cobalt, lead, lithium or nickel should disclose their recycled content. The mandatory minimum levels of recycled content for cobalt, lead, lithium or nickel are provided as follows:
|
Date |
mandatory minimum levels of recycled content in battery active materials |
|||
|
Ni |
Co |
Li |
Pb |
|
|
From Jan 1, 2030 |
≥4% |
≥12% |
≥4% |
≥85% |
|
From Jan 1, 2035 |
≥12% |
≥20% |
≥10% |
≥85% |
The implementation of the "battery passport" provides standardised guidance for battery companies but may also pose certain risks.
- Opportunities: It sets standardised and transparent industry standards, reducing environmental and social impact over the entire battery life cycle. It ensures new battery sustainability and contributes to green transformation.
- Risks: Certain information ought to be made more widely available to the public in a standardised form. For instance, parameters pertaining to battery performance, such as cycle life, are highly sensitive. Additionally, the key components of batteries should be disclosed to the public on a broad scale. There may be a need to reveal the quantities of sensitive metals, such as nickel and cobalt, as well as certain trace metals.
- The "Battery Regulation"- A Double-edged Sword for New Energy Development in Europe
The introduction of the new regulation will enhance the competitiveness of Europe's local battery industry and empower battery developers. It will also decrease reliance on imported batteries, aiding Europe in vying for global leadership in the standardisation of the battery industry.
- The "Battery Passport" tracks information across the entire battery life cycle, assisting the European Union in setting up a supply chain management system that starts at raw materials.
- It sets up a management system for the battery value chain, leads the creation of a data-sharing platform, and collects information on the battery manufacturing and recycling processes.
- In the shift towards climate neutrality, it offers increased financial support to EU battery enterprises, with Europe investing 60 billion euros in European battery factories and vehicle manufacturers.
The rule is expected to accelerate the popularisation of EVs in Europe. However, Europe's present capacity may not meet its future demand over the coming two to three years, taking into account the rule's stringent requirements concerning human rights and battery recycling rates. This situation presents market opportunities for overseas companies to broaden their operations in Europe and in countries covered in Europe’s trade agreements.
III. "Battery Regulation" – Opportunities and Challenges for Chinese EV Manufacturers
As of January 2023, EV sales in China reached 6.884 million units, thereby increasing China's share in the international market to 63.6%. The shipment volume of China's lithium-ion batteries grew to 660.8 GWh, marking a year-on-year increase of 97.7%, and now accounts for 69.0% of the global quantity. China boasts a comprehensive power battery supply chain, with 70% of the world's battery production capacity located within the country, and its products are traded globally. The introduction of the regulation has created an entry barrier for Chinese batteries being exported overseas.
On the other hand, this law will hasten the widespread adoption of EVs in Europe and boost market demand for power batteries. However, the law also requires stricter localisation standards for the supply chain and production. To take full advantage of future market opportunities, manufacturers are expected to accelerate the organisation of their supply chain and the restructuring of the industry.
- Raw material manufacturers: The law requires all manufacturers, apart from small and medium enterprises, to verify the information concerning the raw materials used to produce batteries. This includes details such as technical specifications, carbon footprints, and human rights considerations. Given the diversity of upstream material sources – with many primary material productions situated in less developed regions where legal regulations and enforcement may be lacking – manufacturers must pay careful attention to the legality of their upstream sources.
Raw material manufacturers may also seize these opportunities to explore European markets. However, due to the constraints of the regulation, if they cannot localise quickly in the countries covered by the EU trade agreement, their clients may consider switching suppliers. Some Chinese battery manufacturers, such as CATL, and battery material manufacturers like CNGR & Huayou Cobalt, have collaborated with overseas mines and manufacturers of battery raw materials to ensure data traceability while maintaining supply throughout the entire supply chain.
- Battery cell manufacturers: China began measuring its carbon footprint later than Europe, and its data system is less comprehensive in comparison. The proportion of renewable energy utilised in China is significantly lower than in Europe, contributing to increased indirect emissions during the production process. Therefore, Chinese battery cell manufactures:
- may struggle to meet the regulation due to a lack of renewable materials.
- could face regulatory compliance risks due to complex information and labelling systems.
- could lose competitive advantages as a result of greater carbon intensity in electricity production.
Chinese battery manufacturers are targeting European markets, establishing production facilities in Europe, and becoming familiar with Europe's carbon footprint system. This knowledge will quickly enable them to procure and process battery materials locally and comply with recycling standards. By H1 2023, leading lithium battery manufacturers such as CATL, SVOLT Energy, and Farasis Energy have opted to build factories in Germany, while AESC has established a battery factory in France. However, due to recent international political instability, potential political risks must be considered during deployment.
Hence, Chinese battery companies should reassess their global strategy and investment portfolio, moving forward with their industry positioning in the European market. They need to acquaint themselves with the responsibilities and obligations set out in the new "Battery Regulation." This includes specific rules concerning battery manufacturers, authorised representatives, importers, distributors, and travel service providers. Through analysing the macro-environment and the industry, they can identify potential barriers to entry in their target markets and evaluate their prospects for future development.
Chinese companies must engage in a thorough compatibility analysis to align their business strategies. This requires a careful assessment of their strengths and weaknesses in areas such as investment, operations, organisational control, and marketing, helping them recognise where they stand in comparison to the target market. The insights derived from this analysis can further refine their approach. Key areas to consider in this analysis include:
- Evaluating the market landscape and forecasting its scale.
- Examining the current state of supply and demand, along with predictions for future growth.
- Analysing the local business environment, including relevant policies that might affect operations.
- Identifying short-to-medium-term market opportunities, as well as potential risks that may arise.
- Assessing potential competitors to understand the competitive dynamics within the market.



