[SMM Annual Report] Global Nickel Likely to be Oversupplied in 2023-2026E

Publicado: Jan 10, 2023 17:33 (GMT+8)
In 2023, in addition to the impact of the aforementioned delays in the commissioning of some capacity, the demand from the new energy industry will stimulate the production and ramp-up of the upstream producers.

SHANGHAI, Jan 10 (SMM) - 2022 is another year that has witnesses the nickel price turmoil. In March 2022, nickel prices soared to a record high. In the second quarter, the prices were on a downward trend and returned to the fundamentals due to COVID-19 outbreak and the macro factors. In the middle and late third quarter, steel mills were expected to resume their production owing to the sharp drop in stainless steel supply earlier, pushing up the short-term stainless steel output and the nickel demand. In addition, the new energy industry mushroomed in the third quarter. The operating rates of battery companies grew amid the improvement of orders, the low inventory of precursor companies, the rapid expansion of the leading battery producers, etc. Nickel demand gained strong support from the new energy industry. As a result, the prices rallied from lows.

In terms of the fundamentals in 2022, the US Fed continued to raise the interest rates to temper inflation. The global economy showed signs of recession from time to time, and overseas consumption, especially in European countries, slumped, while nickel consumption performed relatively well. The two major downstream markets, the stainless steel and new energy industries both maintained positive growth, and the nickel demand in the latter burgeoned by more than 30% year-on-year. Nickel demand from the military alloy sector grew apace, while that from the electroplating sector performed poorly during the year.

In 2023, the market may witness a significant supply surplus of primary nickel, especially the NPI.  Besides, the refined nickel supply will also be in surplus. Nonetheless, the same scenario is unlikely happen to nickel sulphate in 2023 because of its capacity mismatch. The Indonesian government’s potential export tax hike on nickel products may, on the other hand, affect the rhythm of NPI production and cause oversupply. The global economy will not be optimistic in 2023. Under the influence of factors on the fundamentals and macro front, nickel prices will fluctuate wildly with a high probability and will trend lower amid the expected supply surplus.
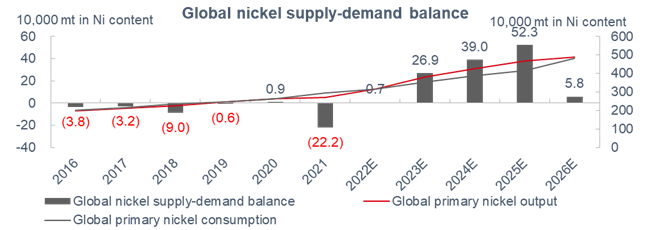
In 2022, the global primary nickel consumption is expected to be 3.14 million mt in Ni content, up 6.9% YoY. The supply will add 15.9% YoY to 3.148 million mt in Ni content. The global primary nickel surplus will reach 8,000 mt in Ni content. The market should see no supply surplus if the downstream restocking demand had been taken into account. In 2022, nickel supply has been relatively tight, which is mainly caused by the lower-than-expected growth of supply.  The commissioning of Indonesia NPI slowed down, and some production lines were switched to produce high-grade nickel matte, reducing the expectations of NPI oversupply to some extent. Meanwhile, the nickel salt output, restricted by the mismatch between converted battery-grade nickel sulphate capacity and the raw material types, failed to surge, thus the market supply was in deficit for most of the year.

In 2023, the surplus is expected to expand further. In addition to the impact of the aforementioned delays in the commissioning of some capacity, the demand from the new energy industry will stimulate the production and ramp-up of the upstream producers. In 2023, the total supply will reach 3.808 million mt in Ni content while the demand will be 3.54 million mt in Ni content, resulting in a supply surplus of 269,000 mt in Ni content, which is mainly contributed by NPI supply since there will be multiple new NPI production lines put into production. SMM predicts that SMM #1 refined nickel prices will move between 143,000-178,000 yuan/mt, with an average of 160,500 yuan/mt.


Declaración de Fuente de Datos: Excepto la información disponible públicamente, todos los demás datos son procesados por SMM basándose en información pública, comunicación de mercado y confiando en el modelo de base de datos interna de SMM. Son solo para referencia y no constituyen recomendaciones para la toma de decisiones.

Para cualquier consulta o para obtener más información, por favor contacte: lemonzhao@smm.cn
Para más información sobre cómo acceder a nuestros informes de investigación, contacte con:service.en@smm.cn
Noticias relacionadas
【Flash | Los recargos de tubos con molibdeno de Tubacex en octubre son mixtos】
02 Oct 2026 10:52 (GMT+8)
【Flash | Los recargos de tubos con molibdeno de Tubacex en octubre son mixtos】
Leer más
【Flash | Los recargos de tubos con molibdeno de Tubacex en octubre son mixtos】
Tubacex publicó sus recargos de aleación de octubre para tubos. En euros, el 316/316L acabado en caliente/frío bajó de 5,07 €/5,59 € por kg (5.070 €/5.590 € por tonelada) a 5,05 €/5,56 € por kg (5.050 €/5.560 € por tonelada). Los materiales con alto contenido de Mo, con Mo superior al 2,5 %, descendieron de 5,26 €/5,79 € a 5,23 €/5,76 € por kg. Los recargos para el 2205 y el 2507 se mantuvieron sin cambios, mientras que el 254 SMO subió de 9,64 €/10,62 € a 9,67 €/10,65 € por kg. Análisis de SMM: la mayoría de los grados de tubo con Mo se mantuvieron estables o ligeramente a la baja, mientras que el 254 SMO avanzó, lo que indica una transmisión de costes diferenciada entre grados.
02 Oct 2026 10:52 (GMT+8)
[SMM Noticias de Acero Inoxidable] Los precios de la chatarra de acero inoxidable en India divergen: el 304 se relaja con el níquel y el 316, escaso, se mantiene firme
02 Oct 2026 10:50 (GMT+8)
[SMM Noticias de Acero Inoxidable] Los precios de la chatarra de acero inoxidable en India divergen: el 304 se relaja con el níquel y el 316, escaso, se mantiene firme
Leer más
[SMM Noticias de Acero Inoxidable] Los precios de la chatarra de acero inoxidable en India divergen: el 304 se relaja con el níquel y el 316, escaso, se mantiene firme
[SMM Noticias de Acero Inoxidable] Los precios de la chatarra de acero inoxidable en India divergen: el 304 se relaja con el níquel y el 316, escaso, se mantiene firme
El mercado de chatarra de acero inoxidable de la India se movió en distintas direcciones en la semana que terminó el 1 de octubre. Los precios internos de la chatarra 304 bajaron ligeramente y las ofertas de importación los siguieron, mientras que los precios del 316 se mantuvieron estables tanto en el mercado interno como en el de importación. La debilidad de los precios del níquel en la LME presionó el ánimo para el 304, y los compradores se limitaron a sus necesidades inmediatas mientras la actividad se desaceleraba durante el período festivo. La escasa disponibilidad limitó la caída del 316. En cuanto a las compras, los plazos de procesamiento reducidos tras la flexibilización por parte del gobierno de los requisitos del Certificado de Inspección Previa al Embarque (PSIC), junto con los costos adicionales de importación, siguieron limitando la flexibilidad de las plantas. Algunas plantas están evaluando palanquillas, planchones y arrabio de níquel (NPI) como alternativas a la chatarra para gestionar los costos de los insumos. Mirando más adelante, la propuesta de la UE de restringir las exportaciones de residuos metálicos a la India en virtud de su nuevo Reglamento sobre Traslados de Residuos (WSR), de adoptarse, reduciría aún más las opciones de importación de chatarra de la India. En el corto plazo, la chatarra 304 enfrenta una leve presión a la baja si el níquel se mantiene débil, mientras que se espera que el 316 se mantenga firme mientras la oferta siga siendo escasa. La evolución del PSIC y la economía relativa de las palanquillas y el NPI serán factores clave a observar.
02 Oct 2026 10:50 (GMT+8)
【Flash | Metallus aumenta el recargo de molibdeno de octubre para el acero 300M】
02 Oct 2026 10:47 (GMT+8)
【Flash | Metallus aumenta el recargo de molibdeno de octubre para el acero 300M】
Leer más
【Flash | Metallus aumenta el recargo de molibdeno de octubre para el acero 300M】
Metallus fijó sus recargos de materia prima de octubre para el período del 1 al 30 de octubre. El componente de Mo para el acero 300M subió un 0,52 % hasta 15,176 $/cwt, unos 334,57 $/t de acero, desde 15,098 $/cwt, o 332,85 $/t. El recargo total publicado aumentó un 1,03 % hasta 45,054 $/cwt. La chatarra subió a 17,750 $/cwt, mientras que el recargo energético independiente para barras y tubos bajó de 1,296 $/cwt, unos 28,57 $/t, a 0,050 $/cwt, o 1,10 $/t.
02 Oct 2026 10:47 (GMT+8)
[SMM Annual Report] Global Nickel Likely to be Oversupplied in 2023-2026E - Shanghai Metals Market (SMM)

