SHANGHAI, Dec 10 (SMM) - This is a roundup of China's metals weekly inventory as of December 10.
Aluminium Social Inventories Dropped 50,000 mt on Week
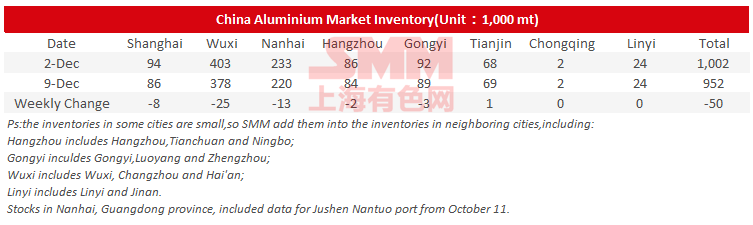
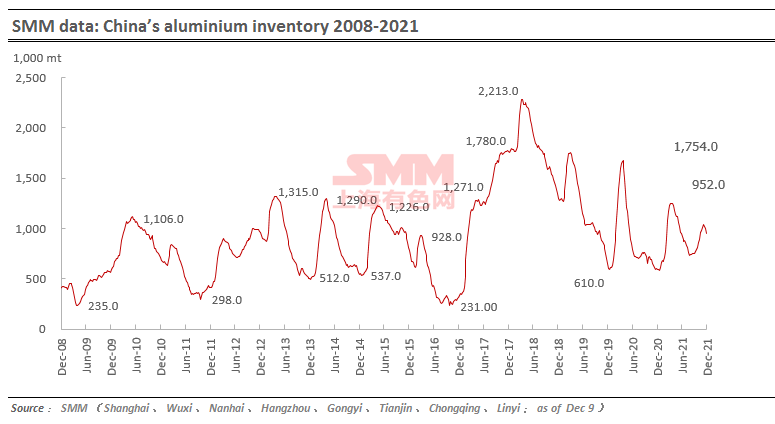
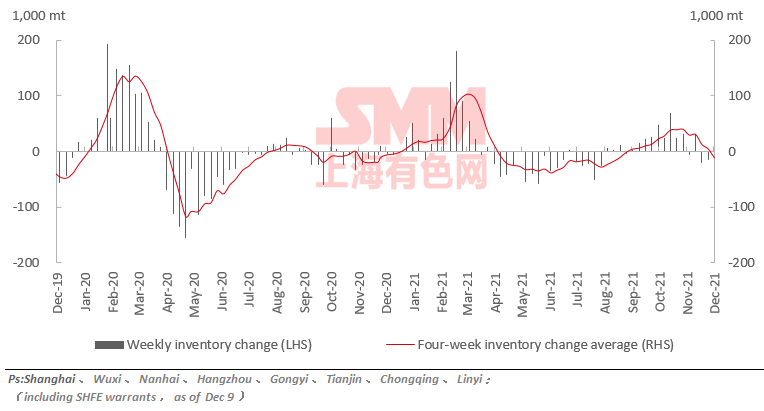
SMM data showed that China's social inventories of aluminium across eight consumption areas dropped 50,000 mt on the week to 952,000 mt as of December 9, mainly contributed by Wuxi, Nanhai and Shanghai. The inventory in Gongyi also declined on the week.
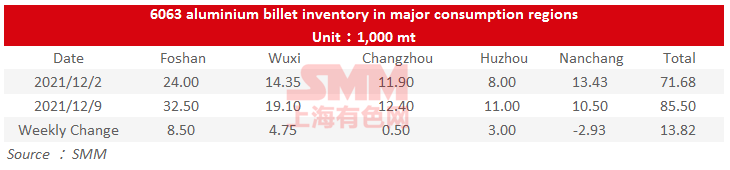
Aluminium Billet Inventories Up 13,800 mt on Week
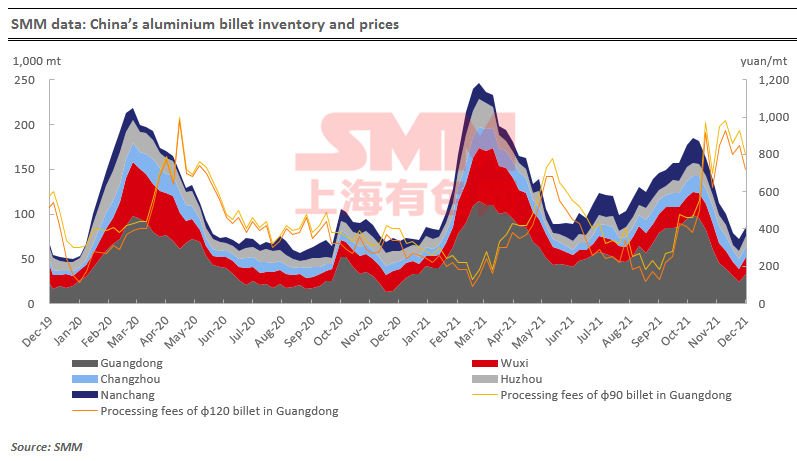
The stocks of aluminium billet in five major consumption areas rose 13,800 mt to 85,500 mt on December 9 from a week ago, an increase of 19.28%. The inventory finally reversed the downside trend which last seven consecutive weeks.
Only the inventory in Nanchang dropped by 2,900 mt or 21.82% from Thursday December 2. And other four major markets all saw increasing inventories, with Foshan contributing most of the increases of 8,500 mt (35.42%). The rising weekly inventory was mainly the result of more arrivals of aluminium billet and relatively sluggish downstream demand.
Looking into the future, the aluminium billet inventory is likely to be locked in the upside trajectory as downstream demand lacks growth engines.
Zinc Social Inventories Down 4,800 mt on Week
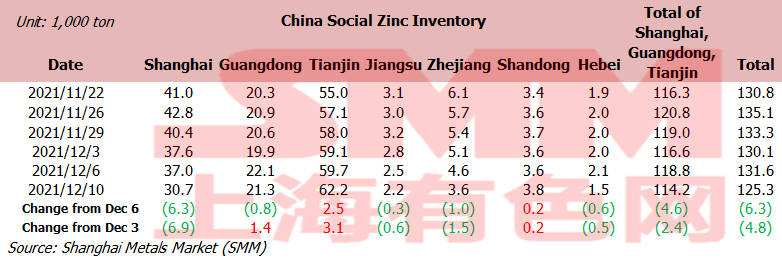
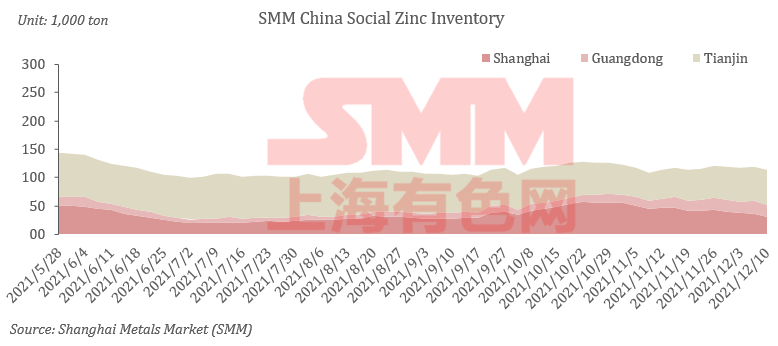
Total zinc inventories across seven Chinese markets stood at 125,300 mt as of December 10, down 6,300 mt from December 6 and 4,800 mt from December 3.
The inventory in Shanghai fell sharply as some major plants implemented maintenance, deliveries have been hindered by Covid-19 pandemic in Ningbo and the demand increased. Guangdong saw an increase in the overall inventory amid growing arrivals of goods in the spot market. The stocks in Tianjin continued to increase as demand from downstream producers weaked and some plants mainly consumed finished product inventory. Inventories in Shanghai, Guangdong and Tianjin fell 2,400 mt, and inventories across seven Chinese markets decreased 4,800 mt.
Copper Inventory in China Bonded Zone Declined 8,300 mt on Week
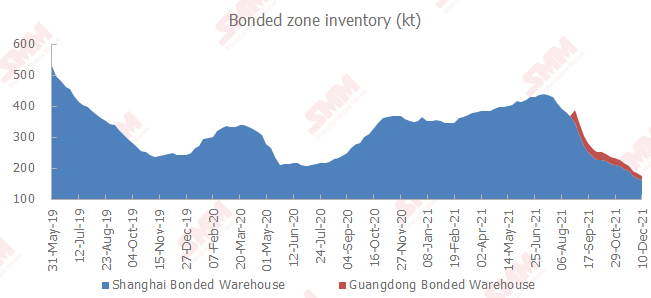
The copper inventories in the domestic bonded zones dipped 8,300 mt from December 3 to 175,200 mt as of Friday December 10, the ninth consecutive week of decline, according to the most recent SMM survey.
The inventory in the Shanghai bonded zone decreased 7,800 mt to 161,800 mt, and the inventory in the Guangdong bonded zone dipped 500 mt to 13,400 mt.
The import window remained open this week, driving the importers to move their cargoes under warrants into the domestic market. Meanwhile, the arriving shipments decreased due to the lower efficiency of port operations, driving the further decline in the bonded zone inventory.
Copper Inventories across Major Chinese Markets Dipped 1,100 mt
As of Friday December 10, the copper inventory across major Chinese markets dipped 1,100 mt from Monday to 90,100 mt.
The inventory decline was mainly seen in Jiangsu, mainly due to less shipments arrivals. The inventories increased across other major markets. The import window has remained open this week, driving continued inflows of imported cargoes. Meanwhile, the arriving shipments of domestic copper also increased after the domestic smelters resumed production. The supply pressure weighed on the spot quotes. The rally in the copper prices combined with the lower spot quotes sidelined downstream buyers, growing the inventories.

SHFE/LME Nickel Price Ratio Dipped amid Market Pessimism
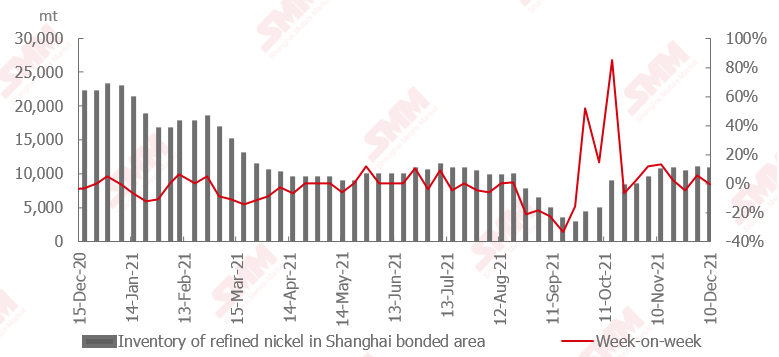
The SHFE/LME nickel price ratio fell from a high level this week. As SMM mentioned in the last edition of the weekly report, there was a lack of import opportunity due to a large volume of expected shipments arrivals and the current nickel prices which failed to boost the domestic demand.
The market will focus on the downstream consumption next week after the expected shipments of nickel plate arrive. Based on the demand this week, if the nickel prices remain high, the domestic social inventory will increase. And the SHFE/LME copper price ratio is unlikely to improve.
Silicon Metal Inventory Increased 7,000 mt on Week
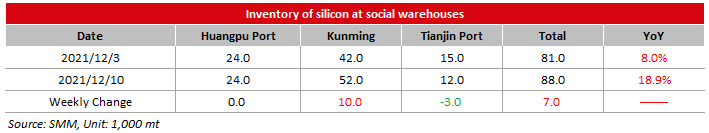
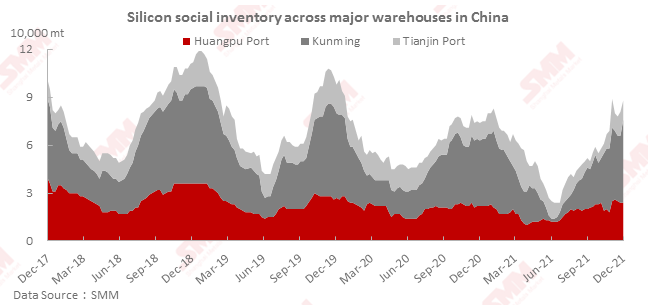
The social inventory of silicon metal across Huangpu port, Kunming city and Tianjin port increased 7,000 mt from the previous week to 88,000 mt as of Friday December 10.
The spot transactions of silicon metal were active this week. The arrivals at Tianjin Port were scattered in trucks, and the shipments were high, mostly of which for the domestic sales. In south China, the arrivals and shipments were basically balanced at Huangpu port, while the inventory in Kunming increased significantly due to intensive arrivals. Therefore, the total inventory across the country increased markedly.