Impact from high copper prices and secondary copper slowed recovery in copper rods produced with copper cathode

Publicado: Mar 23, 2021 10:27 (GMT+8)
Downstream cable companies have placed orders moderately amid price volatility previously. Weak copper demand resulted in slow delivery-taking, accumulating inventory of raw material or finished products at producers. That increased cash pressure at copper rod plants using secondary copper as feedstock, affecting secondary copper suppliers. Secondary copper suppliers have sold aggressively and collected payments to ease cash flow issues.

SHANGHAI, Mar 23 (SMM)—Downstream cable companies have placed orders moderately amid price volatility previously. Weak copper demand resulted in slow delivery-taking, accumulating inventory of raw material or finished products at producers. That increased cash pressure at copper rod plants using secondary copper as feedstock, affecting secondary copper suppliers. Secondary copper suppliers have sold aggressively and collected payments to ease cash flow issues. Cash flow issues are expected to intensify due to high tax payment in April. As such, factories and suppliers should liquidate stocks.
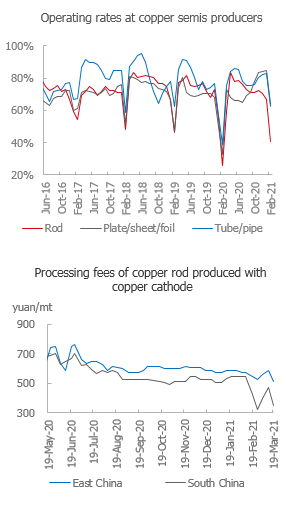
Operating rates at copper rod producers using secondary copper as raw material should return to a high level in March against accumulated orders, boosting secondary copper demand. However, decreased new orders at the end of last week and increased cash flow issues have limited the interest in purchasing. That combined with the demand for stock liquidation at suppliers, will keep normal supply and demand.

The average weekly price of #1 bare bright copper without invoice stood at 59,930 yuan/mt, an increase of 200 yuan/mt compared with the previous week, and the weekly average price difference between copper cathode and copper scrap stood at 2,217 yuan/mt, an increase of 385 yuan/mt. The average weekly discount of copper rod produced with secondary copper stood at 1,464 yuan/mt against the SHFE front-month copper contract, growing the advantage compared to copper rod produced with copper cathode.

For imported copper scrap, cif quotes for #1 copper scrap were Comex July copper less $0.21/lb, and offers for birch/cliff were Comex July copper less $0.36/lb. US brass was quoted at $5,650-5,850/mt. The coefficient for copper granules (98%) against LME copper stood at 93%, and the coefficient for bare bright copper against LME copper at 96-96.5%, on a cif basis.

Improved consumption of copper rod produced with secondary copper had significant impact on consumption of copper rod produced with copper cathode

Many producers of copper rod using secondary copper as feedstock have seen high orders, reporting strong supply and demand. The price spread between copper cathode and copper scrap has returned to above 2,000 yuan/mt, and discounts of copper rod produced with secondary copper reached a high of 1,550 yuan/mt against the SHFE front-month copper contract. Low-priced copper rods produced with secondary copper have been more desirable for downstream companies amid high copper prices, and this depressed consumption of copper rod produced with copper cathode which has been already weak. 

The impact of poor wire and cable demand and secondary copper rods has slowed recovery in the market of copper rod produced with copper cathode. Most of the producers are unlikely to return to normal production levels in March. As consumption picks up amid warmer weather, the market sentiment of the wire and cable industry should rise. Consumption of copper rods produced with copper cathode is expected to improve in April. However, the overly high copper price will depressed consumption. The current inventory of finished products at copper rod producers using copper cathode as feedstock stands at high levels. Producers will prioritise stock depletion and new orders at end users are unlikely to pass to copper rod plants using copper cathode as raw material any time soon. We believe that consumption of copper rods produced with copper cathode in April would hardly return to the peak season level of previous years.
Declaración de Fuente de Datos: Excepto la información disponible públicamente, todos los demás datos son procesados por SMM basándose en información pública, comunicación de mercado y confiando en el modelo de base de datos interna de SMM. Son solo para referencia y no constituyen recomendaciones para la toma de decisiones.

Para cualquier consulta o para obtener más información, por favor contacte: lemonzhao@smm.cn
Para más información sobre cómo acceder a nuestros informes de investigación, contacte con:service.en@smm.cn
Noticias relacionadas
El estudio de prefactibilidad del proyecto Iberian Belt West de Emerita muestra un VAN de 776 millones de dólares y una vida útil de mina de 21 años
30 Oct 2026 22:39 (GMT+8)
El estudio de prefactibilidad del proyecto Iberian Belt West de Emerita muestra un VAN de 776 millones de dólares y una vida útil de mina de 21 años
Leer más
El estudio de prefactibilidad del proyecto Iberian Belt West de Emerita muestra un VAN de 776 millones de dólares y una vida útil de mina de 21 años
Emerita publica el estudio de prefactibilidad del proyecto de zinc-plomo-cobre Iberian Belt West: VAN de 776 millones de dólares y 21 años de vida útil Emerita Resources (TSXV: EMO) publicó el 29 de octubre un estudio de prefactibilidad positivo para su proyecto polimetálico Iberian Belt West, de su entera propiedad, en la Faja Pirítica Ibérica de España. El estudio muestra un VAN después de impuestos de 776 millones de dólares al 8 %, una TIR del 23,51 %, una vida útil de la mina de 21 años y un período de recuperación después de impuestos de 1,9 años. La inversión inicial es de 567 millones de dólares, incluida la contingencia. Las reservas probables iniciales ascienden a 23,4 millones de toneladas con leyes de 2,30 % de zinc, 1,13 % de plomo, 0,45 % de cobre, 53 g/t de plata y 1,07 g/t de oro.
30 Oct 2026 22:39 (GMT+8)
El mercado del cobre enfrenta cambios fiscales y escasez de suministro en octubre de 2026
30 Oct 2026 19:47 (GMT+8)
El mercado del cobre enfrenta cambios fiscales y escasez de suministro en octubre de 2026
Leer más
El mercado del cobre enfrenta cambios fiscales y escasez de suministro en octubre de 2026
En octubre de 2026, el diferencial de precios con impuestos incluidos entre el metal primario y la chatarra se redujo de 3.979 yuanes/tm al inicio de la semana a 1.896 yuanes/tm, para luego recuperarse hasta el rango de 2.826-2.976 yuanes/tm. La diferencia de precios entre la varilla de cobre catódico y la varilla de cobre secundario también se comprimió de 1.250 yuanes/tm a un mínimo extremo por debajo de 430 yuanes/tm antes de rebotar a 1.450 yuanes/tm. Aunque la ventaja de sustitución contable fluctuó, en la mayor parte del tiempo se vio erosionada por factores de coste.
30 Oct 2026 19:47 (GMT+8)
Price Increases Suppress Reorders, Operating Rates Pull Back, Making Rebound Hard to Sustain [SMM Analysis]
30 Oct 2026 18:41 (GMT+8)
Price Increases Suppress Reorders, Operating Rates Pull Back, Making Rebound Hard to Sustain [SMM Analysis]
Leer más
Price Increases Suppress Reorders, Operating Rates Pull Back, Making Rebound Hard to Sustain [SMM Analysis]
30 Oct 2026 18:41 (GMT+8)