[SMM Thread Analysis] three increases in post-section inventory, with a higher-than-expected increase

Publicado: Oct 10, 2019 17:53
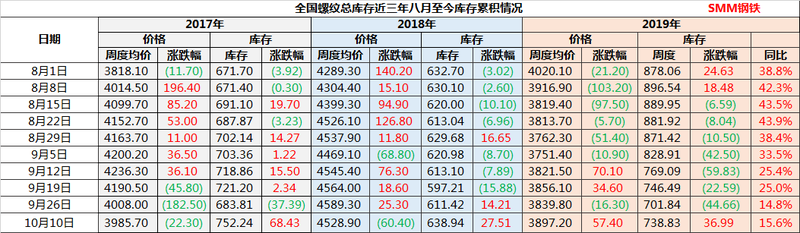
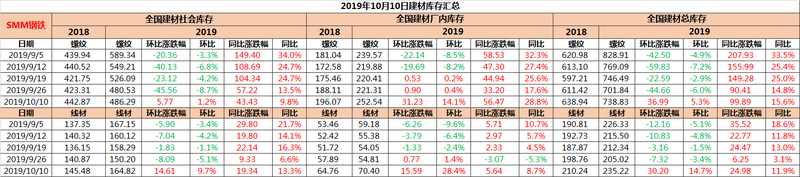
[the national thread inventory increased three times after the festival, and the total warehouse increased by 369900 tons] this week, the national thread stock was 7.3883 million tons, an increase of 369900 tons (+ 5.3%) over the week before the festival, and + 15.6% from the same period last year. Among them, the factory inventory was 2.5254 million tons, an increase of 312300 tons (+ 14.1%) over the week before the festival, + 28.8% from the same period last year. Social inventory was 4.8629 million tons, an increase of 57700 tons (1.2 percent) over the previous week, and + 9.8 percent from the same period last year.

This week, the total thread warehouse of the whole country was 7.3883 million tons, an increase of 369900 tons (+ 5.3 percent) over the week before the festival, and + 15.6 percent from the same period last year. Among them, the factory inventory was 2.5254 million tons, an increase of 312300 tons (+ 14.1 percent) over the week before the festival, and + 28.8 percent compared with the week before the festival. Social inventory was 4.8629 million tons, an increase of 57700 tons (1.2 per cent) over the week before the festival, and + 9.8 per cent from the same period last year. At the end of the 70th anniversary of Daqing, the national thread inventory changed from decrease to increase. There are two reasons, first, the end of production restrictions, superimposed profits rebounded, some areas of steel enterprises re-hot start. Supply pressure could make a comeback. Second, Daqing, the market holiday, terminal access to goods is limited, the speed of demand release is greatly reduced. Combined with the above reasons, thread inventory is expected to increase by three.


Although the social treasury has returned to the trend of accumulation, the demand for the National Day holiday has been blocked, and two days after the festival, the terminal pickup mentality is more cautious because of the expected inventory deviation, and transportation has not yet fully recovered, the increase of 57700 tons is lower than the increase of 195600 tons in the same period last year, exceeding market expectations, showing the tenacity of the demand for building materials. Therefore, demand is still the support. On the supply side, although Daqing environmental protection production restrictions have come to an end, but the bugle of the autumn and winter heating season has slowly sounded, Tangshan yesterday issued an autumn and winter production restriction notice, in addition to three A and B grade steel enterprises, the rest of the steel production limits range from 20% to 55%. In the aspect of short process, the scrap resources are tight, the profit situation is still not ideal, and the power to resume production is insufficient. As a result, the supply side has not yet returned to the peak of full production.

To sum up, demand in the peak season, supply is still restrained, the next two weeks fundamentals may still be better, thread spot short-term or show a strong shock trend. It should be noted that China and the United States will hold consultations again today and tomorrow, and the concrete results will once again affect the market mentality.


Declaración de Fuente de Datos: Excepto la información disponible públicamente, todos los demás datos son procesados por SMM basándose en información pública, comunicación de mercado y confiando en el modelo de base de datos interna de SMM. Son solo para referencia y no constituyen recomendaciones para la toma de decisiones.

Para cualquier consulta o para obtener más información, por favor contacte: lemonzhao@smm.cn
Para más información sobre cómo acceder a nuestros informes de investigación, contacte con:service.en@smm.cn
Noticias relacionadas
Australia revisa los derechos antidumping sobre el acero galvanizado de India, Malasia y Vietnam ante la preocupación por el zinc
11 Sep 2026 18:30
Australia revisa los derechos antidumping sobre el acero galvanizado de India, Malasia y Vietnam ante la preocupación por el zinc
Leer más
Australia revisa los derechos antidumping sobre el acero galvanizado de India, Malasia y Vietnam ante la preocupación por el zinc
El 9 de septiembre de 2026, Australia inició su segunda revisión por extinción de las medidas antidumping sobre la chapa de acero galvanizado procedente de India, Malasia y Vietnam, y abrió por separado una revisión por extinción de las medidas compensatorias sobre las importaciones procedentes de India. La revisión abarca el período de julio de 2025 a junio de 2026, y se prevé que el informe final se publique antes del 11 de febrero de 2027. Dado que el acero galvanizado es el principal sector de uso final del zinc, las medidas afectan directamente a los costes de exportación y a la competitividad, lo que podría repercutir en la demanda interna de zinc de Australia y en su cadena de suministro. El mantenimiento de los derechos ofrecería cierta protección a la capacidad nacional de producción de acero y de recubrimiento, mientras que su supresión podría aumentar las importaciones a bajo precio y afectar al consumo regional de zinc. El resultado final sigue sujeto a la determinación de las autoridades.
11 Sep 2026 18:30
El proyecto de expansión de 200 millones de dólares de JCC Hongyuan Copper busca aumentar la capacidad a 550.000 toneladas métricas para 2027
7 Sep 2026 15:43
El proyecto de expansión de 200 millones de dólares de JCC Hongyuan Copper busca aumentar la capacidad a 550.000 toneladas métricas para 2027
Leer más
El proyecto de expansión de 200 millones de dólares de JCC Hongyuan Copper busca aumentar la capacidad a 550.000 toneladas métricas para 2027
El proyecto de ampliación de 300.000 t/año de cátodos de cobre de JCC Hongyuan Copper, filial de Jiangxi Copper Corporation, entró el 4 de septiembre en la fase de aviso público previo a la aprobación de su evaluación de impacto ambiental, con una inversión total de aproximadamente 1.416 millones de yuanes. Está previsto que la construcción comience en septiembre de 2026 y concluya en diciembre de 2027. Una vez finalizado, la capacidad total de JCC Hongyuan pasará de 250.000 t a 550.000 t.
7 Sep 2026 15:43
El yen japonés se fortalece y el USD/JPY cae por debajo de 159 ante la especulación de intervención
3 Sep 2026 19:00
El yen japonés se fortalece y el USD/JPY cae por debajo de 159 ante la especulación de intervención
Leer más
El yen japonés se fortalece y el USD/JPY cae por debajo de 159 ante la especulación de intervención
[SMM Precious Metal Express] El yen japonés se disparó bruscamente durante la sesión del miércoles, con el USD/JPY cayendo por debajo de 159 y cerrando con una baja del 0,92% en 158,69, lo que desató especulaciones sobre una intervención cambiaria japonesa. El índice del dólar también cayó con fuerza, y un entorno de dólar más débil brindó soporte a los metales preciosos.
3 Sep 2026 19:00

